Latest from BCA Research
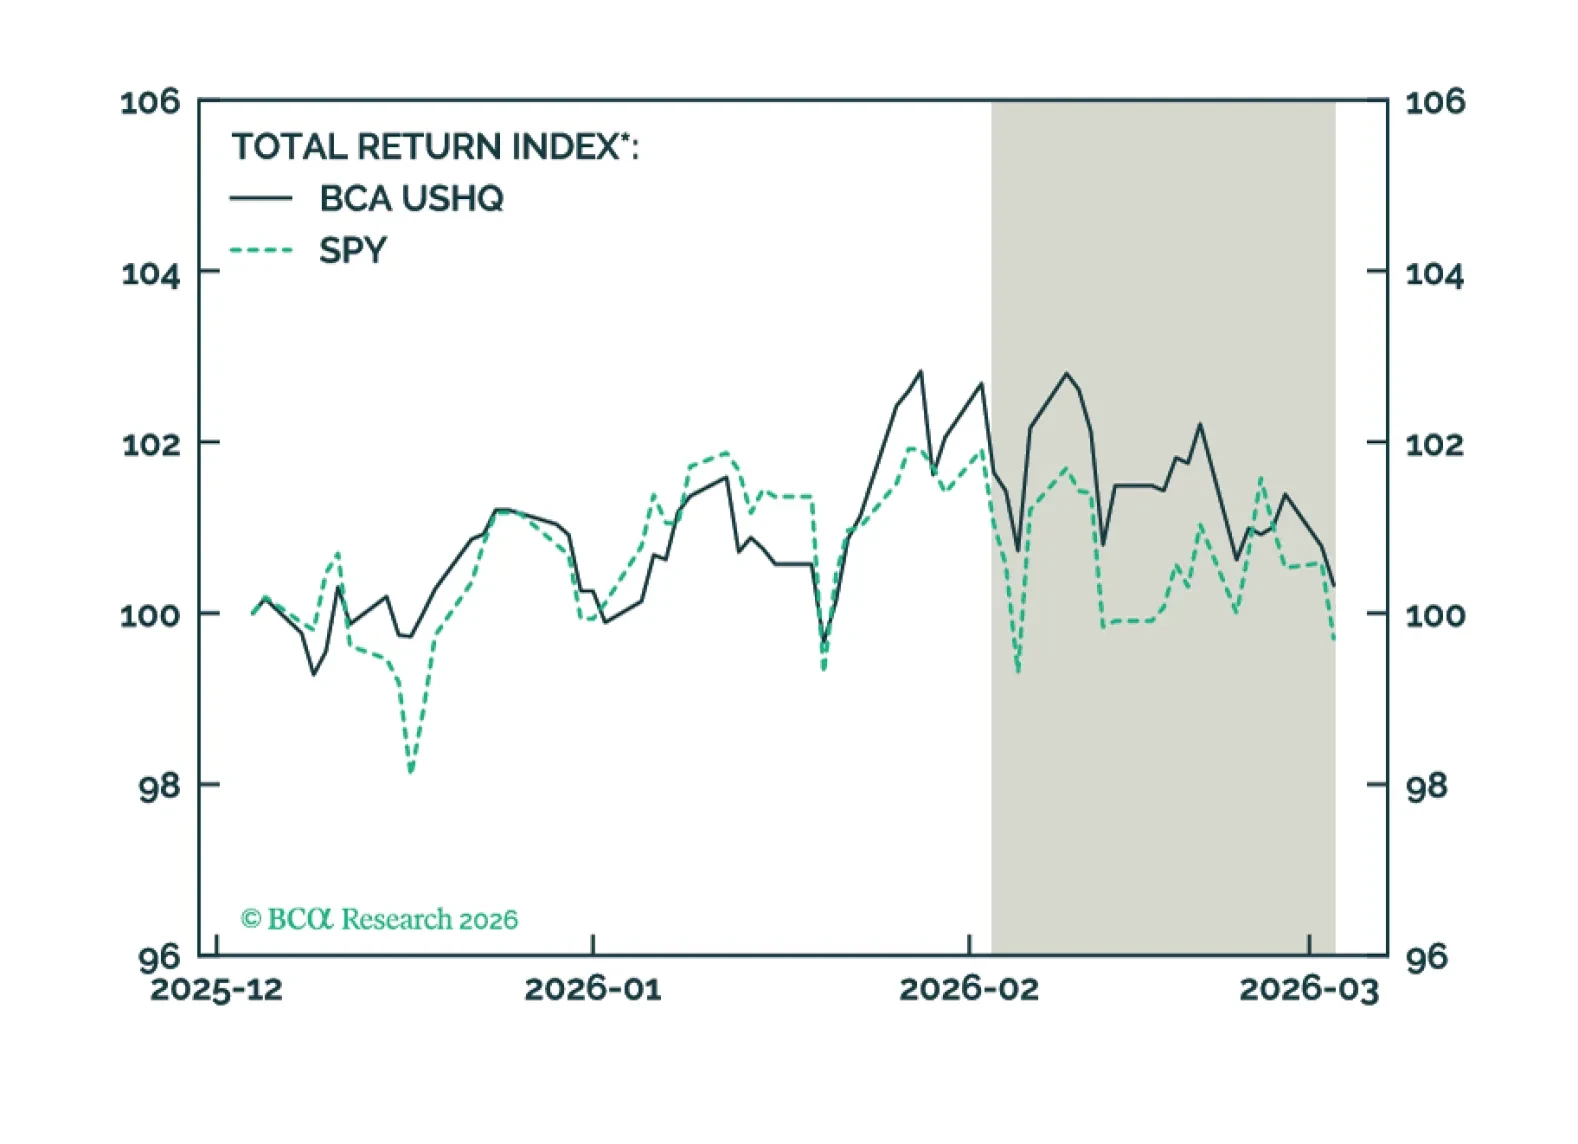
The US High Quality portfolio continues to outperform its benchmark through February, returning -1.29%, while its SPY benchmark returned -1.33%. On a trailing three-month basis, the USHQ portfolio’s performance was stronger than the benchmark as well, with USHQ outperforming by approx. 63bps.
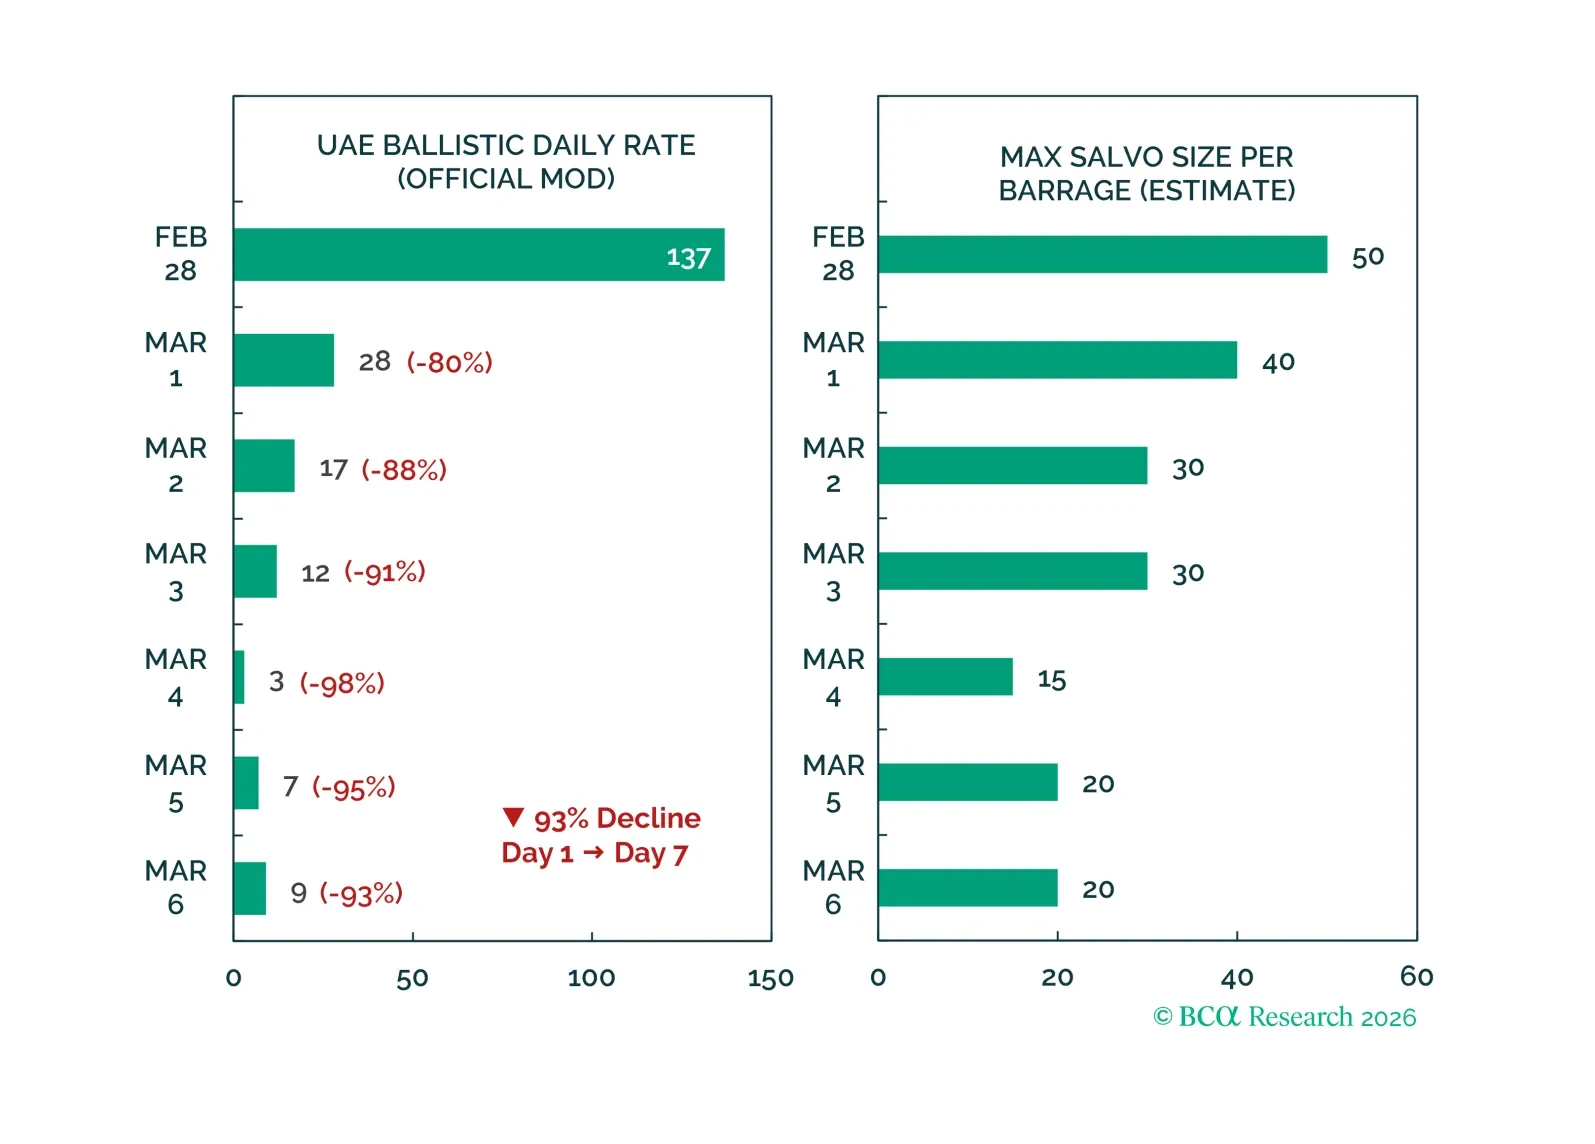
Instead of a normal missive, I am sending all my clients today a very lightly edited internal email that I just shared with the whole firm. I hope that it illustrates to you some of the … “fear”… that we all share with each other behind closed doors here at BCA Research as colleagues and teammates. Hopefully you see some of it in our research as well. That “cold sweat” is a necessary part of anyone in research and strategy roles. Once we lose it, we become disconnected from our clients who are in the trenches and the frontlines.

Looking through month-to-month volatility, job growth’s underlying trend is stable and consistent with a flat-to-slightly higher unemployment rate.
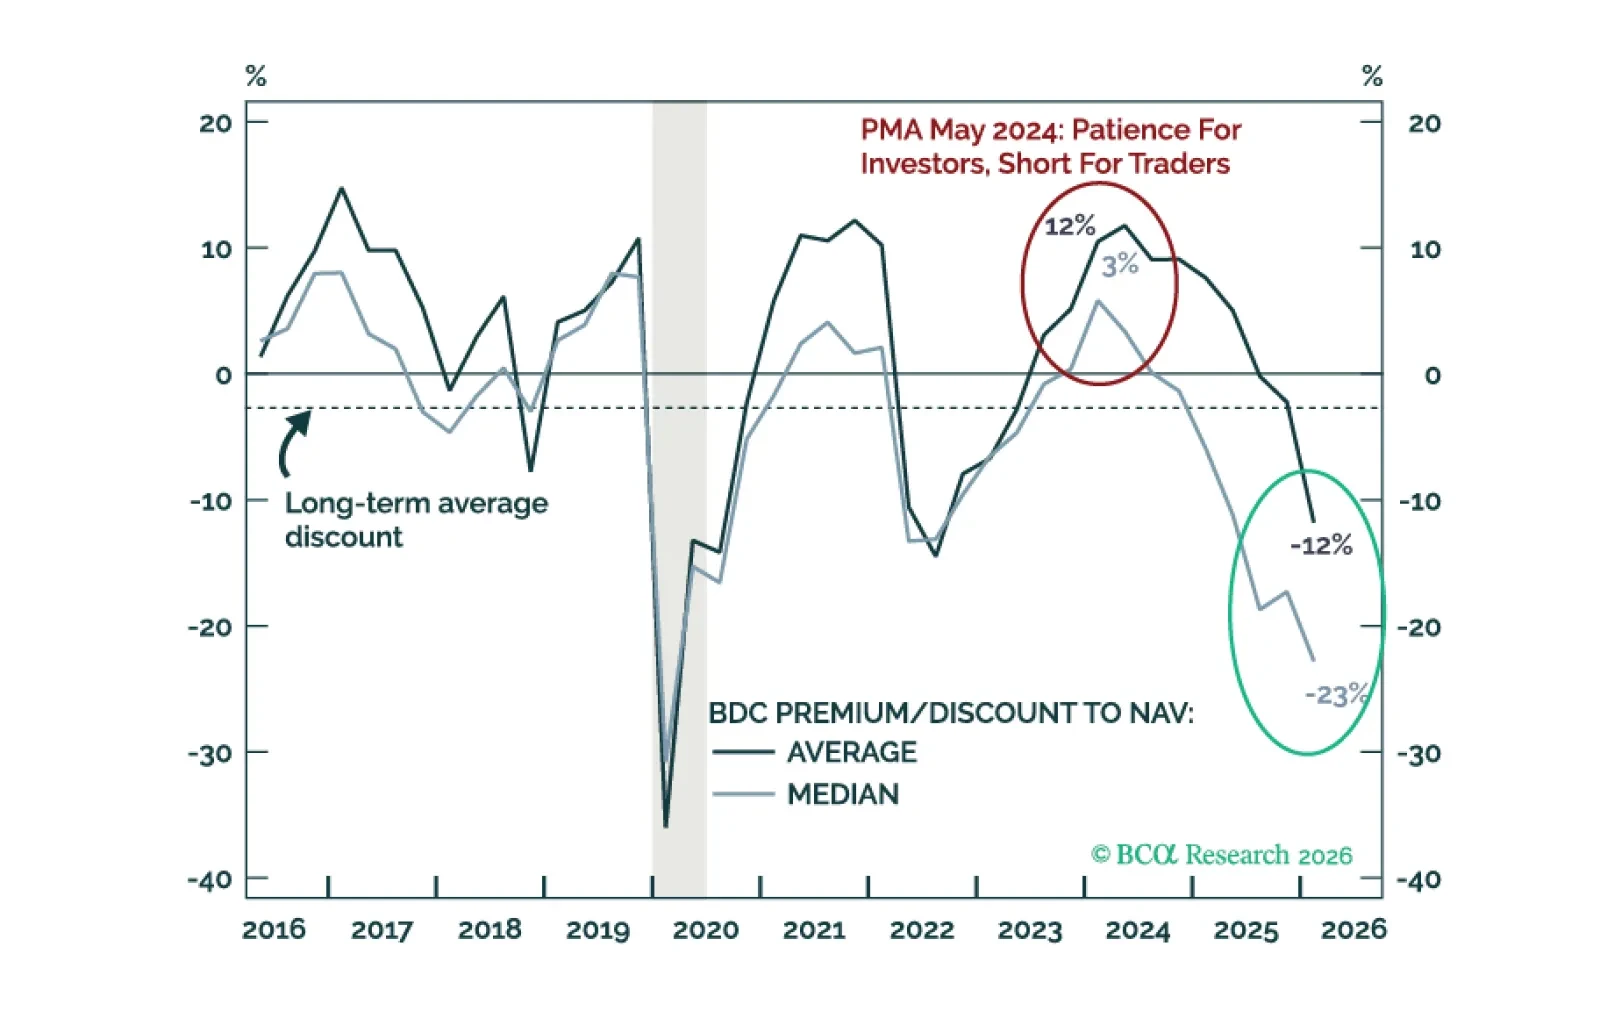
Everyone has opinions on Private Credit, but few have the data, and fewer have the objectivity. We give you both. In under 5 minutes, you will understand how we got here and, more importantly, how to allocate from here.

Avoid EM and DM risk assets. In the near term (one-to-three months), the odds favor US equity outperformance and a US dollar rebound. Nevertheless, the cyclical outlook (nine-to-12 months) warrants underweighting US equities and staying short the greenback.

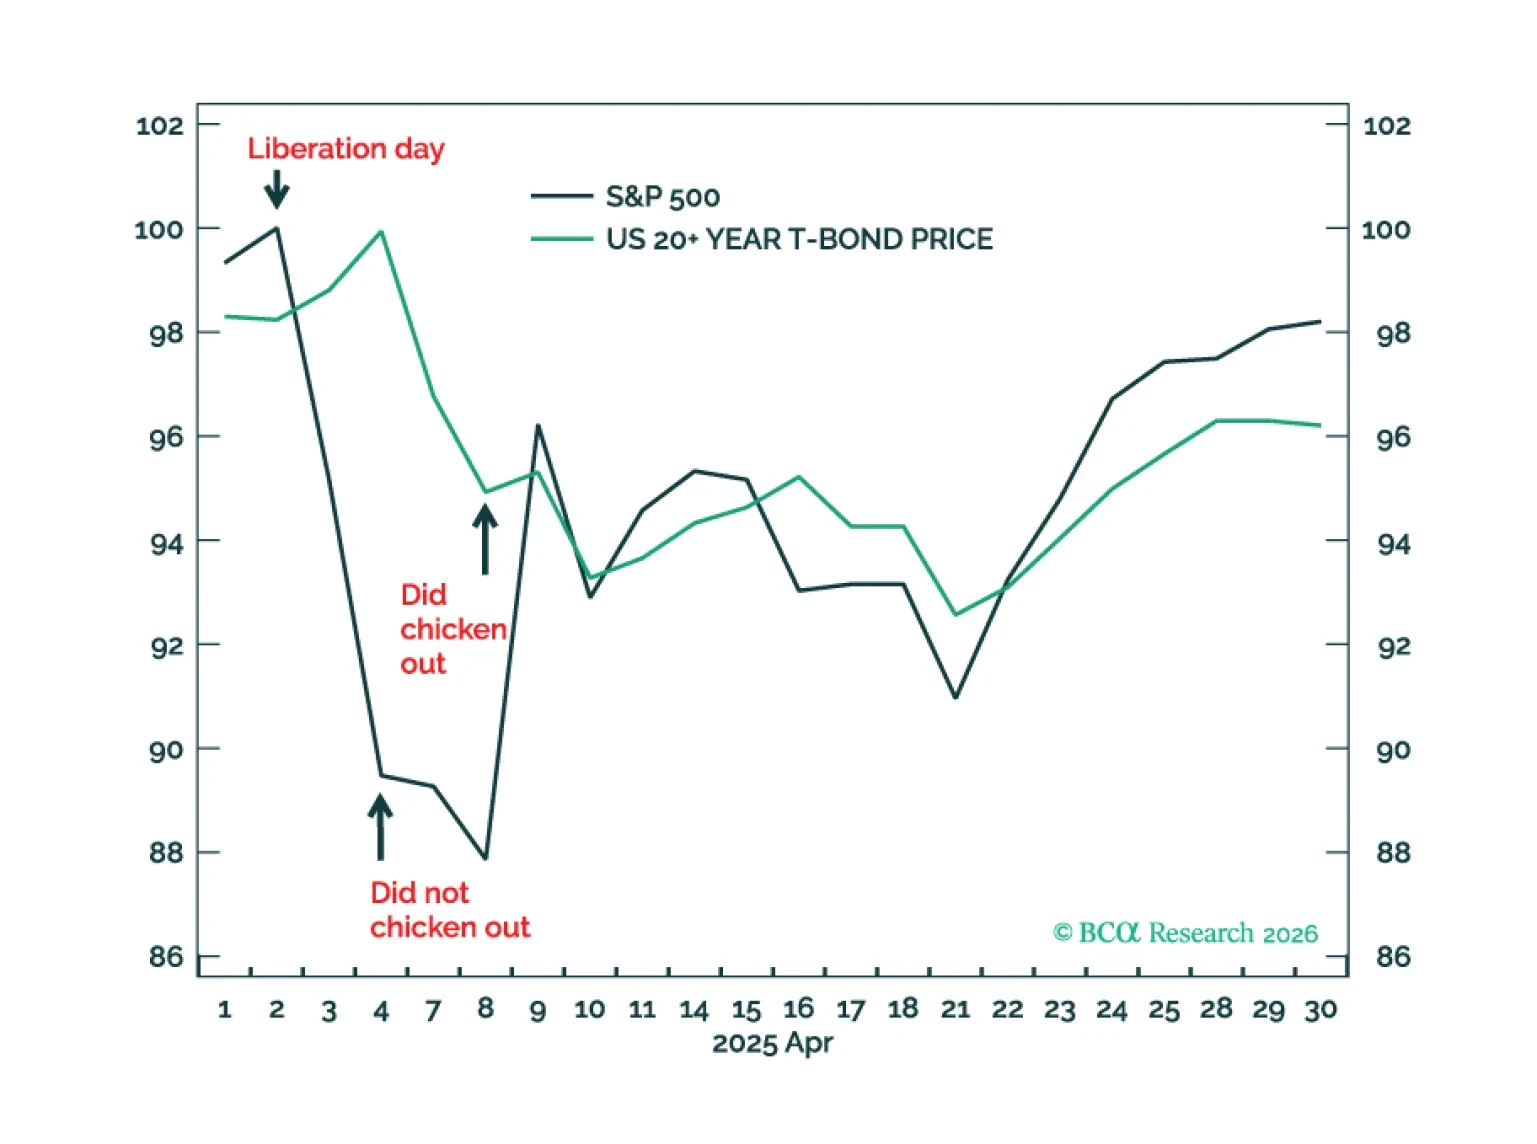
Iran doesn’t need to sink a single US warship; it could inflict much more damage by sinking the US stock and bond markets by disrupting shipping, trade, and oil tankers with decentralised low-tech drone warfare. We discuss why it is not the direct pain of higher oil prices, but the knock-on repercussions for stock and bond markets that could inflict the greater damage. Plus, a new tactical trade is to underweight Materials.


A key risk to our view has materialized. Our base case remains constructive, but risks have increased. Upgrade Tail Risk Strategies from overweight to max overweight. Upgrade Canadian equities and the Canadian dollar to overweight. Upgrade Australian equities and the Australian dollar to overweight.

Clients are universally asking us when we expect President Trump to activate the legendary “Trump Put.” We believe that the S&P 500 would have to correct by more than 10% to practically guarantee a put. We are open minded that it could occur before; it could also occur later. But a double-digit stock price decline will certainly be a greater motivator.