Latest from BCA Research


The labor market showed signs of reviving in the first three months of this year, but it is yet to be determined how consumers will react to the energy supply shock. We reiterate our benchmark asset allocation recommendations, but are skeptical that S&P 500 earnings growth will meet outsized expectations over the rest of 2026.
President Trump has announced that the US would impose a blockade on the Strait of Hormuz, in effect exacerbating the partial blockade that has already been in place due to Iran’s threats against shipping in the Persian Gulf. The threat comes after the direct negotiations between Iran and the US in Islamabad failed to make a breakthrough. Oil is up on the news and stock futures are down. How should investors read the situation?

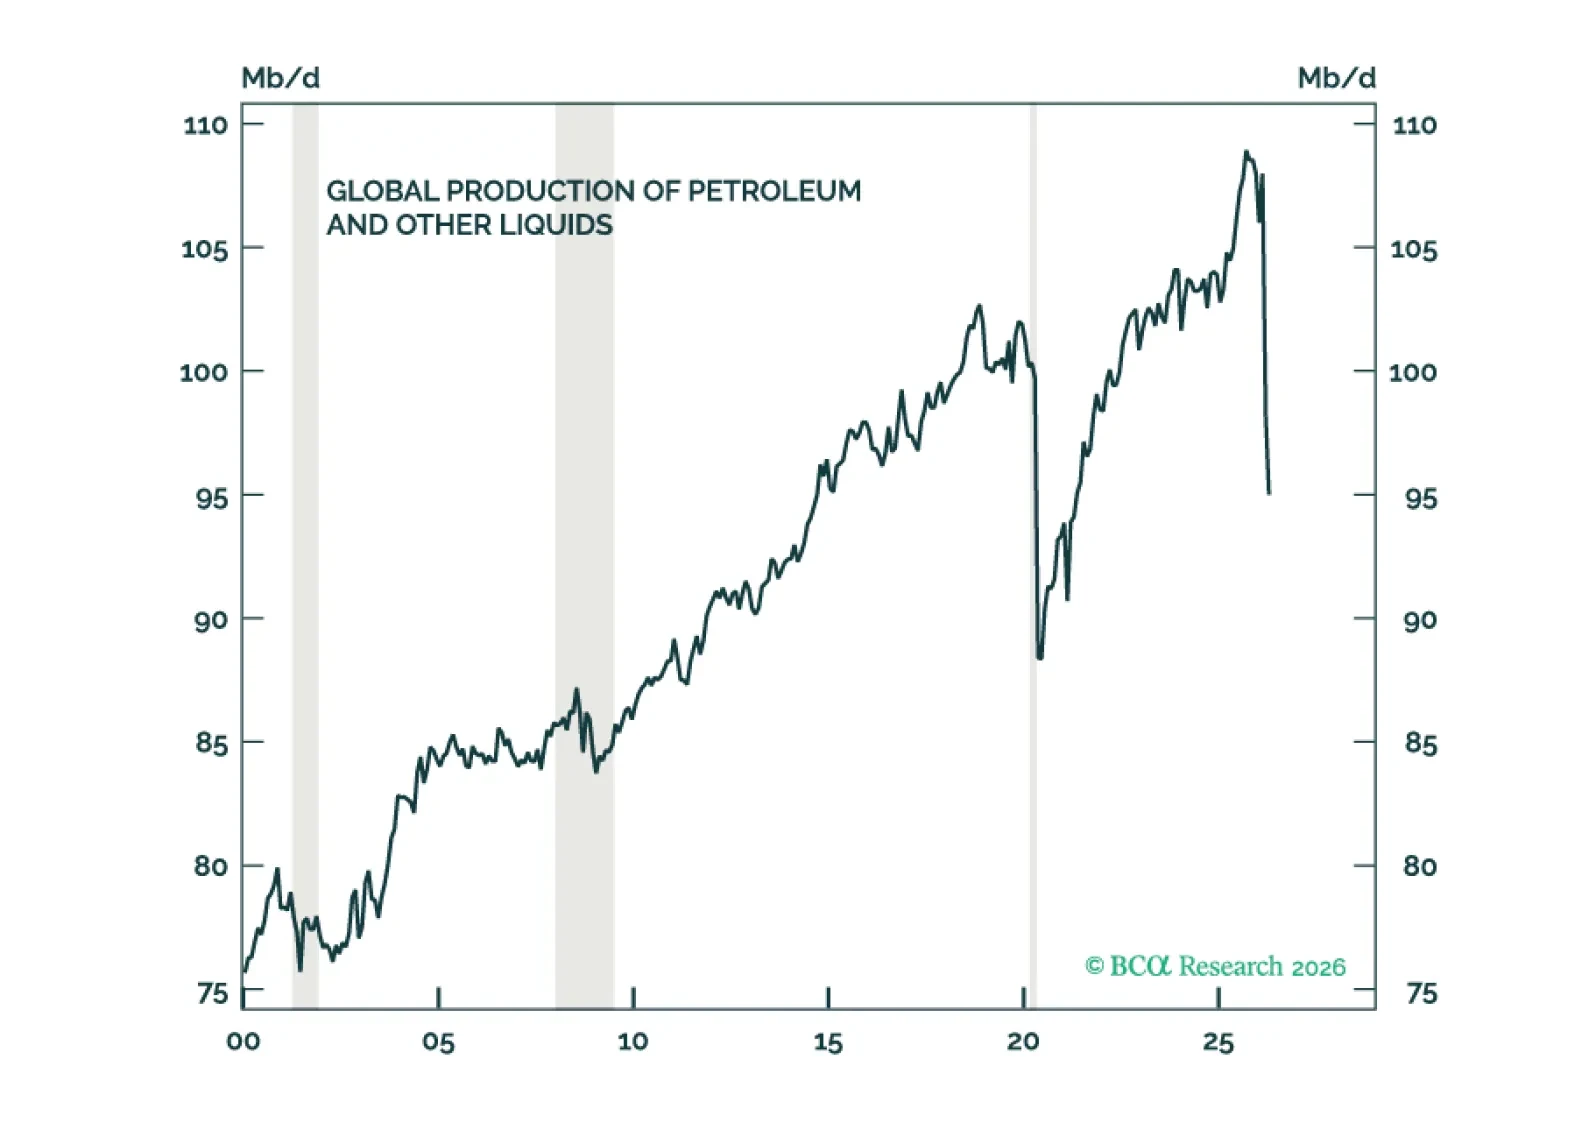
In this report, we deviate from our base case and instead assume that there is an immediate improvement in Hormuz traffic. This exercise allows us to explore how the global oil supply shortfall could eventually be offset if the right conditions are in place.
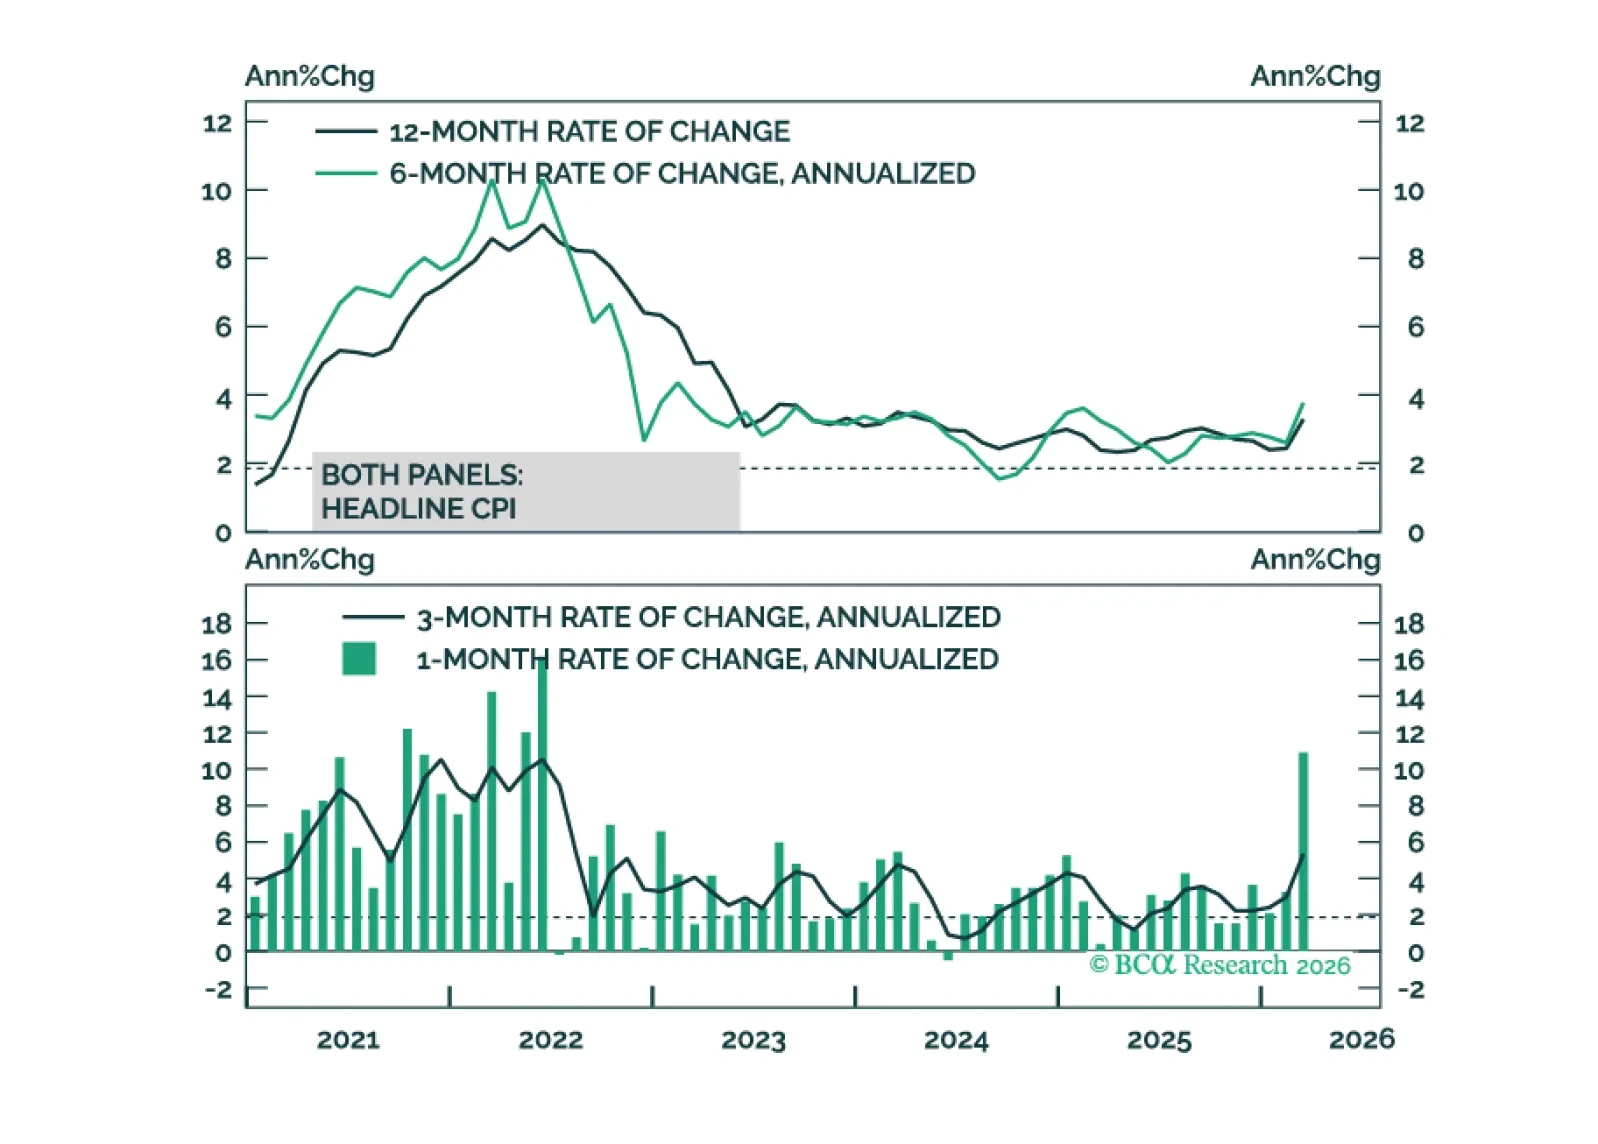
Inflation’s underlying trend was headed lower prior to the Iran war. This makes the recent back-up in bond yields look like an attractive buying opportunity.
The relief rally in stocks can continue a while longer. However, much can still go wrong. As such, we are retaining a 12-month underweight to stocks but are moving to neutral on a short-term tactical horizon.

Outside Asian semiconductor producers, EM corporate earnings and profitability have seen little improvement. Despite the ceasefire in the Middle East, the medium-term outlook for EM stocks is still unattractive.

We remain overweight APAC in both Private Equity and Venture Capital, recognizing the region and its opportunities have evolved meaningfully. Buyouts are growing faster than many realize, driven by Japan, while a deeper reset in fundamentals versus global markets supports stronger upside potential.

Trump’s breaking point is encapsulated by the combined drawdown in stocks plus bonds reaching 12-15 percent. On this basis, we describe how to ‘trade Trump’. Plus, we highlight three positions that should do well independent of Trump’s actions, including a new trade.

The ceasefire announced on Tuesday may signal peak intensity in the Middle East crisis, but sustained energy price pressures will continue to challenge Chinese corporate profitability.