Latest from BCA Research

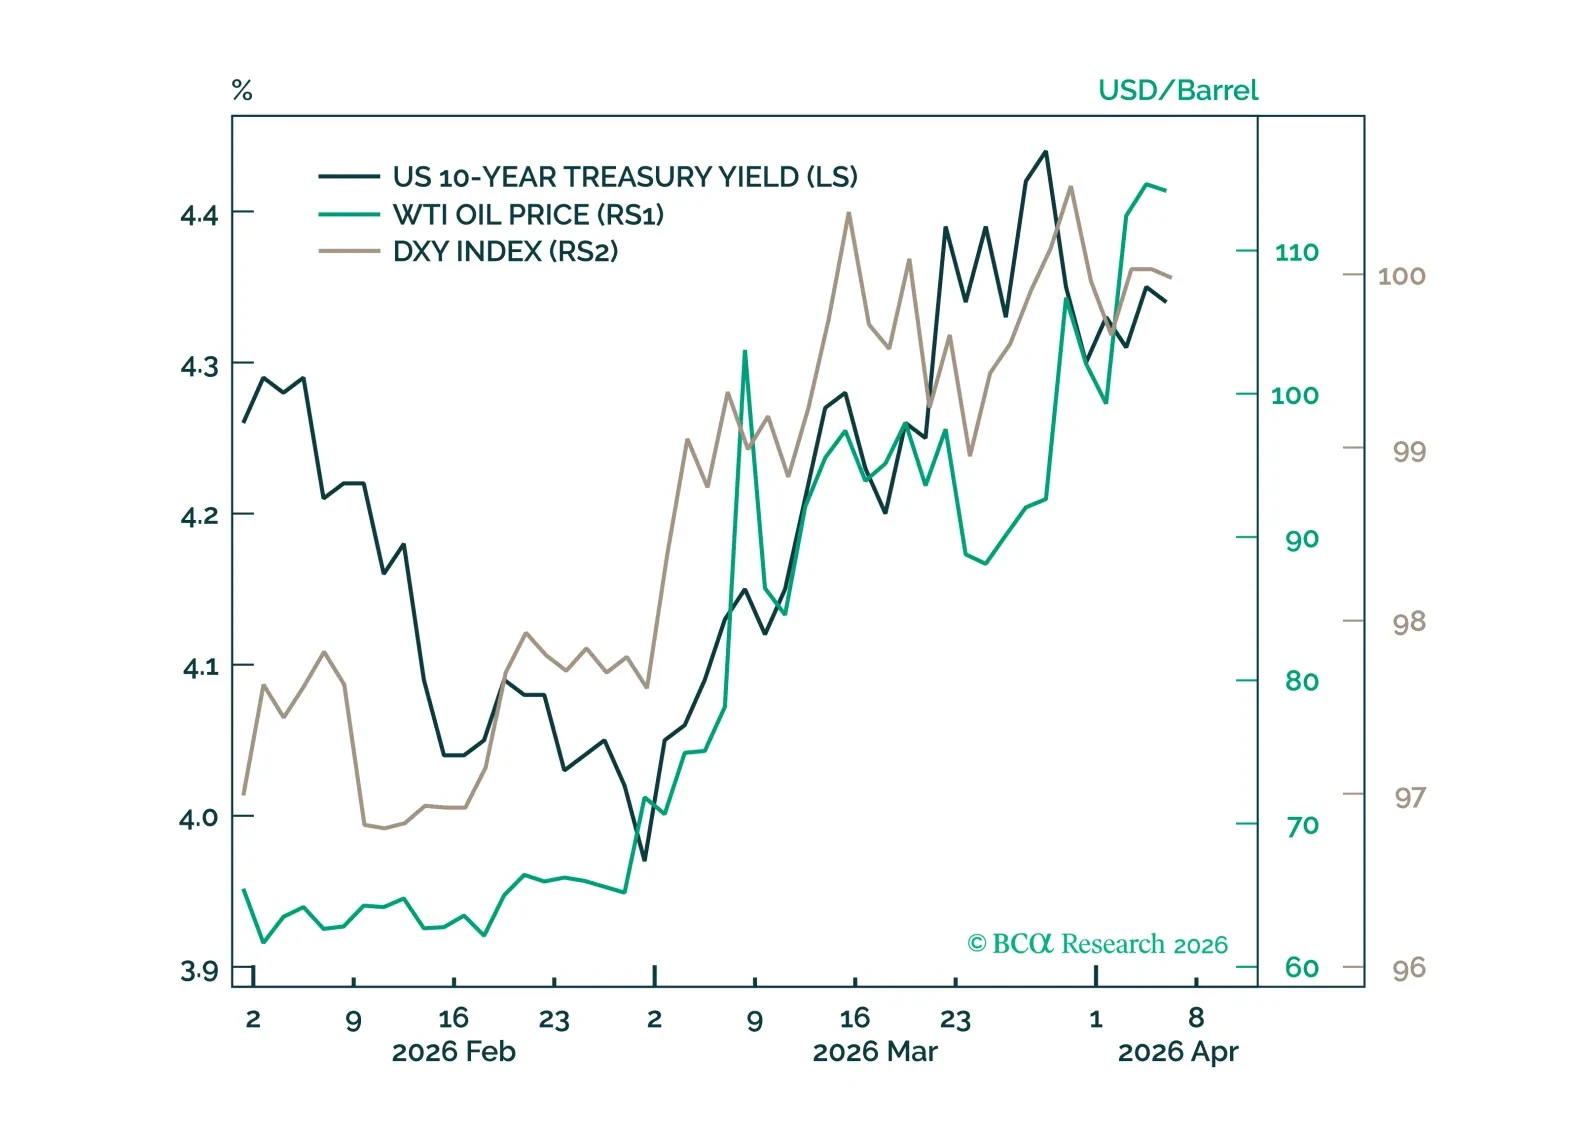
As we publish this regularly scheduled GeoMacro Alpha Report, President Trump is warning of civilization-ending strikes against Iran. A bluff? Stage Five on the Seven Steps of Maximum Pressure? A real threat to use weapons of mass destruction? The odds and pattern of Trump's behavior are skewed towards the former, but even small odds of the latter make trading the next 24 hours dangerous.

Domestic politics suggest that President Trump needs to retreat from the war in Iran, but strategic factors suggest not. Stay defensive for now.


US employment data show some tentative signs of job growth acceleration and stable utilization. We see breakeven monthly job growth as closer to +30k per month than zero.
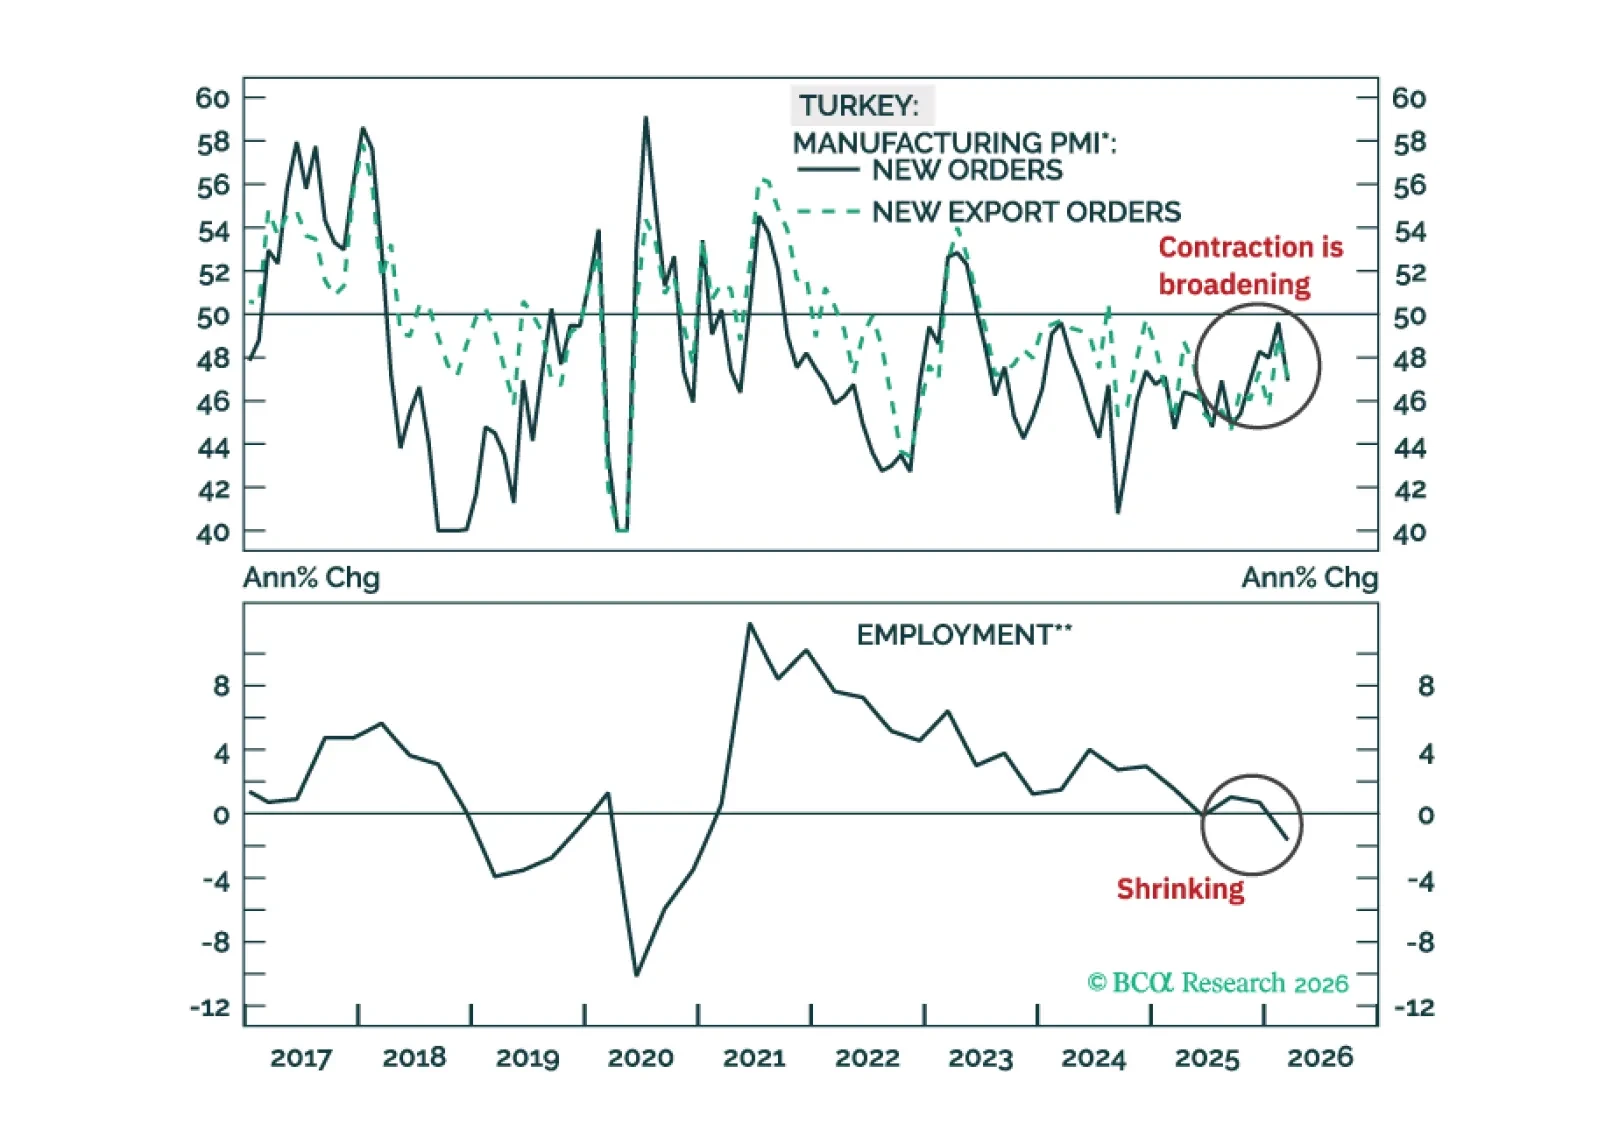
The Turkish financial markets will struggle in the very near term, but beyond that, the cyclical disinflation process will resume. Fixed-income investors should put Turkish 2-year local currencybonds on a ‘buy’ watch list.

The US High Quality (USHQ) portfolio continues to outperform its benchmark through March, returning -2.49%, while its SPY benchmark returned -3.34%. On a trailing three-month basis, the USHQ portfolio’s performance was stronger than the benchmark as well, with USHQ outperforming by approx. 208bps.

We expect the S&P 500 to deliver $308 of EPS in 2026, with a year-end target of 7700. Revenue growth drives upside, with little margin or multiple expansion. With economic growth tilted toward investment, we are overweight Technology, Industrials, and Materials, market-weight Financials, Energy, Health Care, Communication Services, and Real Estate, and underweight Consumer Staples, Consumer Discretionary, and Utilities.

Our "miniature stagflation" episode is coming together on the back of the Iran shock, China slowdown, and American political division.

The global risk-off phase will persist. It is too early to buy local-currency bonds in Mainstream EM, but it is not too late to sell EM sovereign and corporate credit (USD bonds).