FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
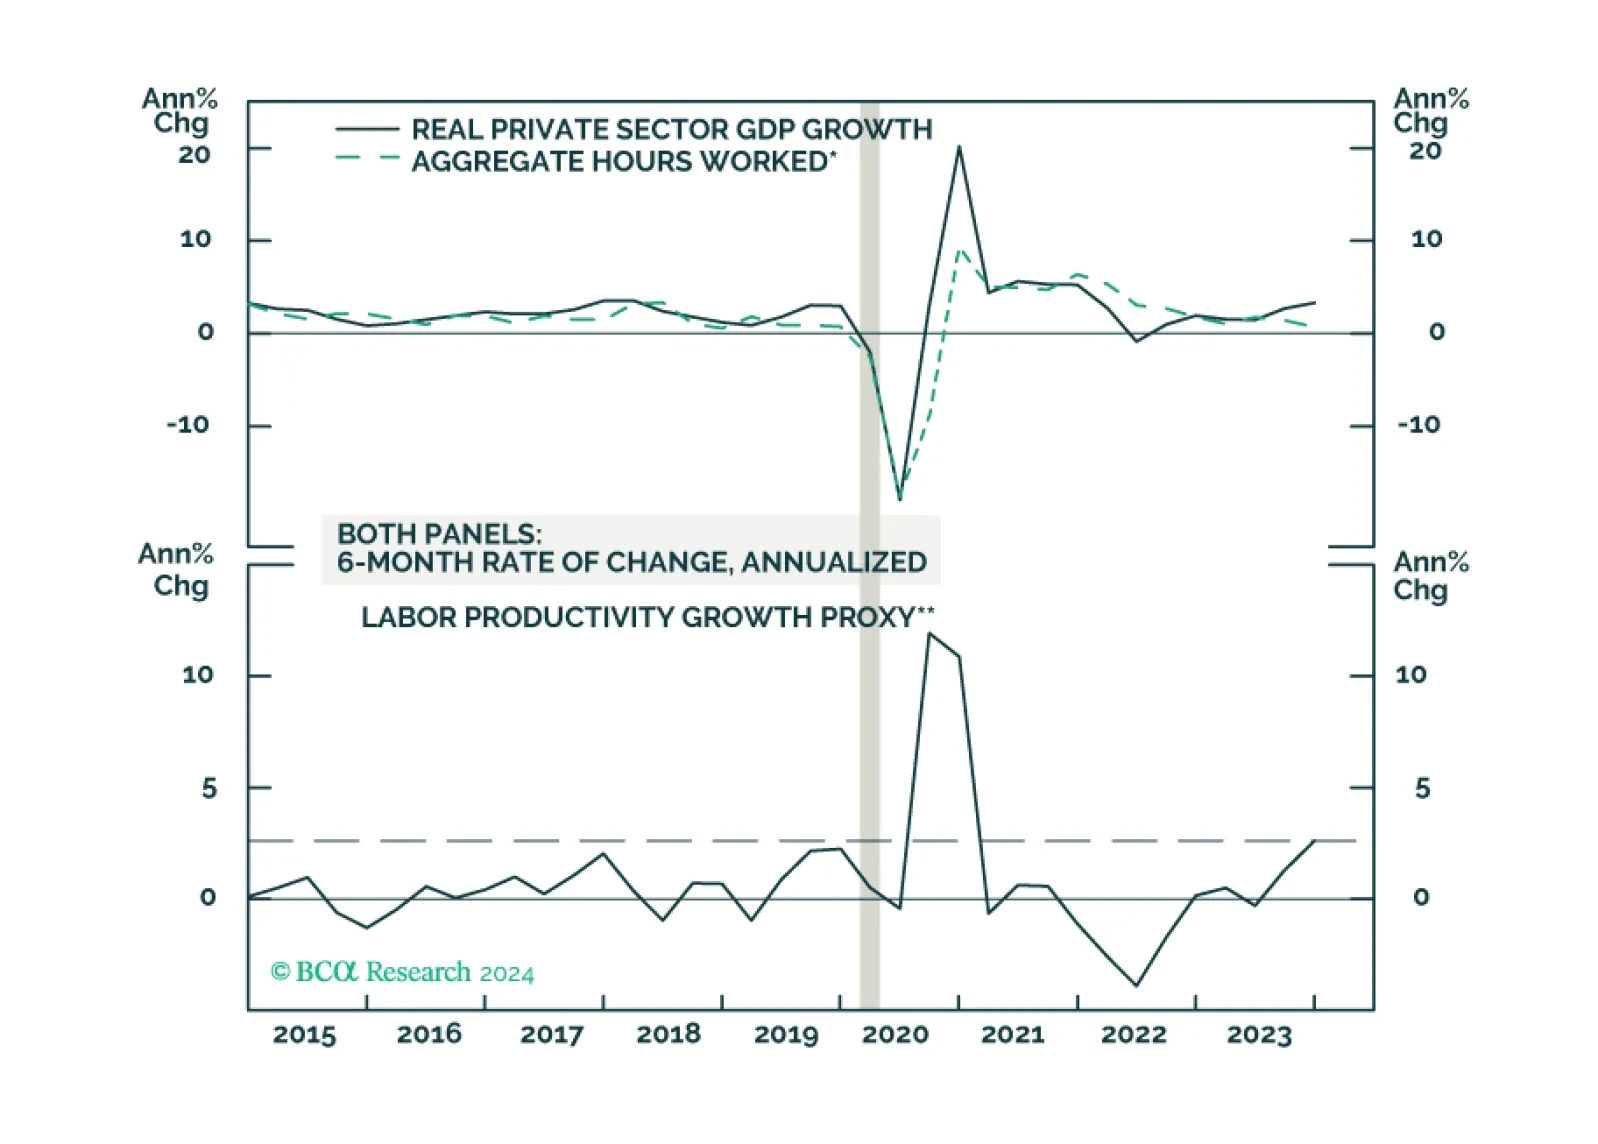
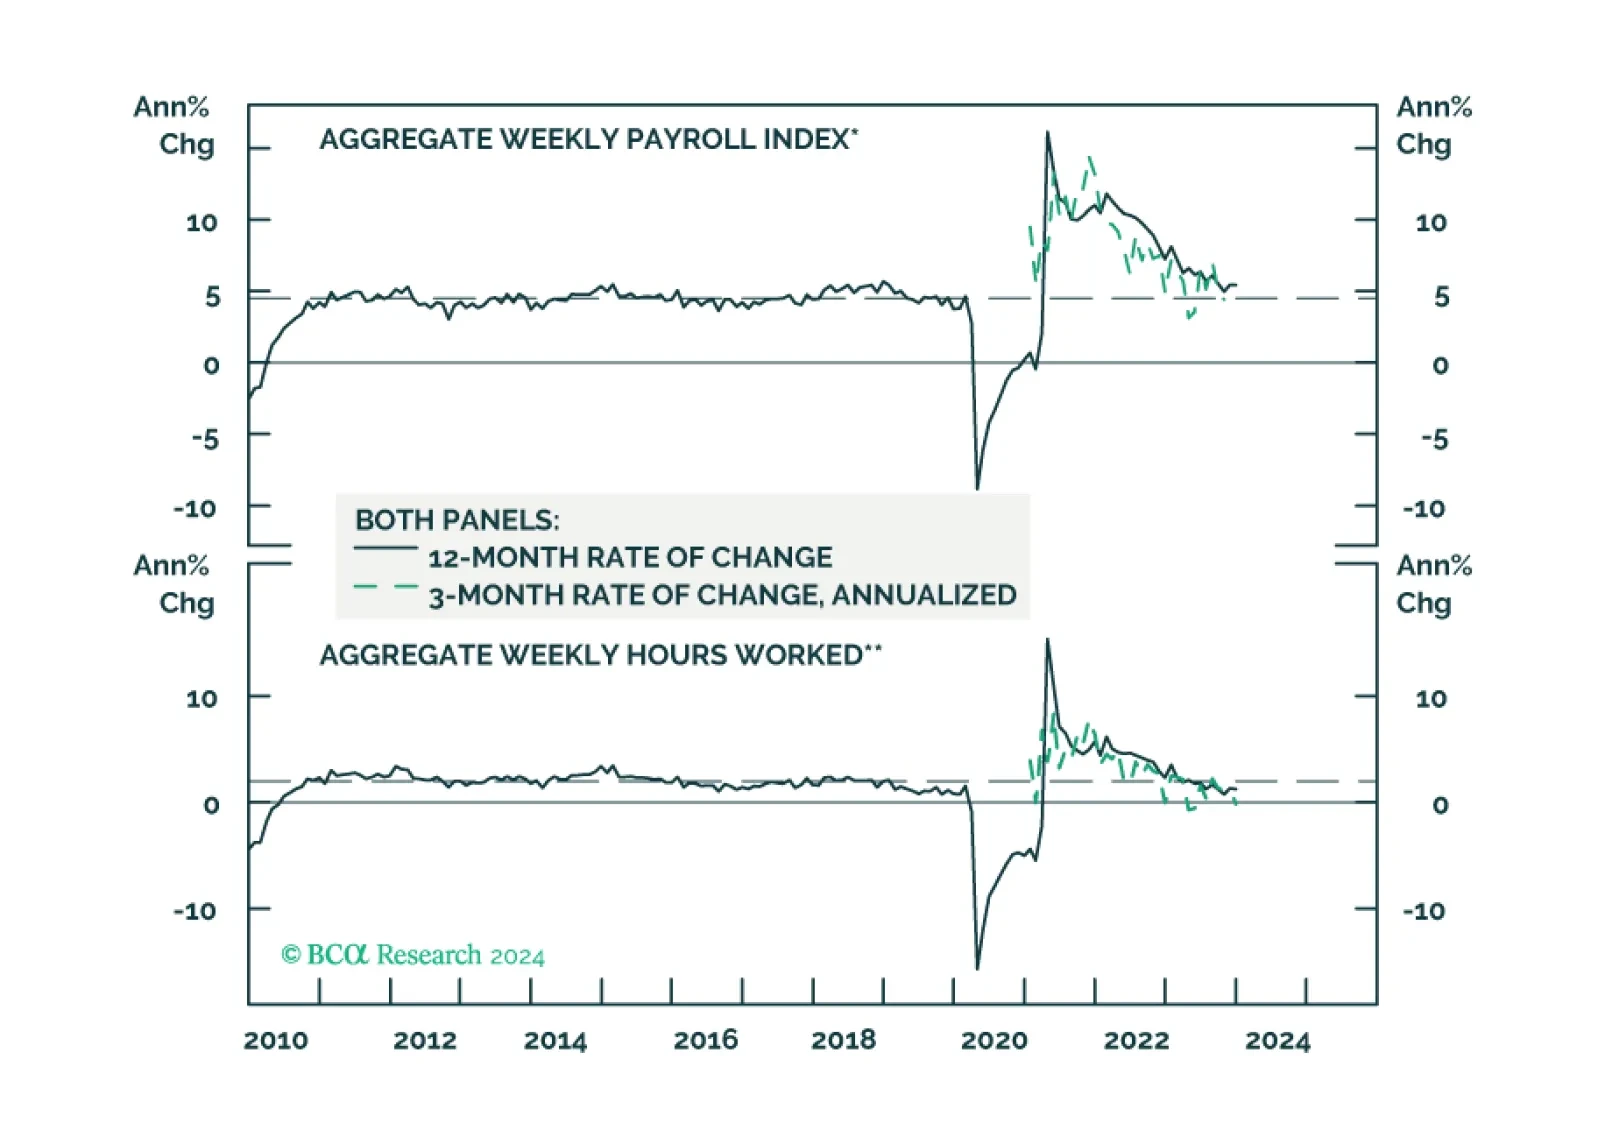
Low inflation argues for the Fed to move relatively quickly toward rate cuts. Continued above-trend GDP growth poses a risk to this view, but leading indicators point to slower growth in the coming quarters.
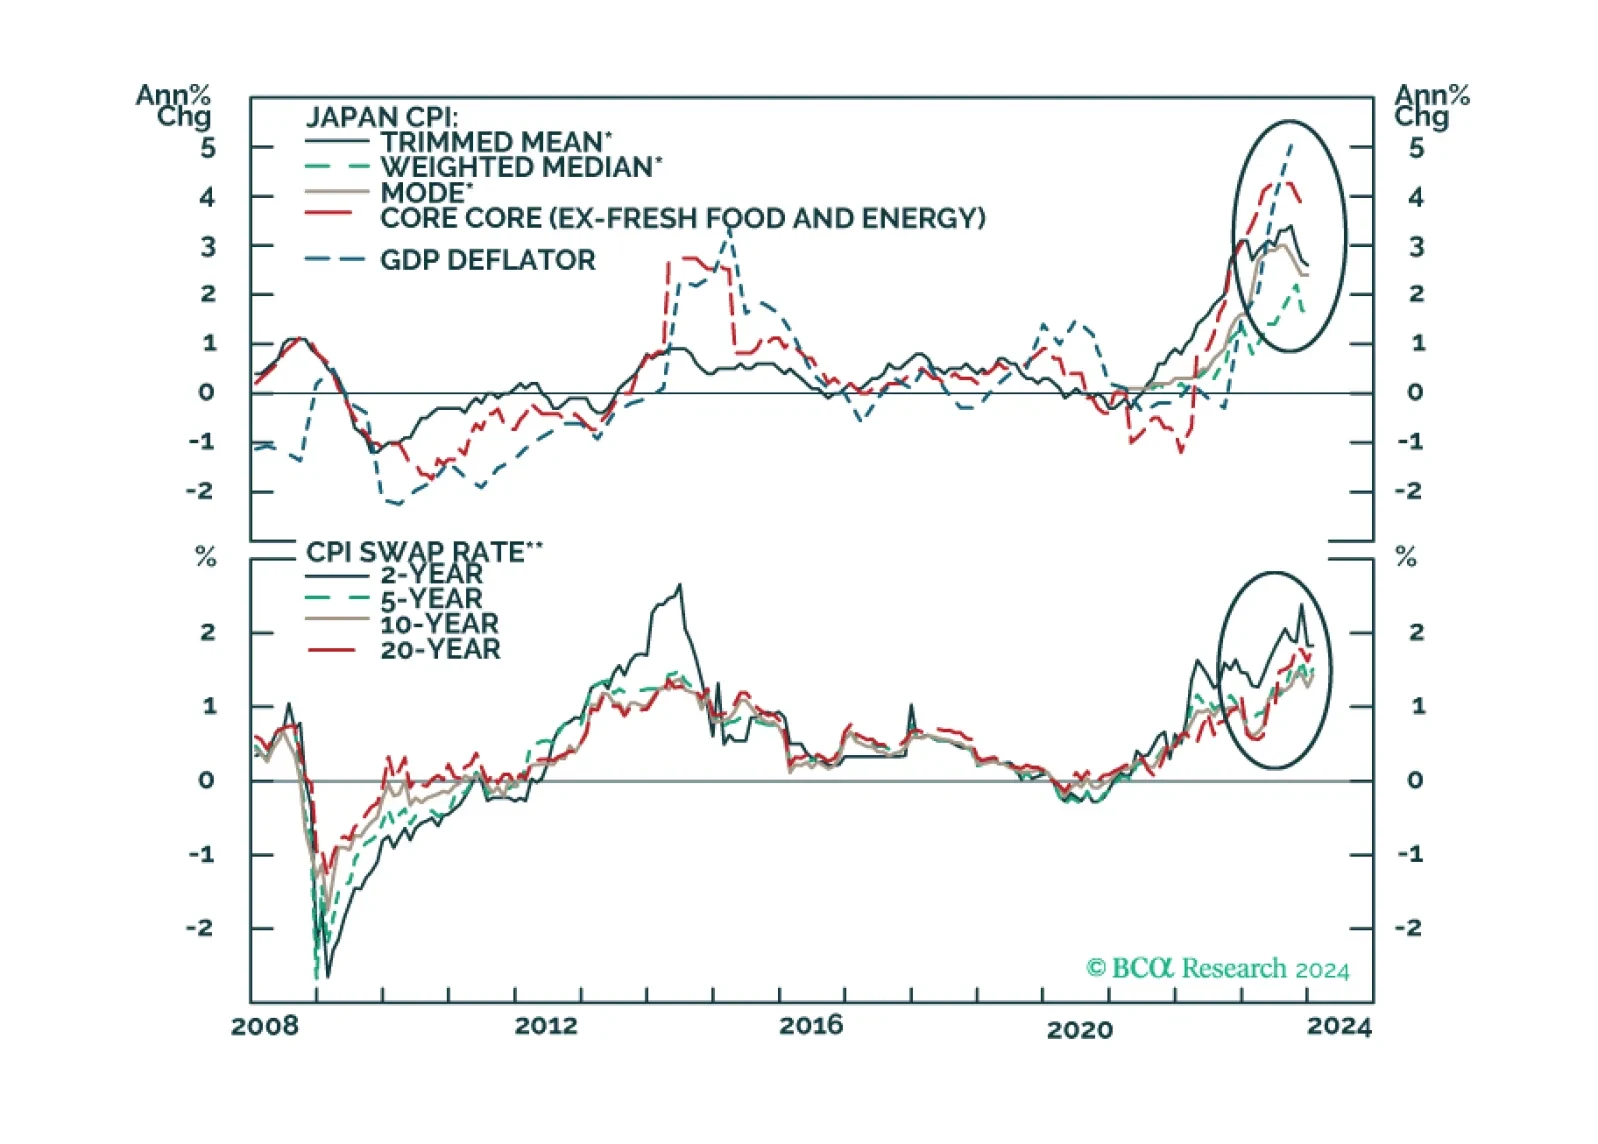
We look at the implications for FX from the slew of central bank meetings this week.
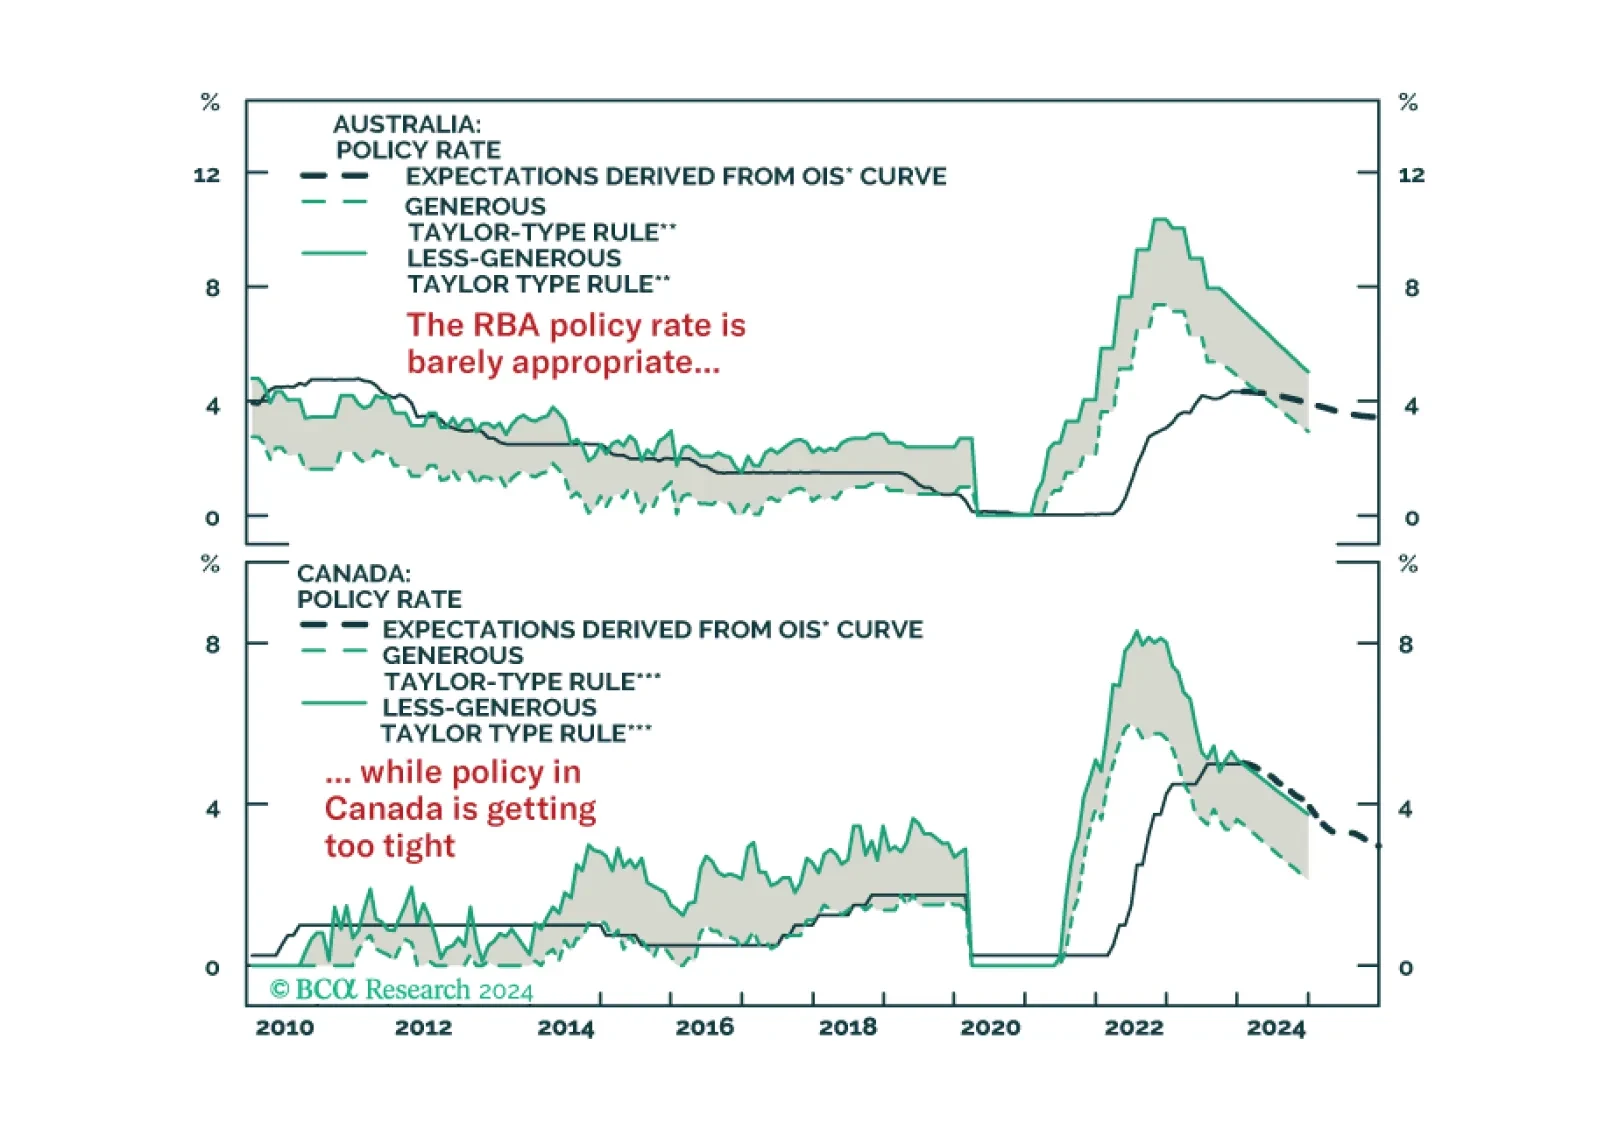
In this Strategy Insight, we assess the monetary policy path for Australia and Canada in 2024 and we discuss how to profit from a growing divergence between the two economies.
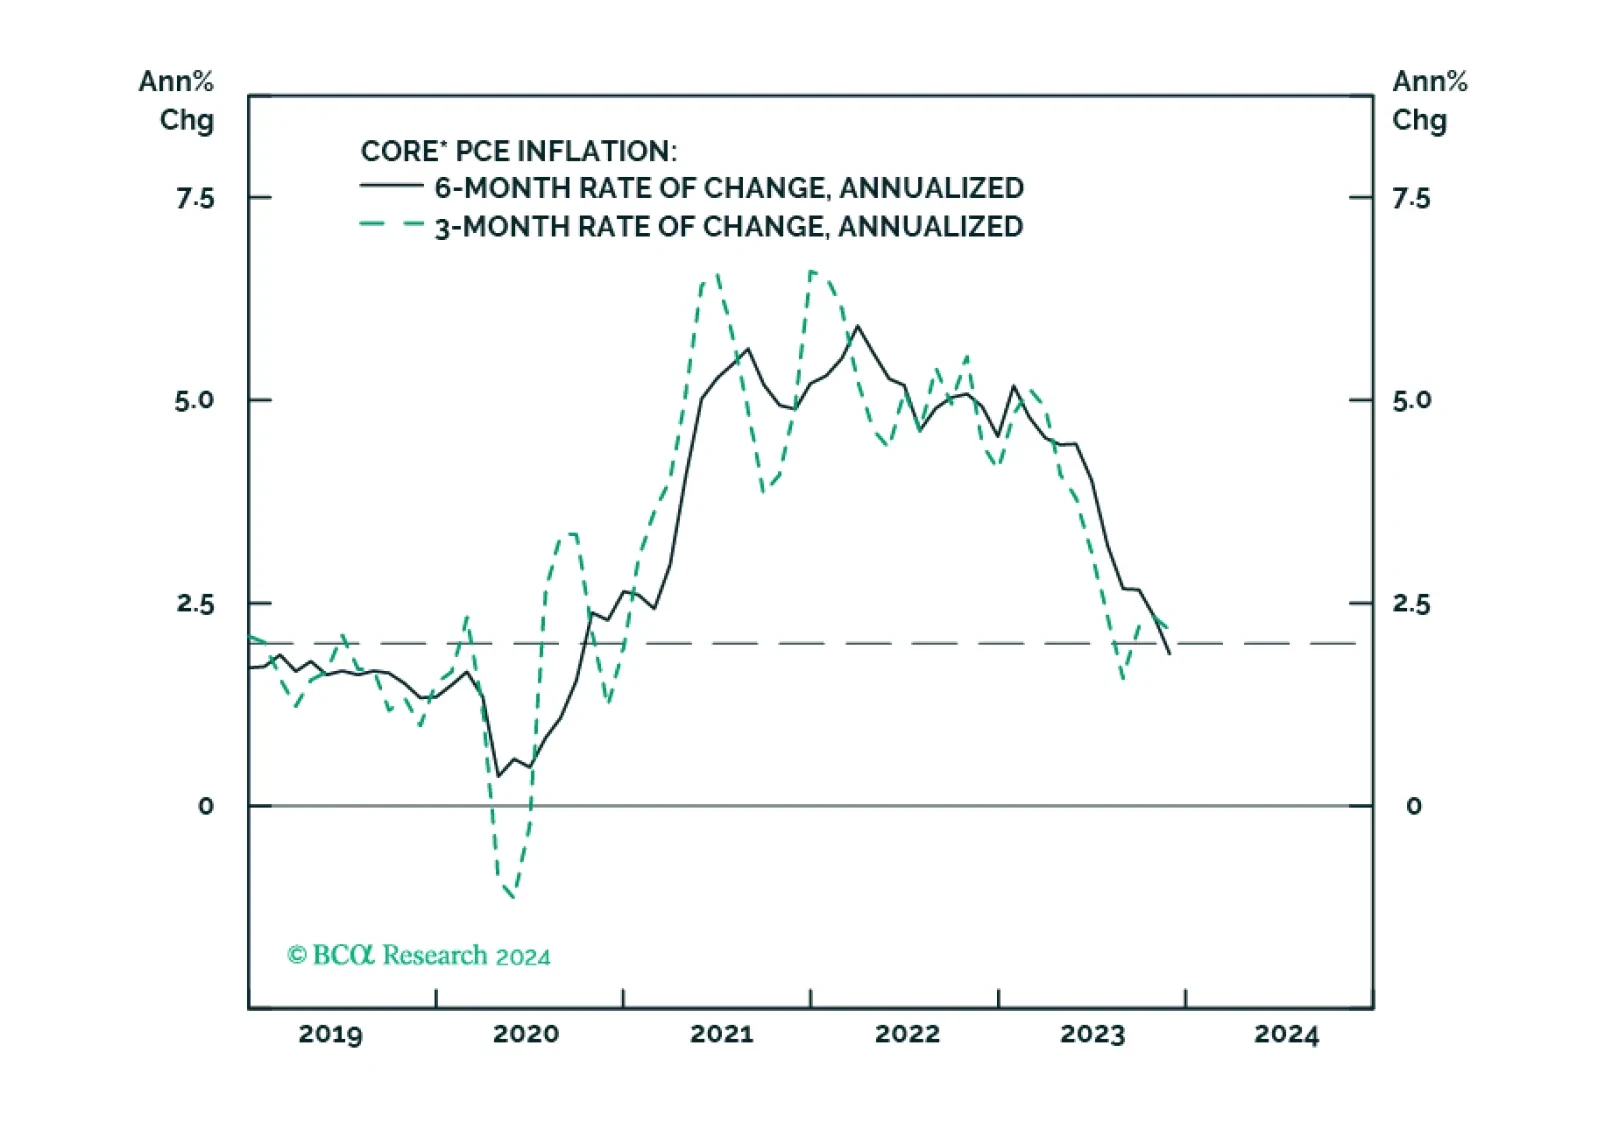
An update to our outlooks for the Fed’s interest rate and balance sheet policies following this week’s remarks from Fed Governor Waller.
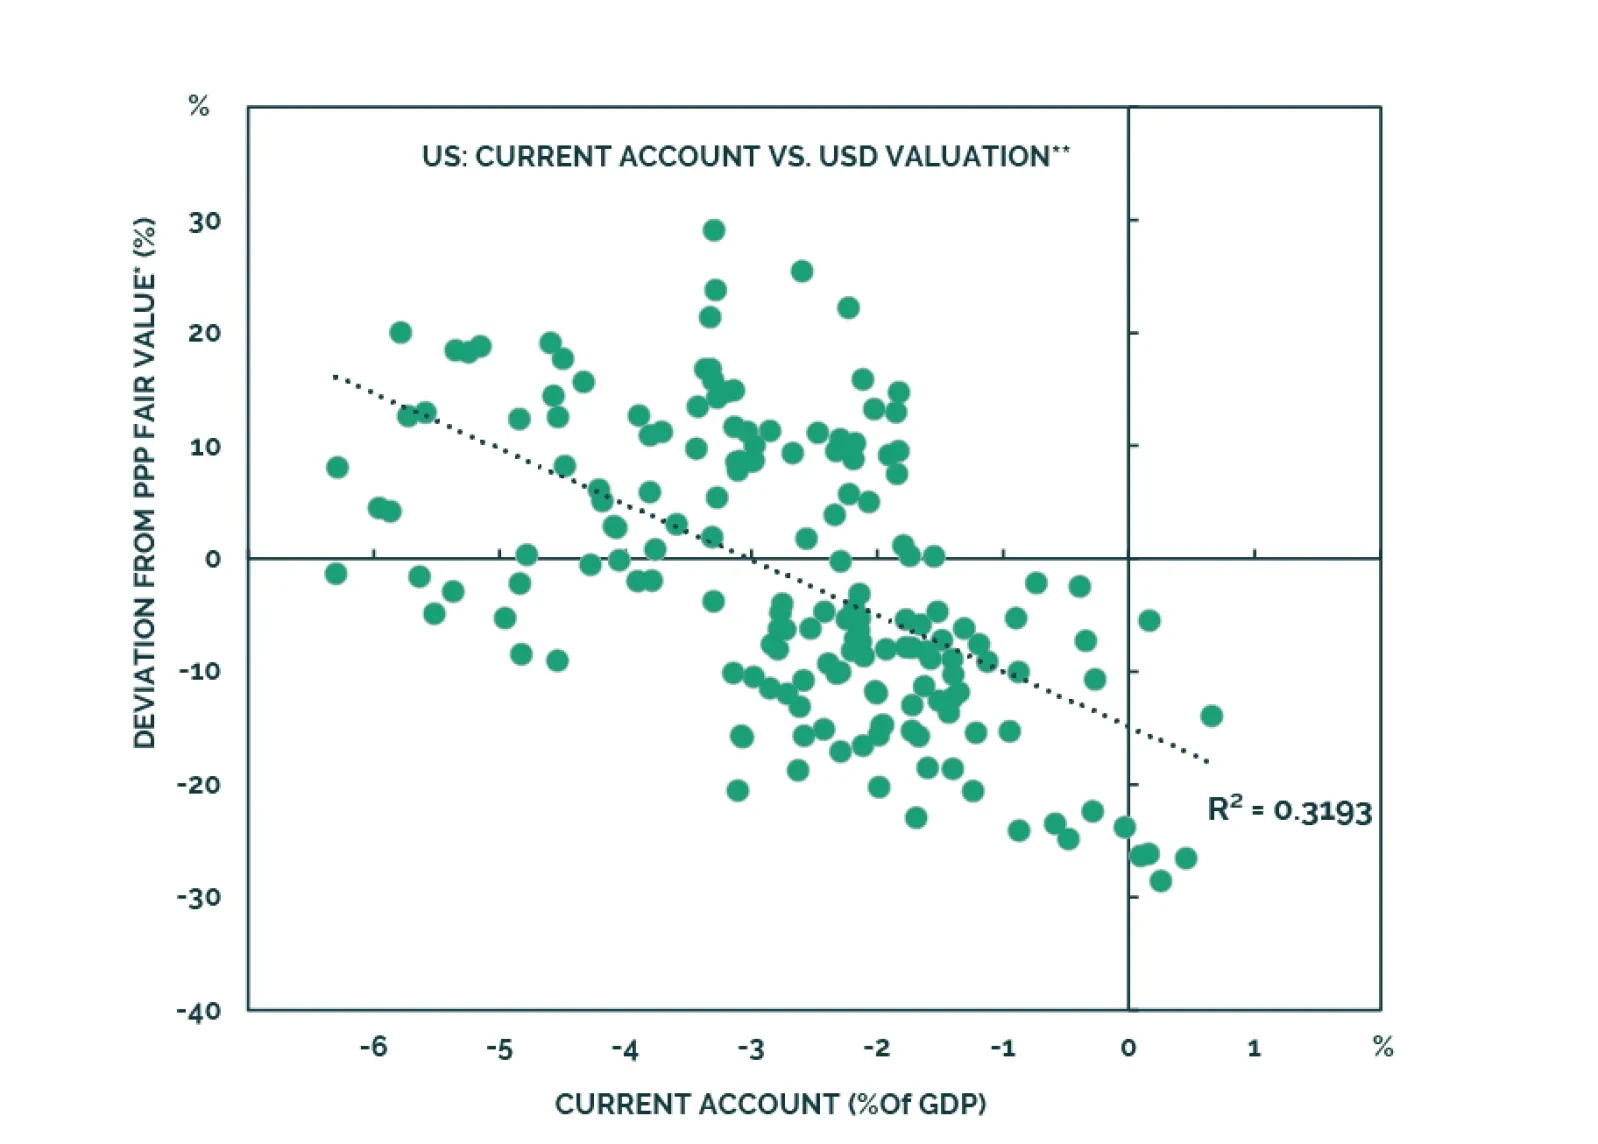
This report examines if investors should worry about a balance of payments crisis in the next 3-to-6 months.

The risk markets will be surprised by another 1mm b/d increase in crude oil supplies this year or next from the US is low, given the depletion of the unfinished-well inventory that drove shale output higher. Demand remains strong, although growth will slow. Higher non-OPEC 2.0 production, slowing demand growth, lower upside risk and the carryforward of elevated 2023 inventories take our 2024-25 Brent forecasts to $95/bbl and $105/bbl, respectively.

In light of the hotter-than-expected US CPI report, we look at what interest rate currency investors should focus on. Our conclusion largely keeps our existing trades in place, as published in our outlook, a few weeks ago.

We update our inflation forecast following this morning’s CPI report.

Increasing gray-zone confrontations and another round of tariff and non-tariff barriers to trade are not being reflected in commodity prices. This is keeping inflationary pressures emanating from the real economy subdued. That said, inflation risks are increasing as threats to commodity supplies and supply chains grow. Standard monetary policy focused on aggregate-demand management is ill-suited for addressing these risks, and could exacerbate supply-side tightness. We remain long oil- and metals-producer equities exposure via the XOP and XME ETFs, and to commodities outright via the COMT ETF.