FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.

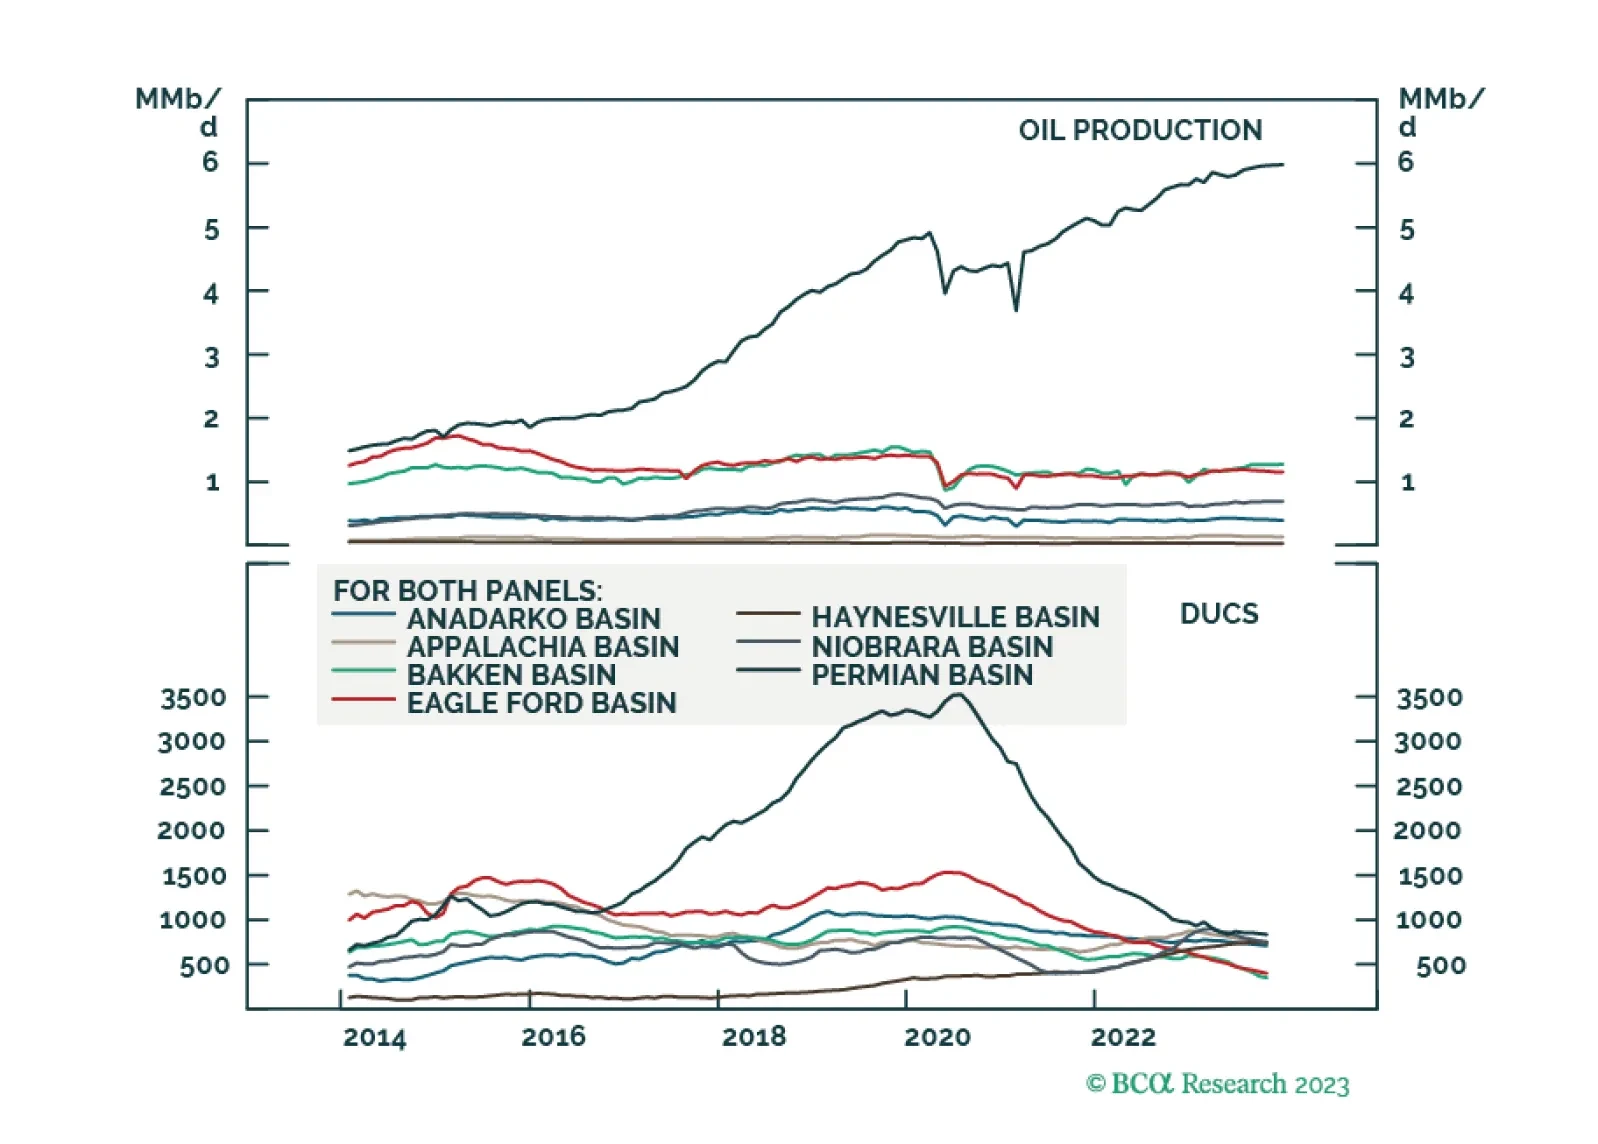
The attacks on Red Sea commercial tankers by Iran’s Yemeni proxies, the Houthi movement, are an inflation risk inasmuch as they lengthen voyage times for any shipping forced to avoid the Bab el-Mandeb Strait. The risk of an expansion of these attacks is, in our view, limited, given Iran’s inability to project naval power in the region.

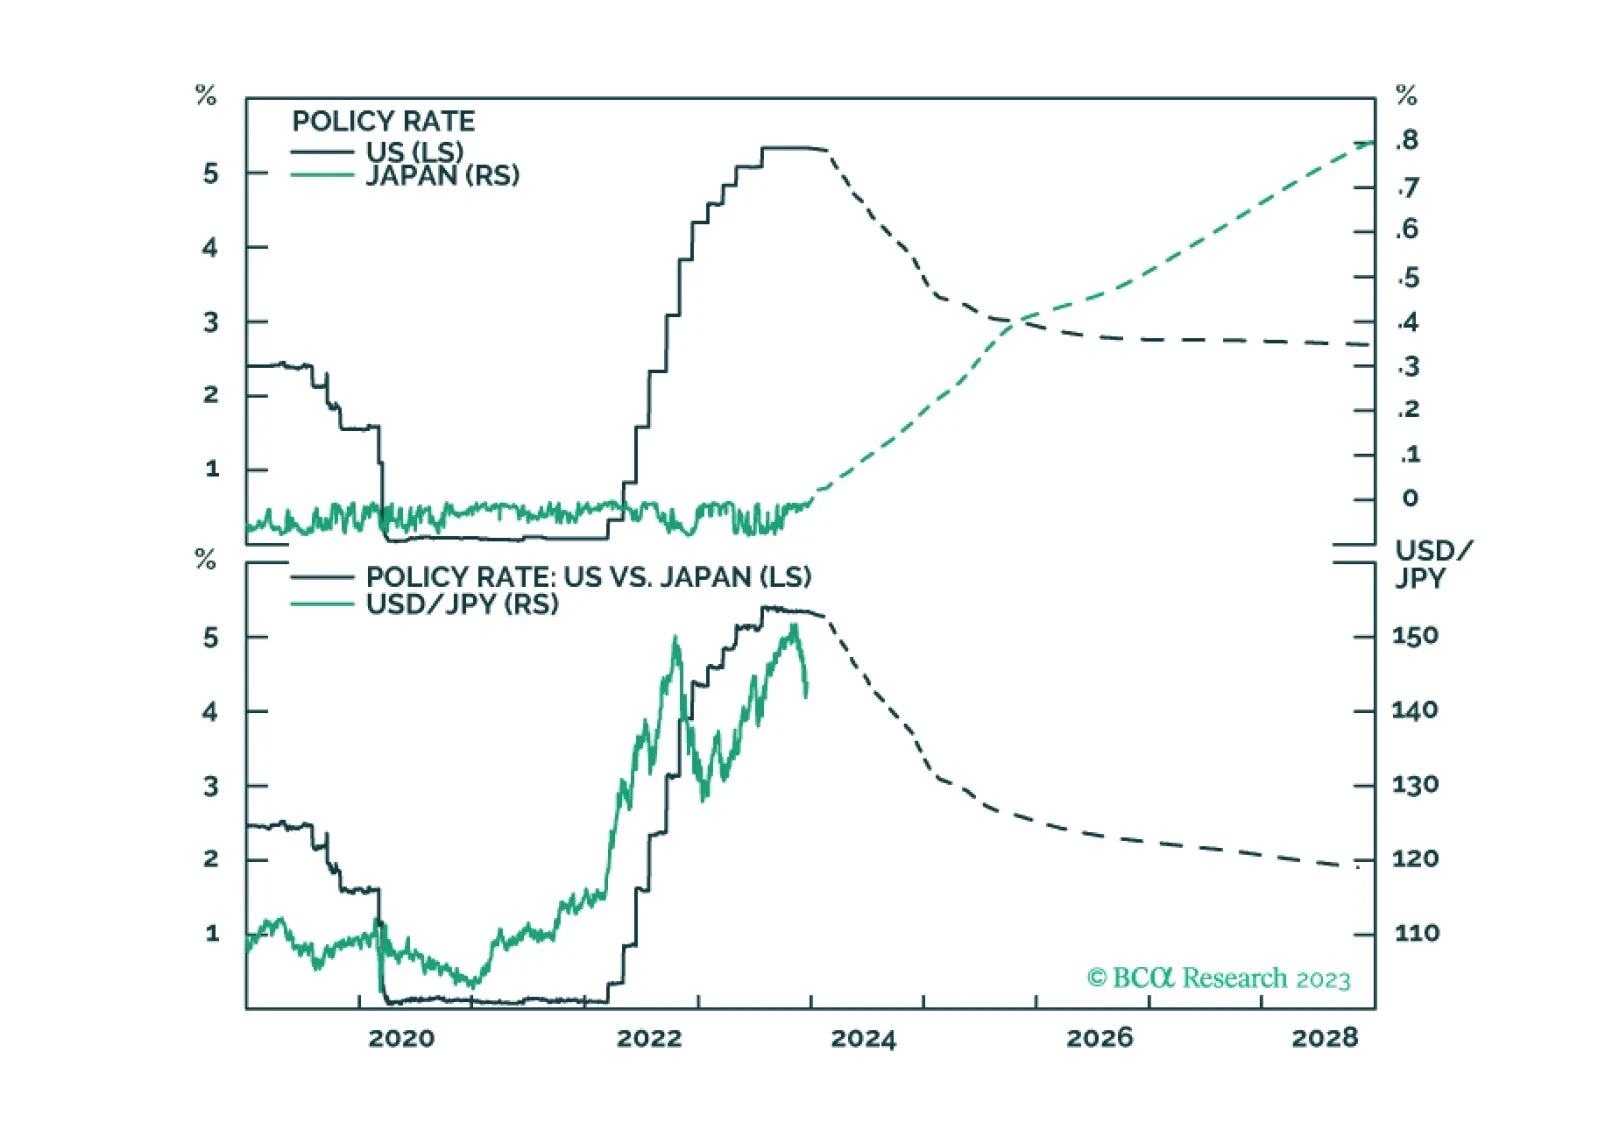
A post-mortem of our trades for the year, and also comments on future yen and sterling moves from the recent BoJ meeting, and the UK inflation report.

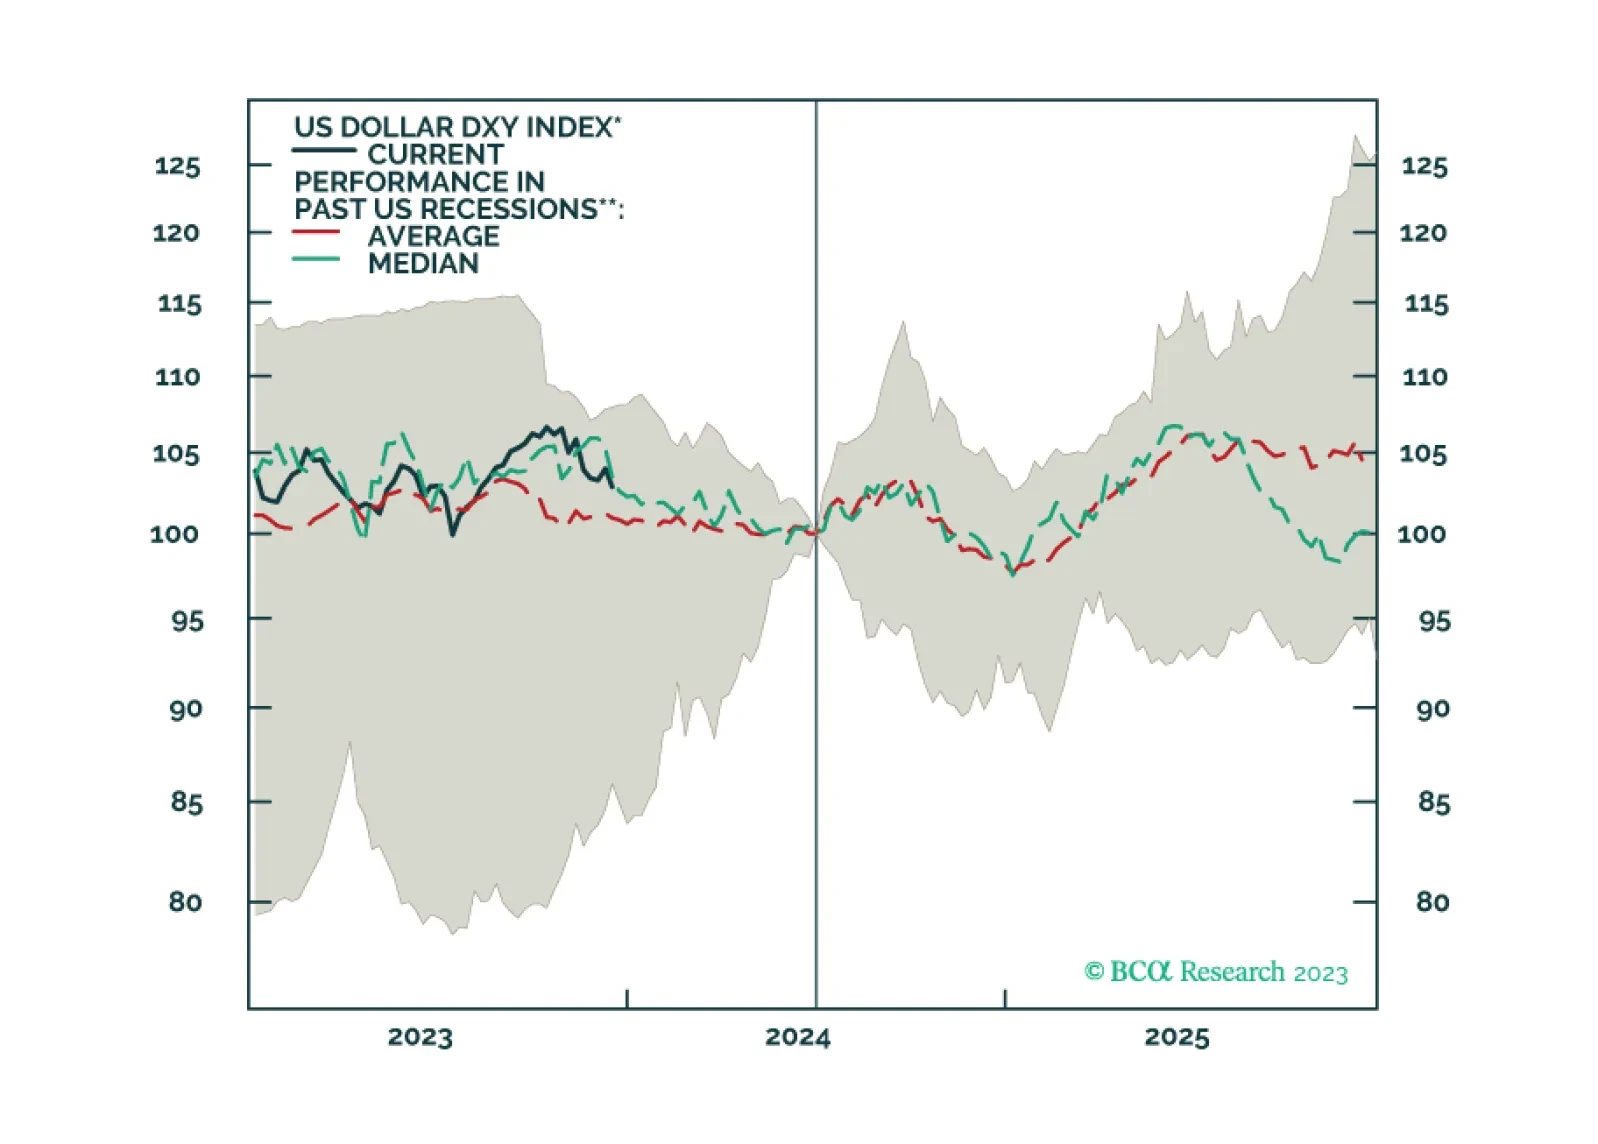

Our US bond team’s thoughts on this afternoon’s FOMC meeting and yesterday’s CPI release.
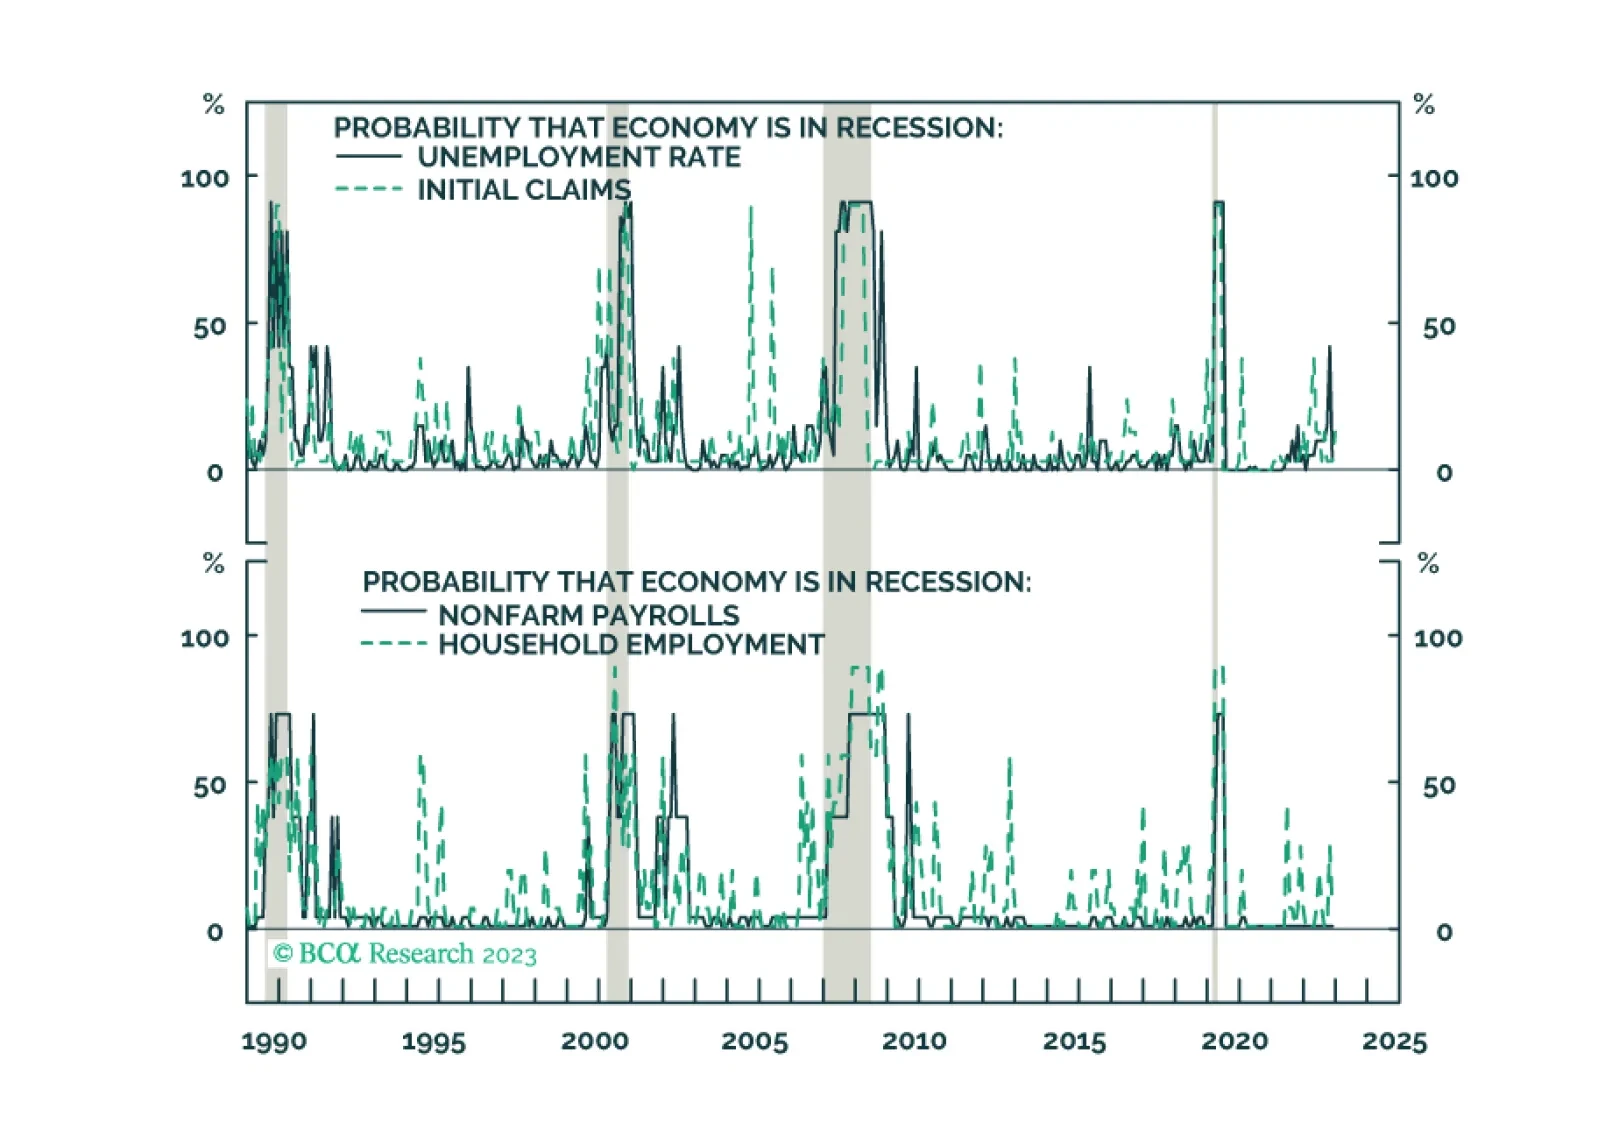
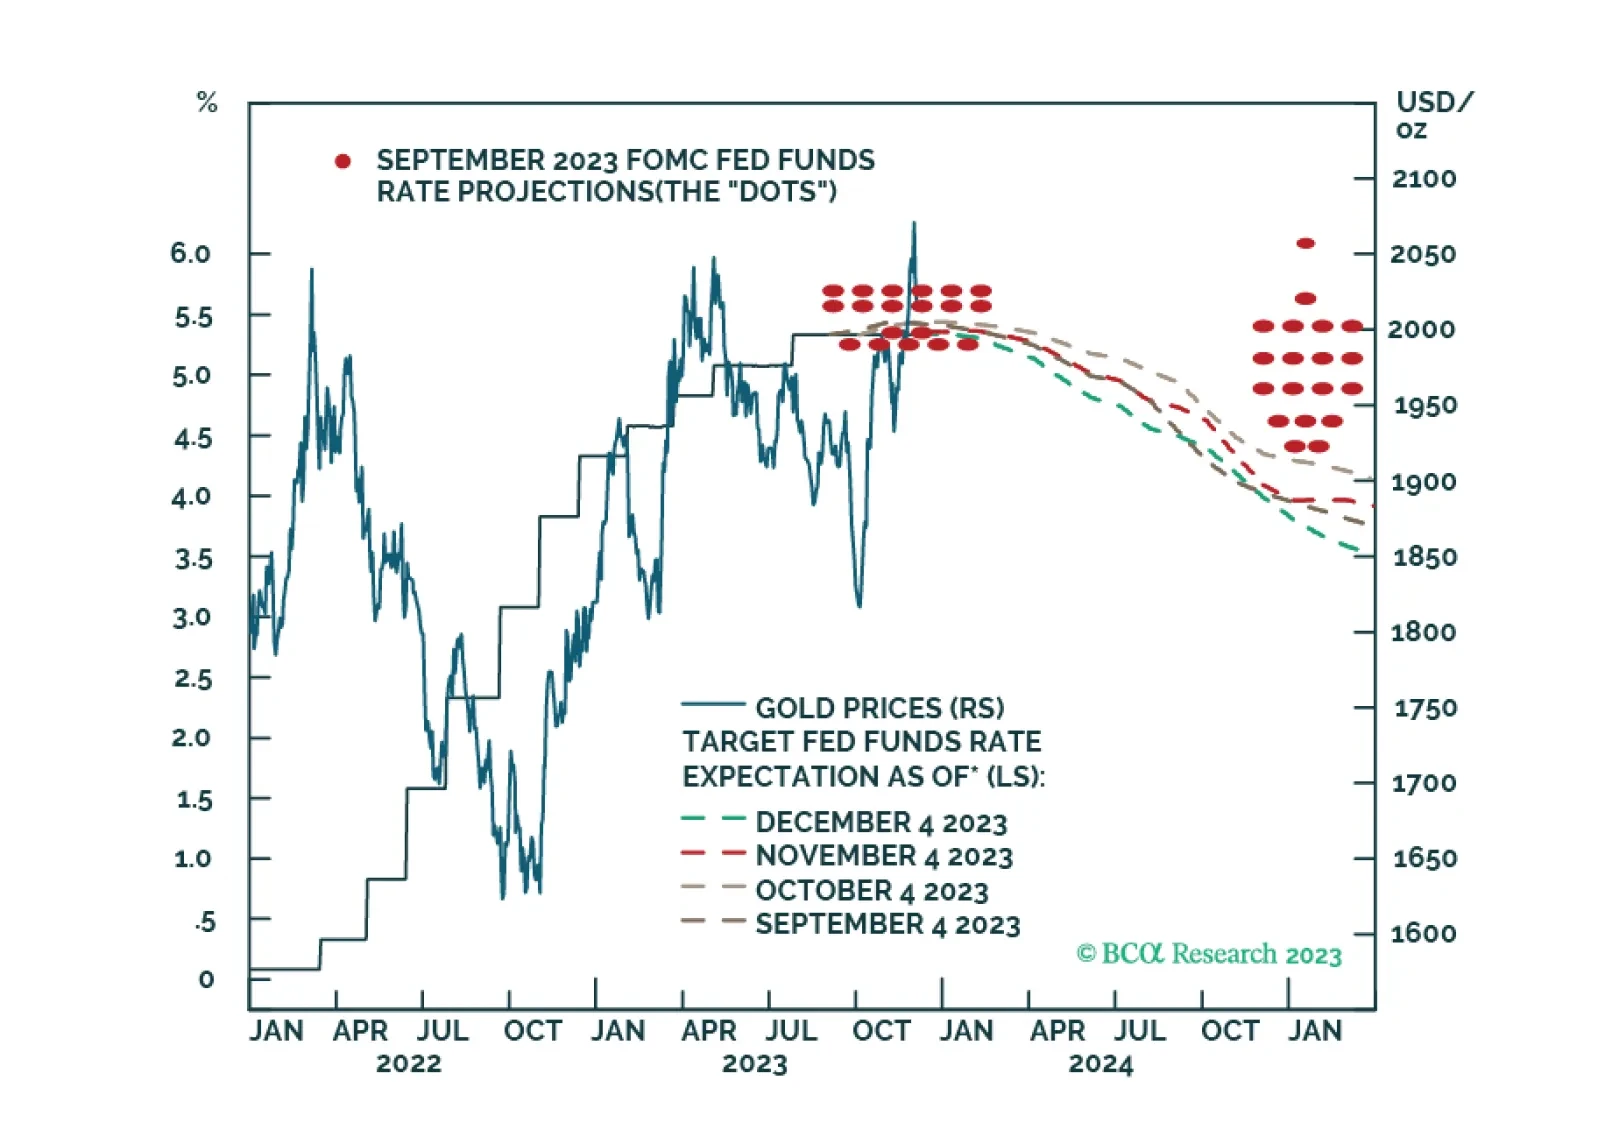
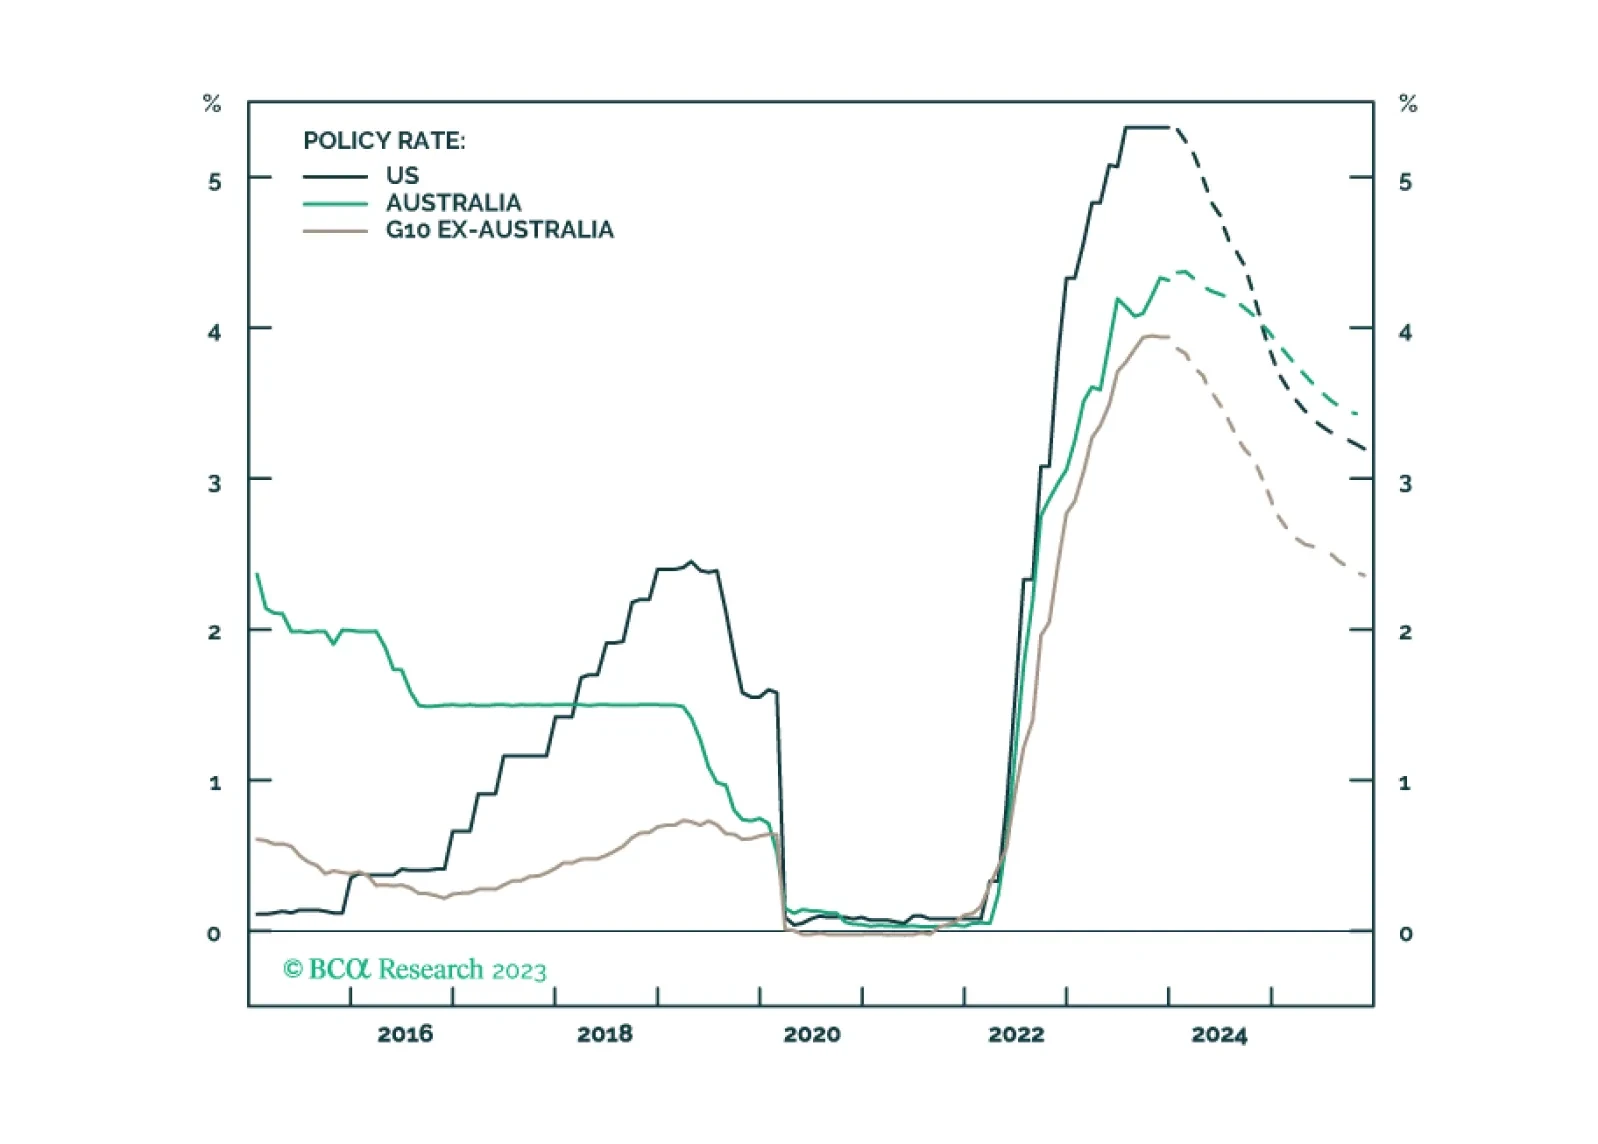
Falling core inflation in the US over the short run will boost real disposable household income, which will keep consumption – ~ 70% of US GDP – strong. Over the medium- to-longer term – 3 to 5 years out – inflation risks rise as fiscal dominance becomes the Fed’s modus operandi, and economic fragmentation becomes entrenched. War and the expansion of war remains an inflation risk. In this environment, gold remains our preferred hedge.