 FICC
| Currencies
Near-term trades and longer-term views on every major developed and emerging market currency.
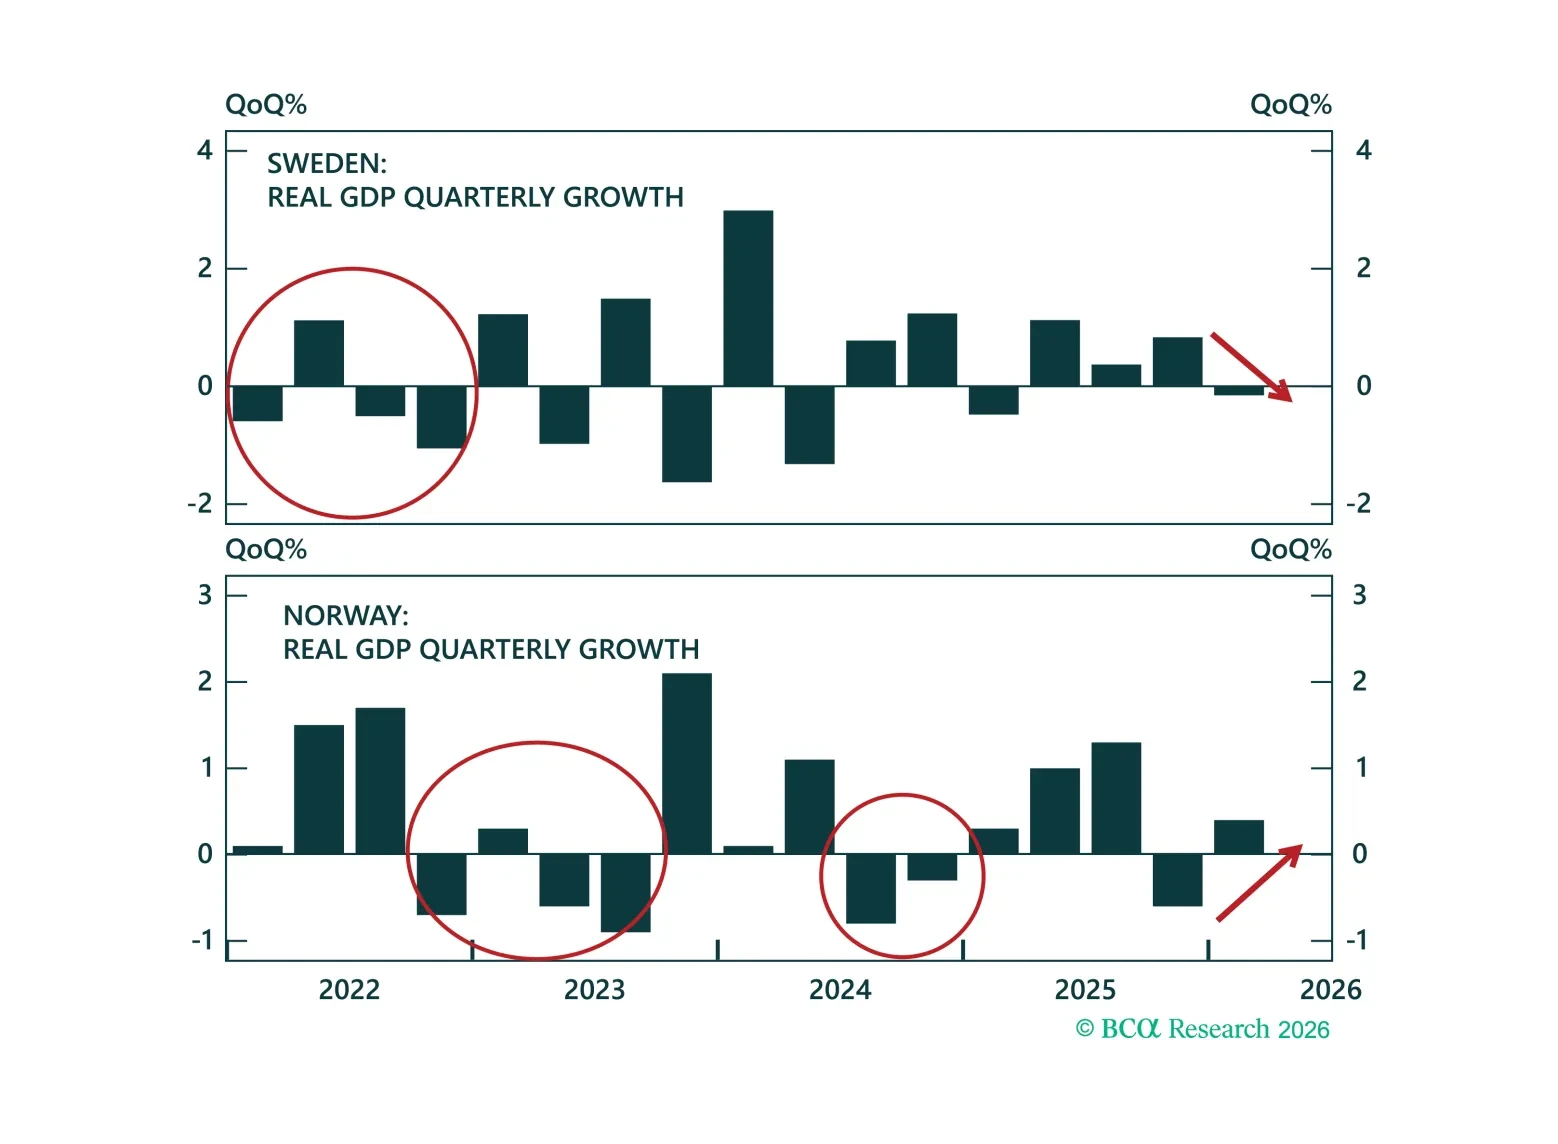
The war in Iran and the energy shock are driving a reversal of Nordic fortunes: Sweden’s recovery is faltering just as Norway receives a welcome energy windfall. Favor Norwegian over Swedish equities and buy NOK/SEK. In rates, fade aggressive Riksbank hike expectations and downgrade Norwegian government bonds to neutral.

MoF and the US Treasury stepped in together to defend the yen, but even joint intervention cannot reset the fundamentals still weighing on the currency. Washington's pursuit of its own incentives, meanwhile, offers another glimpse of a more activist US Treasury.

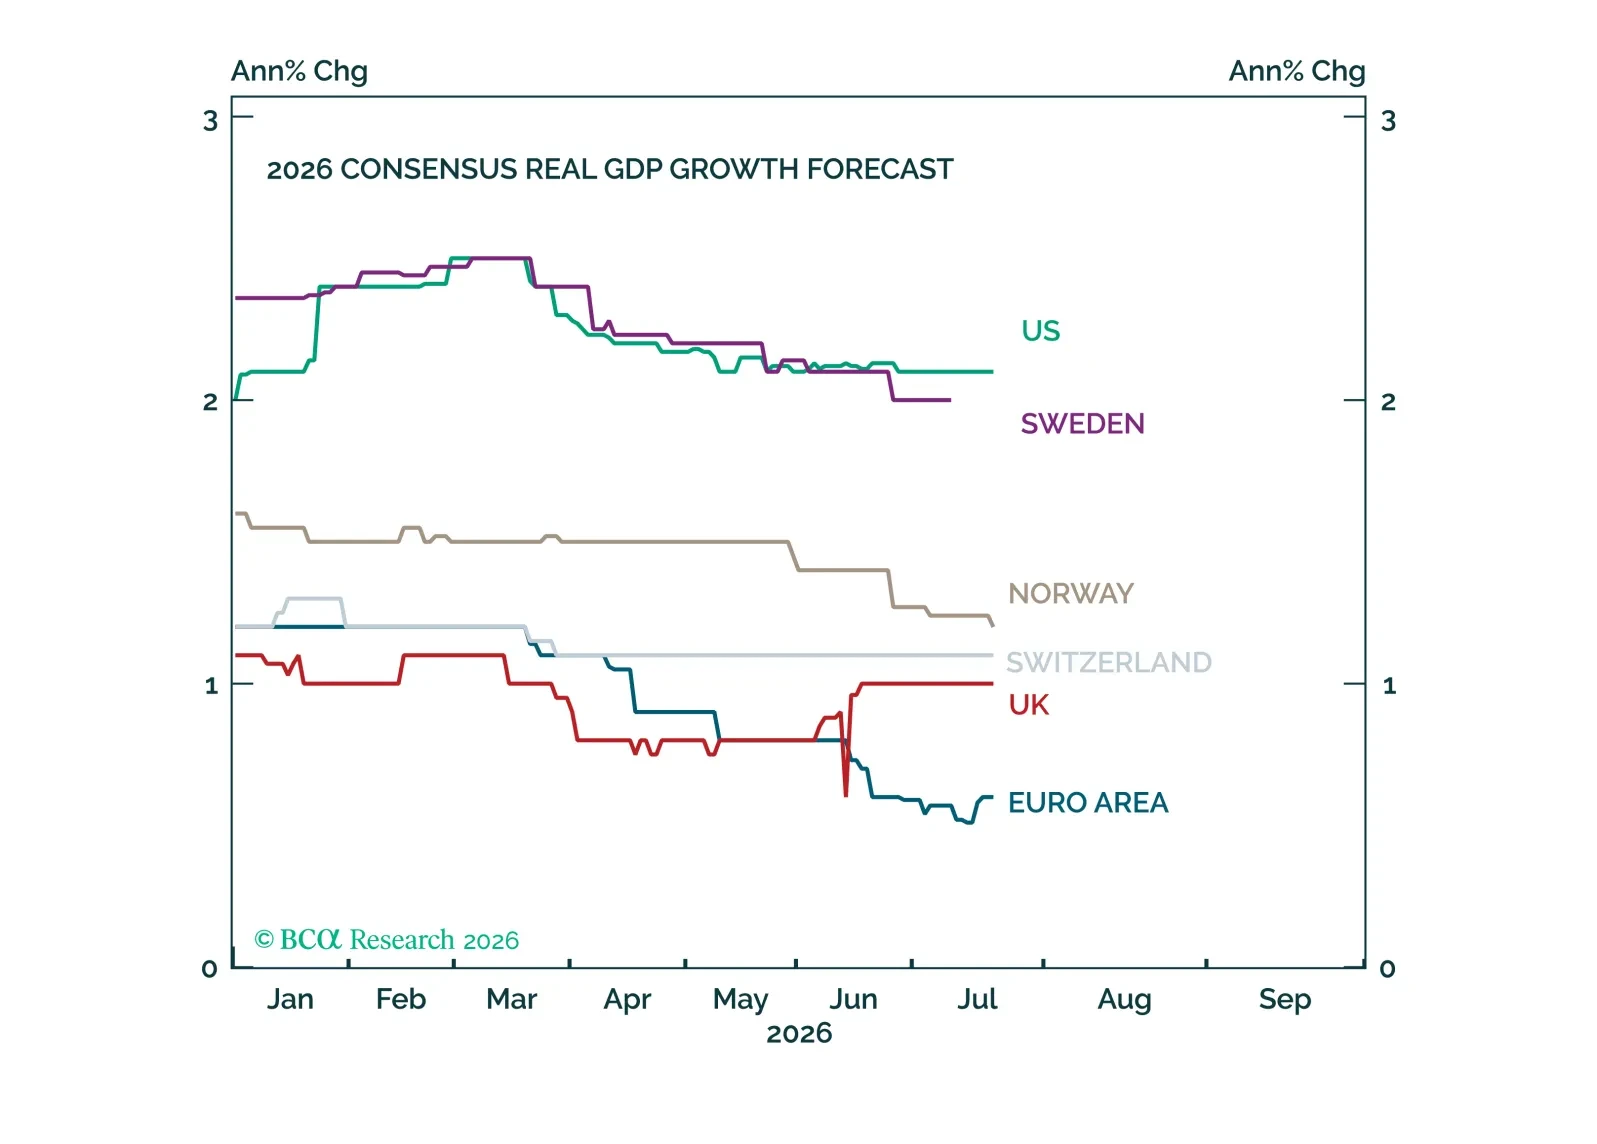
Europe faces a difficult macro backdrop, but whether it slips into recession remains finely balanced. We present two perspectives before translating them into investment implications.
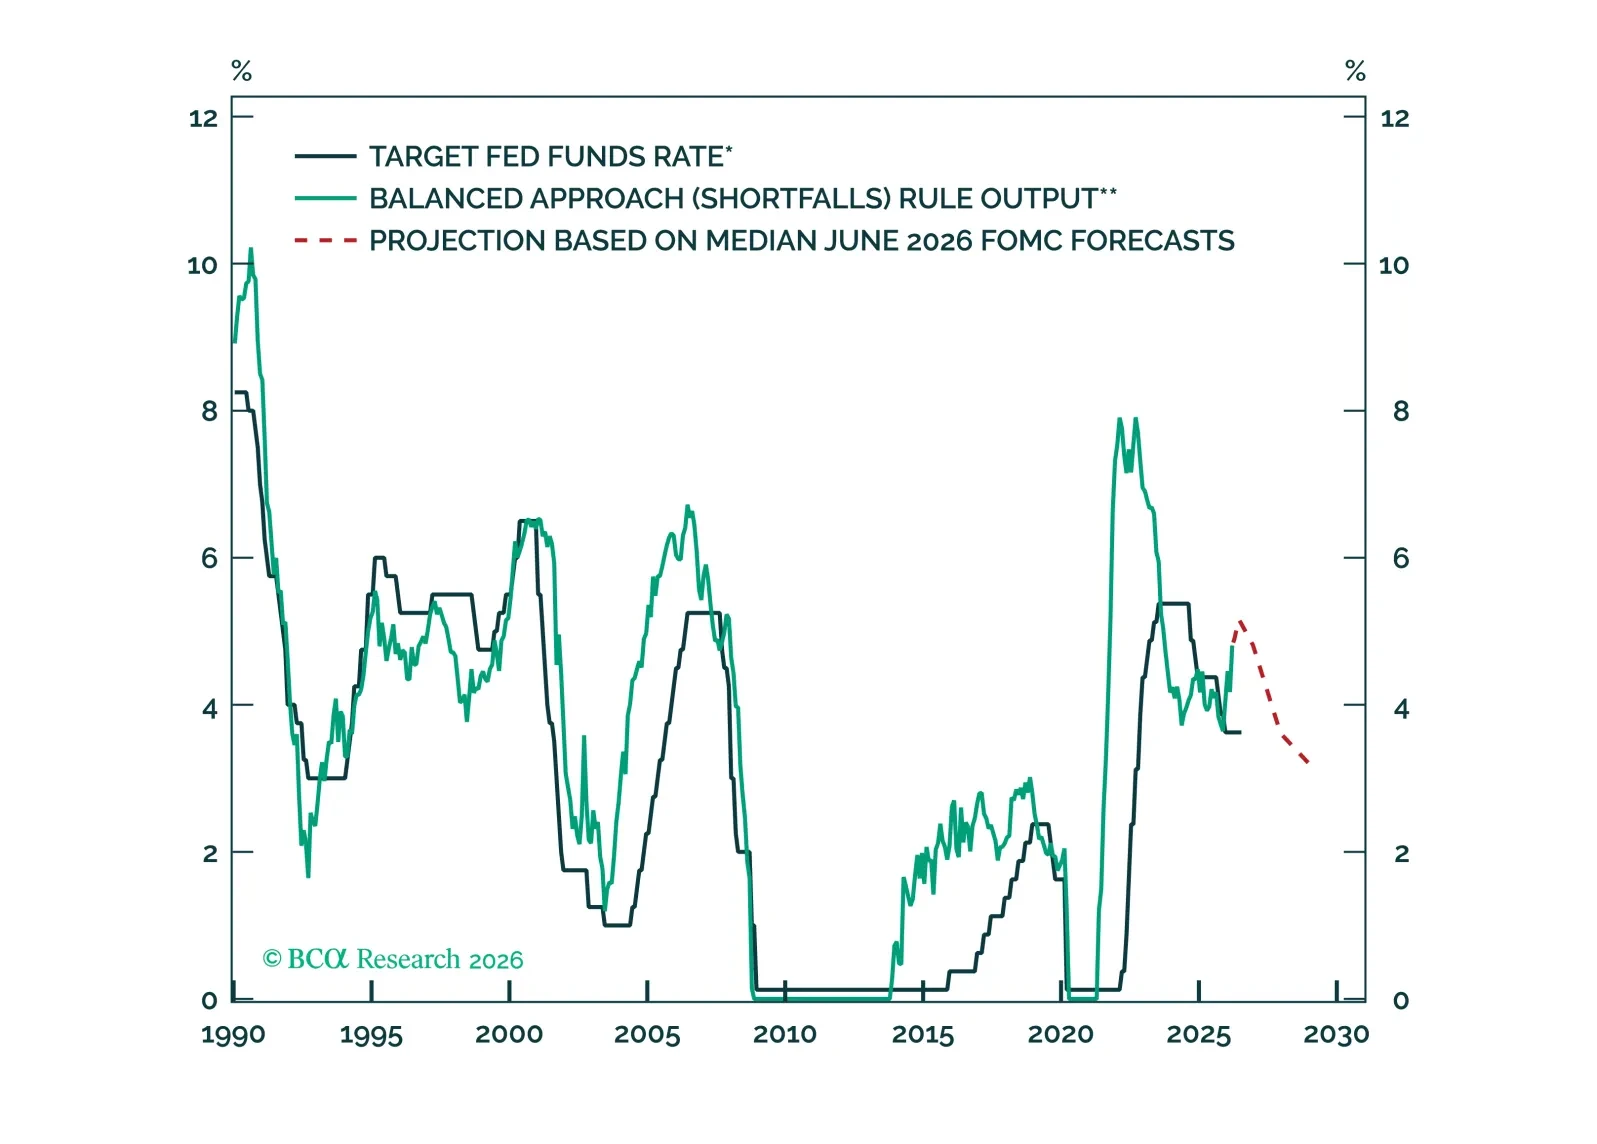
Goldilocks, with fault lines underneath. Our first joint FICC outlook lays out where growth, inflation, and policy are headed this quarter and where the calm could crack.
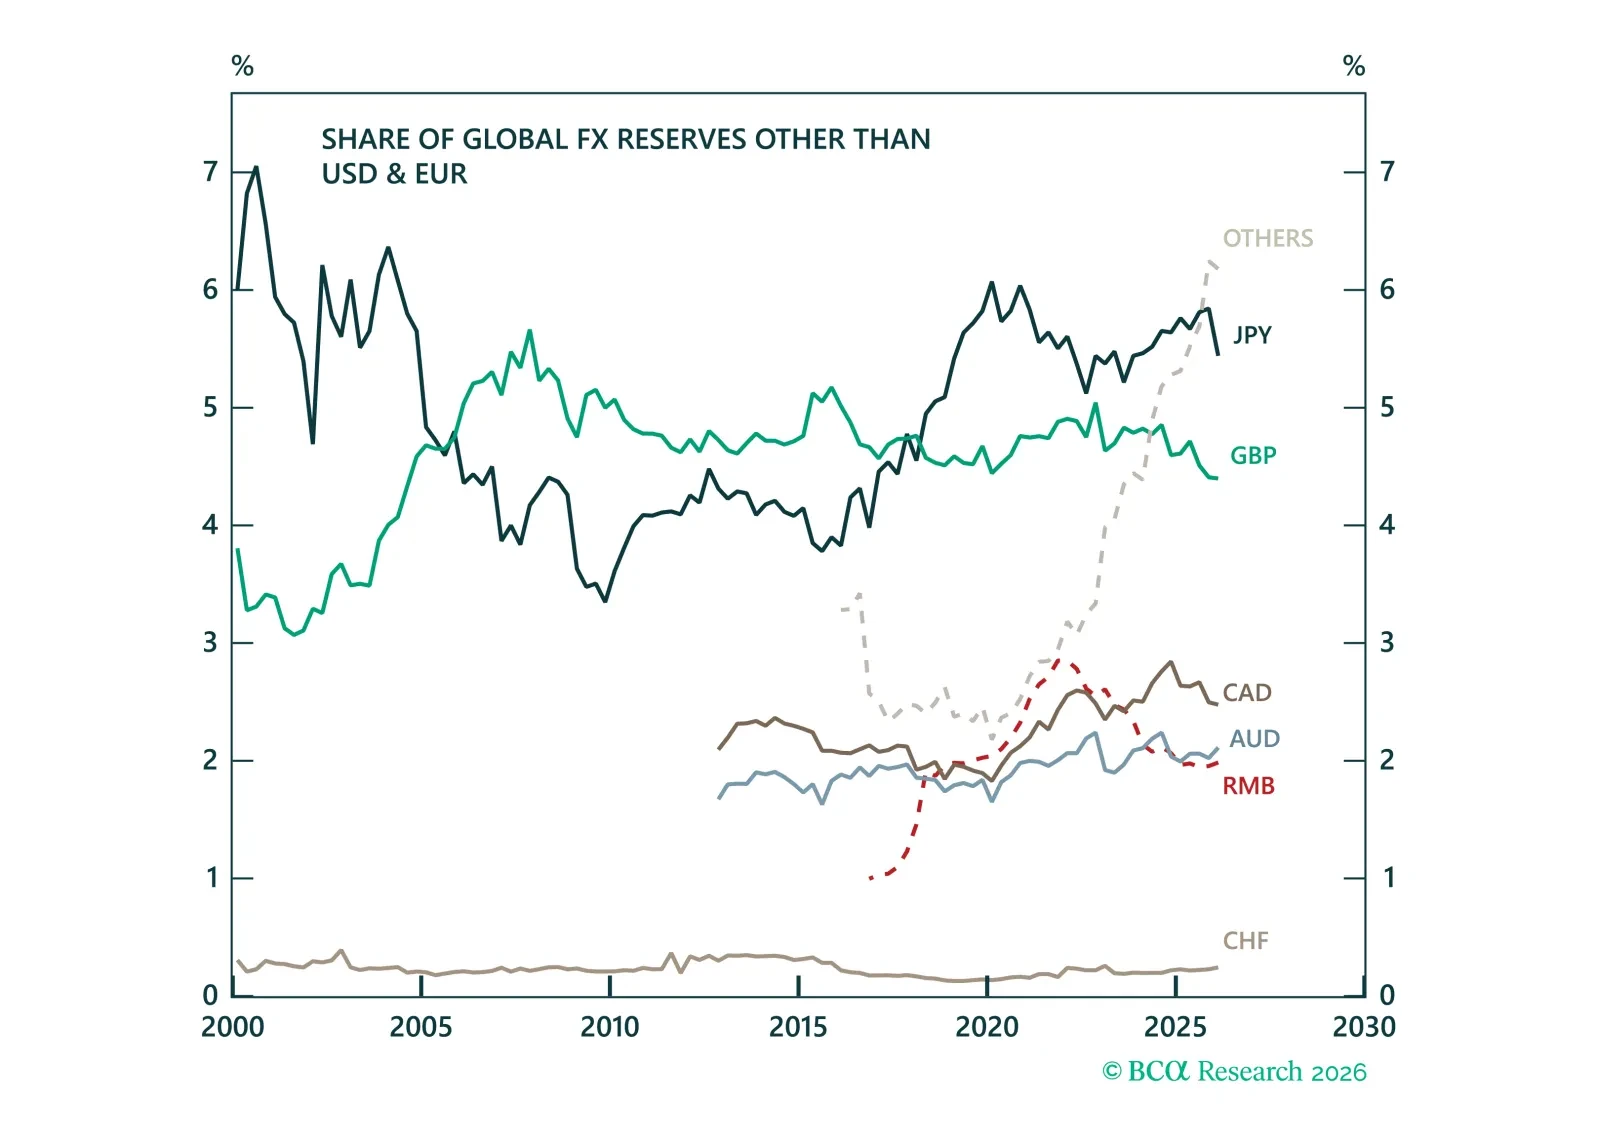
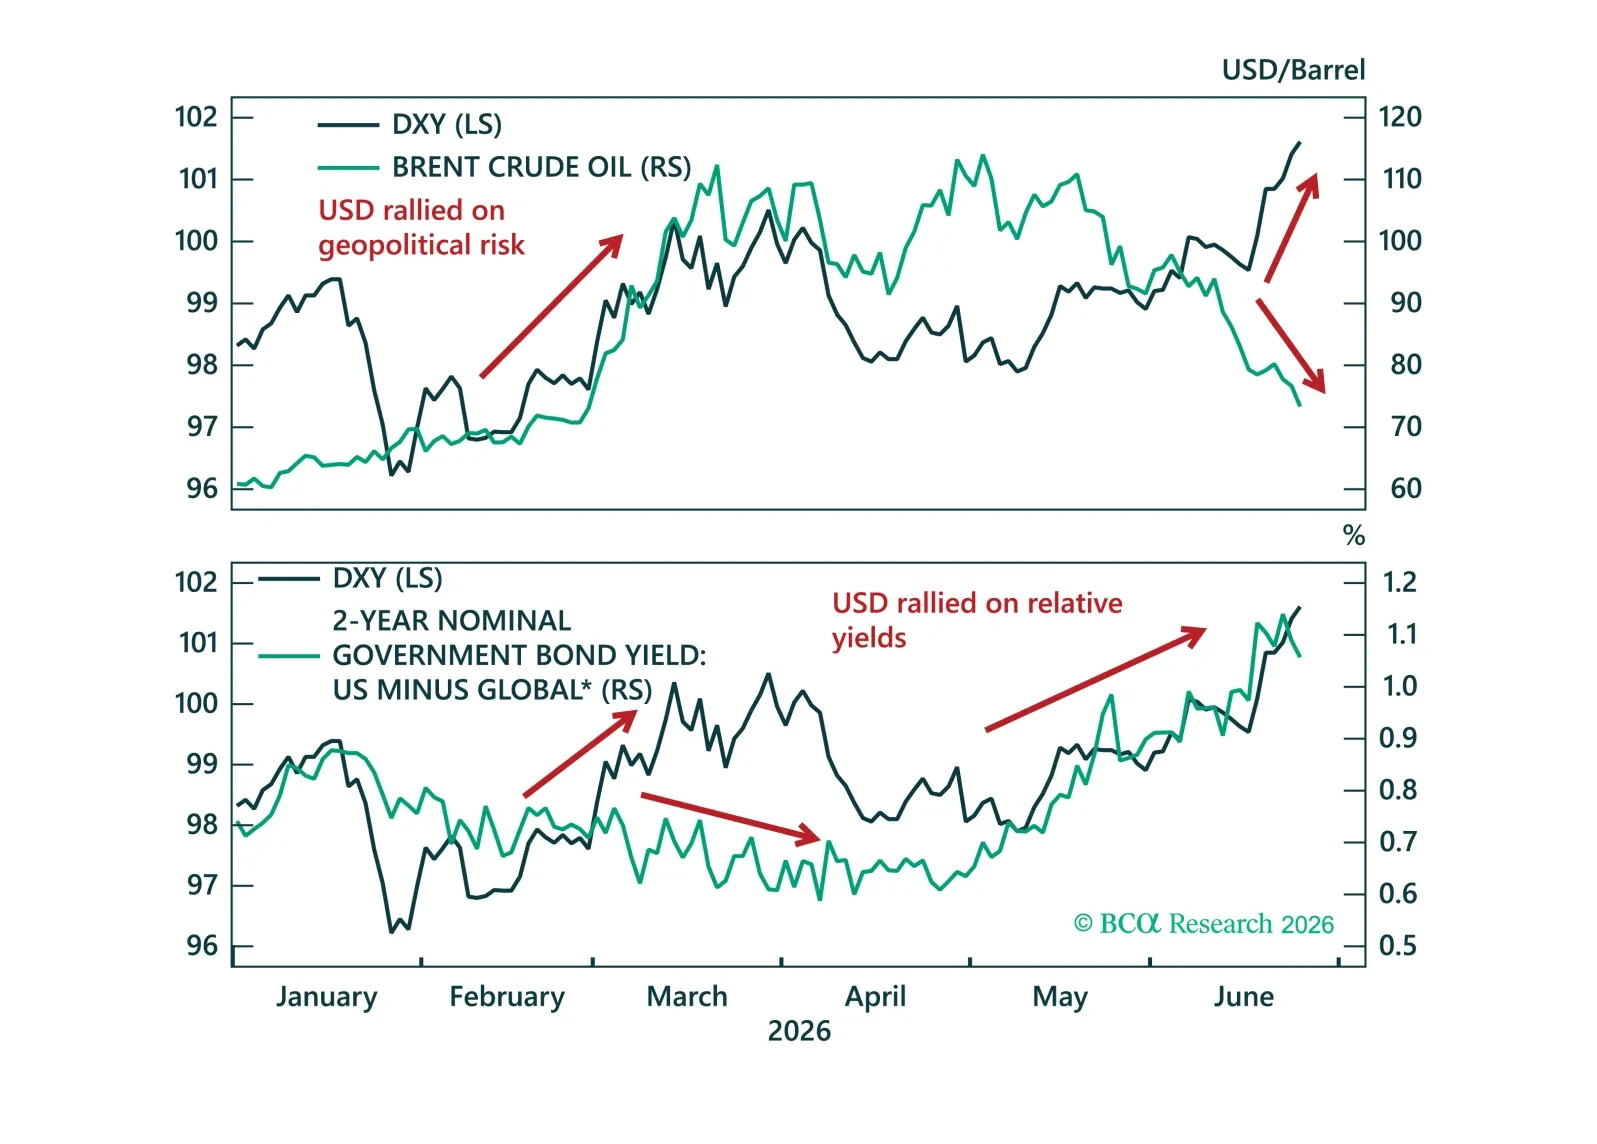
The dollar has had a strong run but its key supports from Fed repricing, positioning, and terms of trade are starting to fade. We close our tactical long USD positions and turn to short USD/JPY, where intervention risk makes yen shorts look increasingly dangerous.


Rising volatility in Korean markets captures a late-cycle surge in which euphoria and drawdown risk are rising together. While KOSPI momentum remains intact, the bigger opportunity may be emerging in the increasingly mispriced KRW, which could rally meaningfully as portfolio flow headwinds fade.
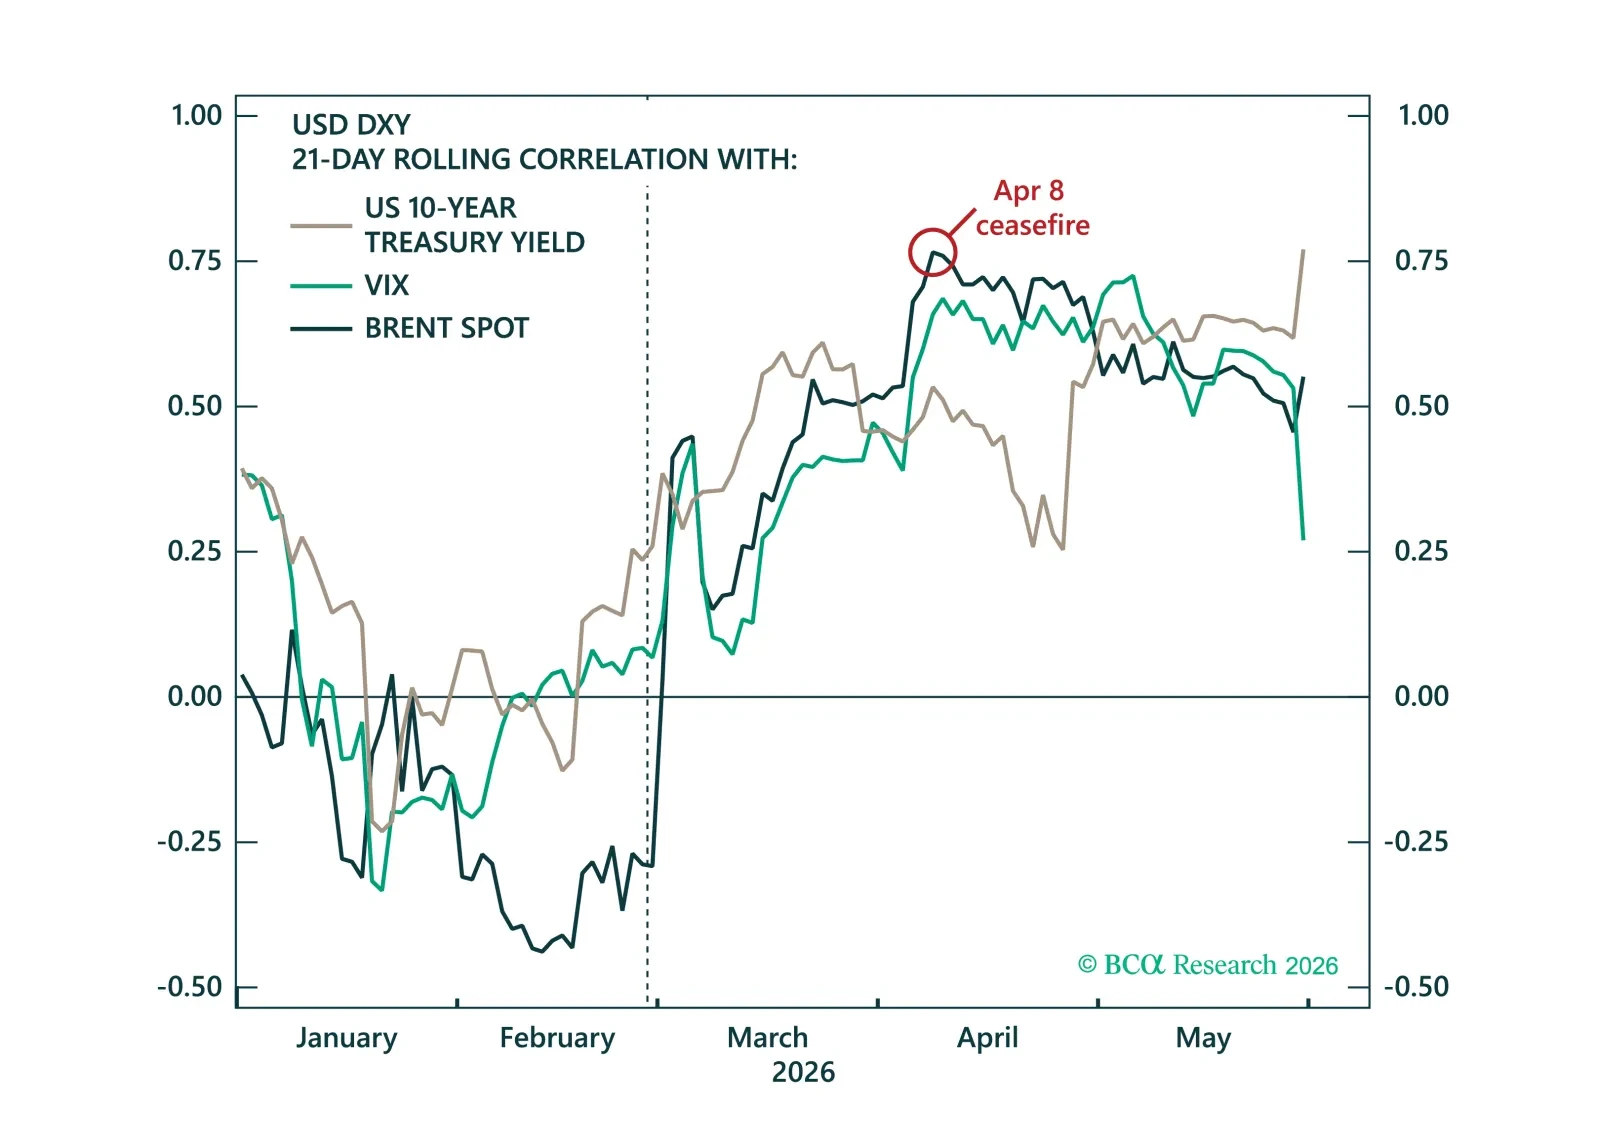
The dollar's muted response to the Iran conflict has led many to question its safe-haven appeal. We argue the opposite – the dollar's defensive properties have returned, while improving growth and rate dynamics should underpin further USD strength in the months ahead.