 FICC
| Bonds
Bond market analysis on where to position across government bonds, credit, and inflation-linked debt.


Forced selling may be approaching a pause, but France’s fiscal and political adjustment has barely begun. Maintain an underweight in OATs and use relief rallies to reduce exposure. Contained contagion is reassuring for Europe; it is not a buy signal for France.
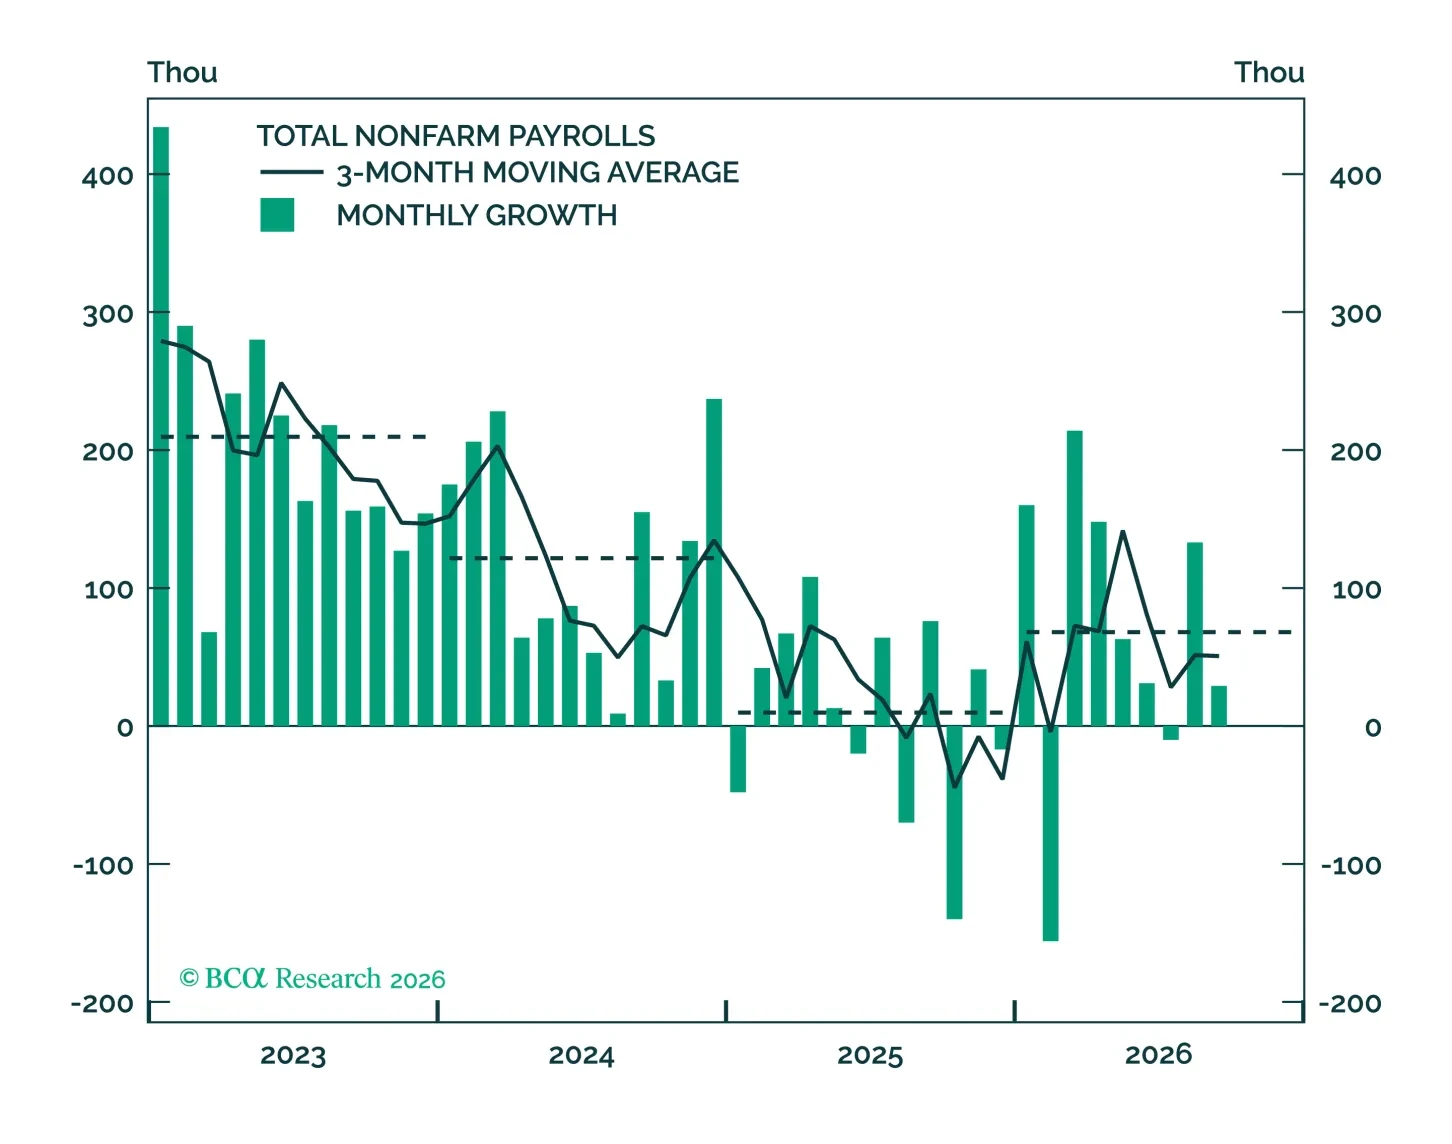
This morning’s jobs report serves to underscore that the labor market is not a source of inflationary pressure and therefore of second-order importance when it comes to the Fed’s near-term decision making.
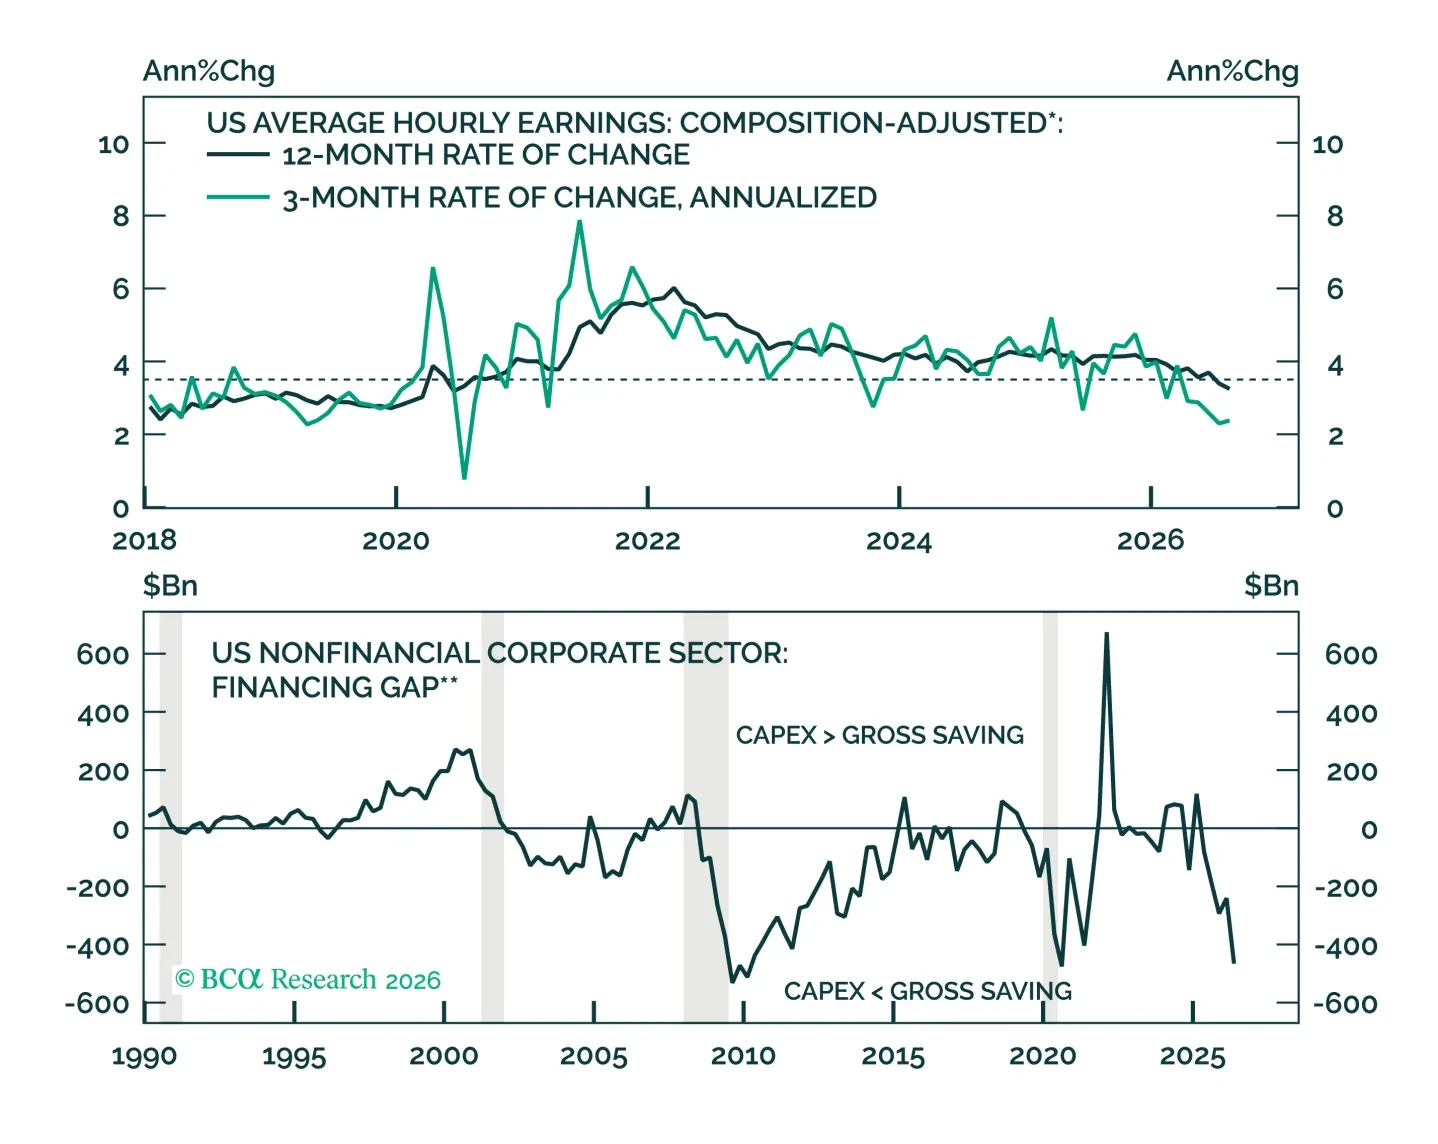
Politics, wars, a global tightening cycle, doubts over AI capex: the wall of worry keeps rising. But the spark that would topple risk assets is missing. Our Q4 FICC outlook explains why to stay long risk, and where the danger lies.

Core US inflation is still running above target. But this morning’s data revisions reveal that the gap is not nearly as large as it appeared yesterday.
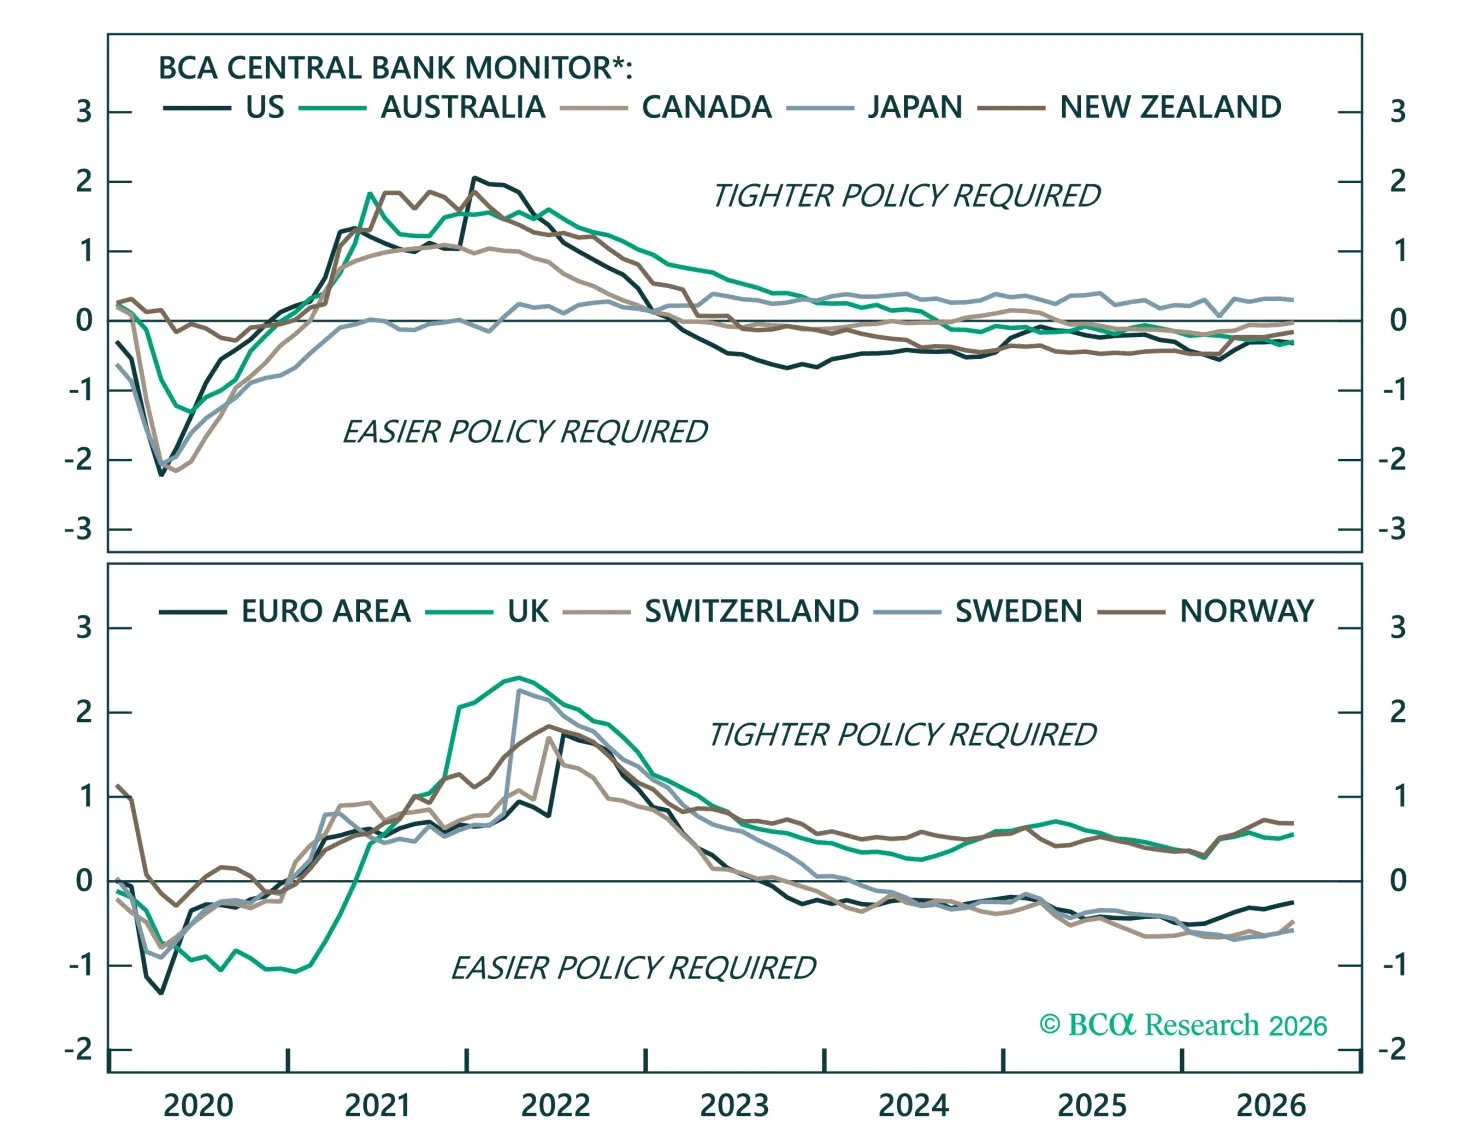
Central banks have begun a mild tightening cycle as elevated energy prices raise concerns about second-round inflation effects. We use BCA’s Central Bank Monitors to test whether hawkish market pricing is justified and identify tactical opportunities across global bond and currency markets.
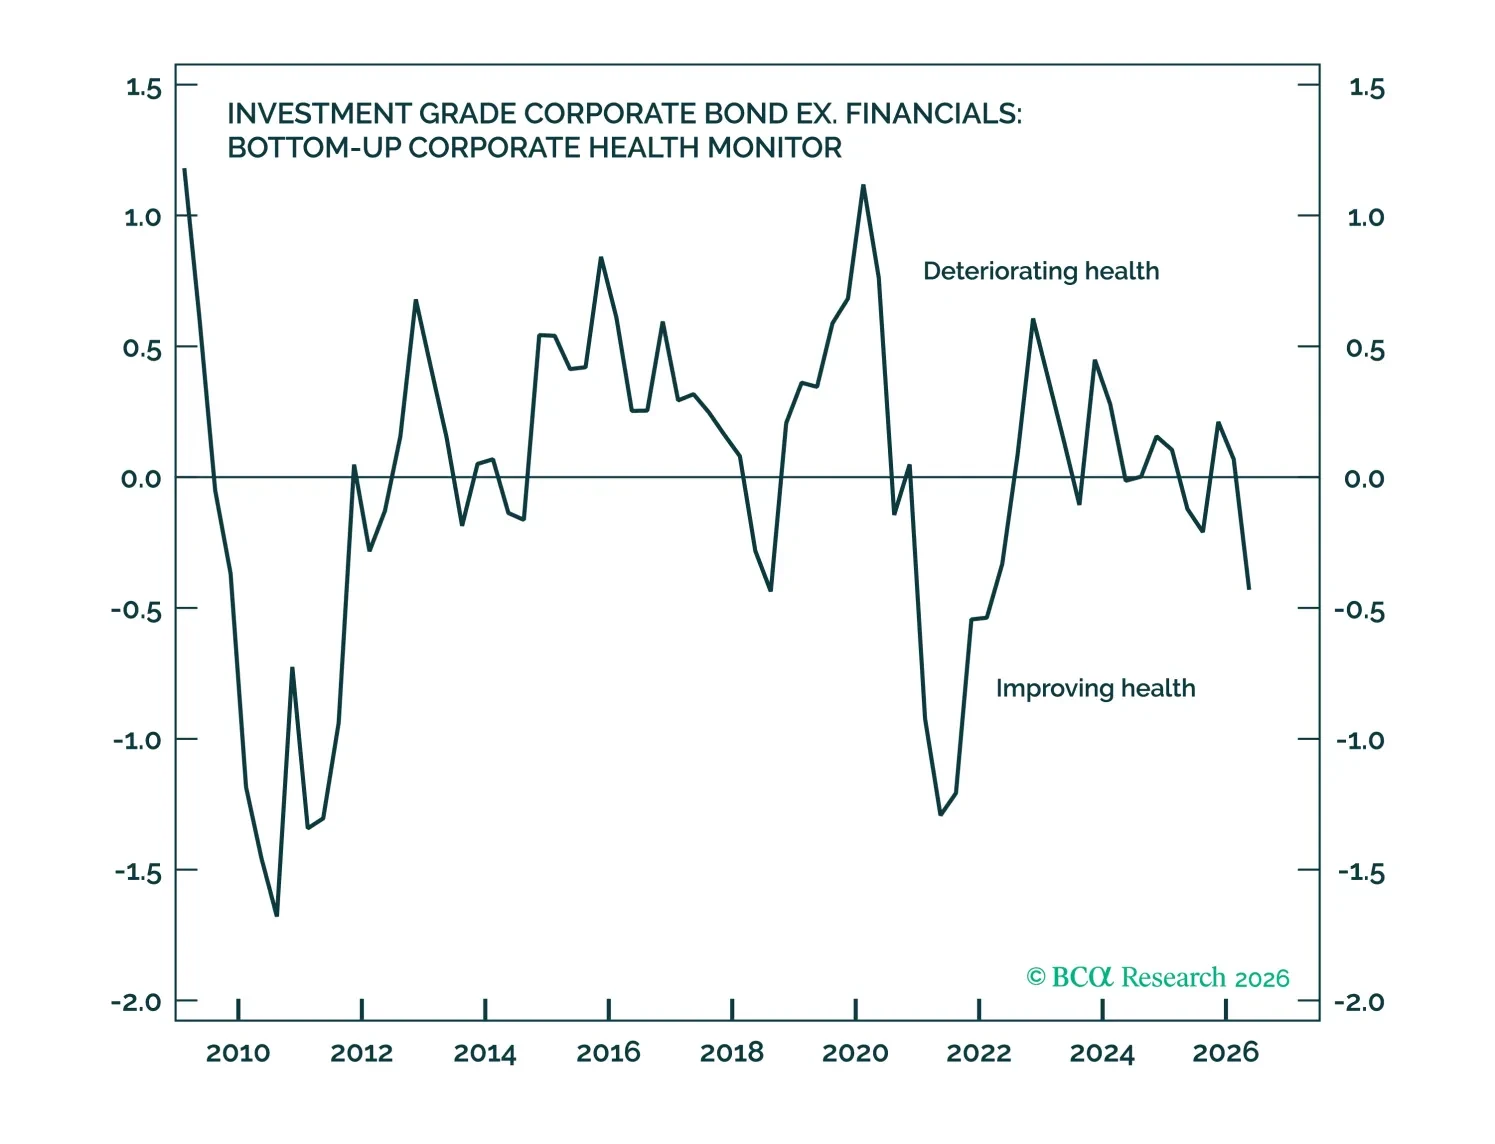

The Fed is unanimous in expecting a mild tightening cycle of no more than 75 bps, but that outcome is contingent on a rapid drop in core inflation in 2027.

August’s 0.3% increase in core CPI breaks inflation’s 3-month downtrend and is likely hot enough for the Fed to hike rates when it meets next week.
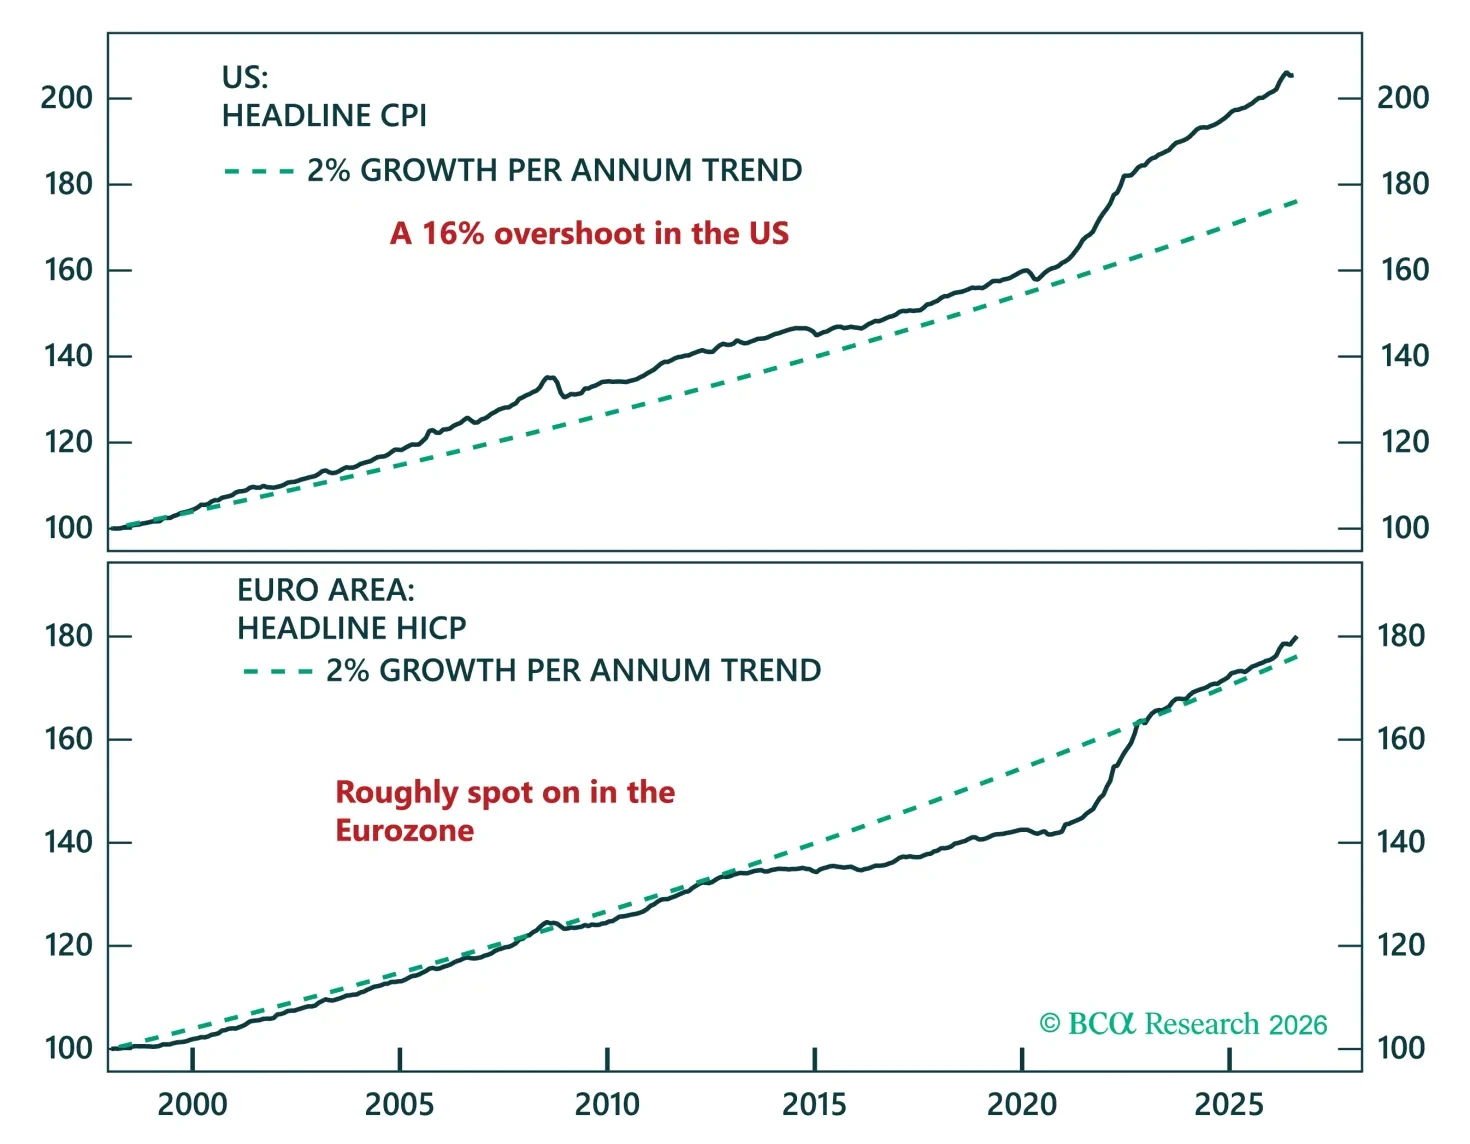
The ECB is winning, and almost nobody's pricing it in. A flatter Phillips curve, a shrinking term premium, a euro built to shrug off France, credibility is the trade.