Latest from BCA Research
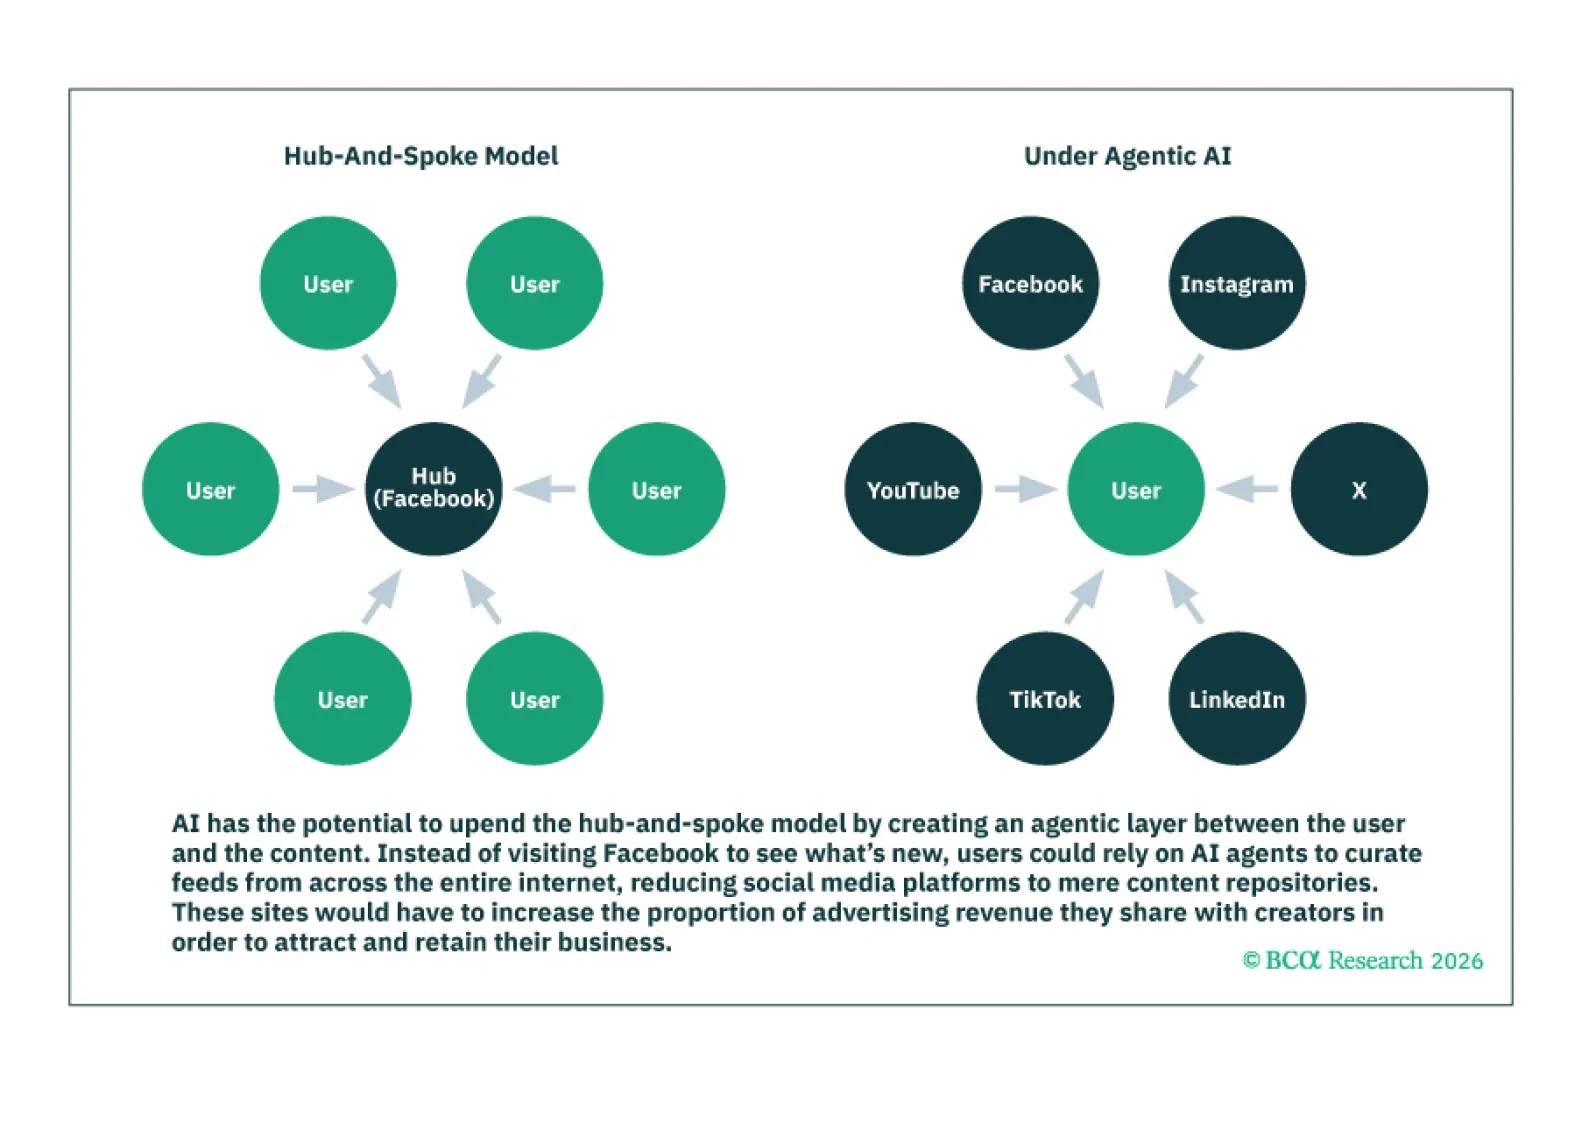

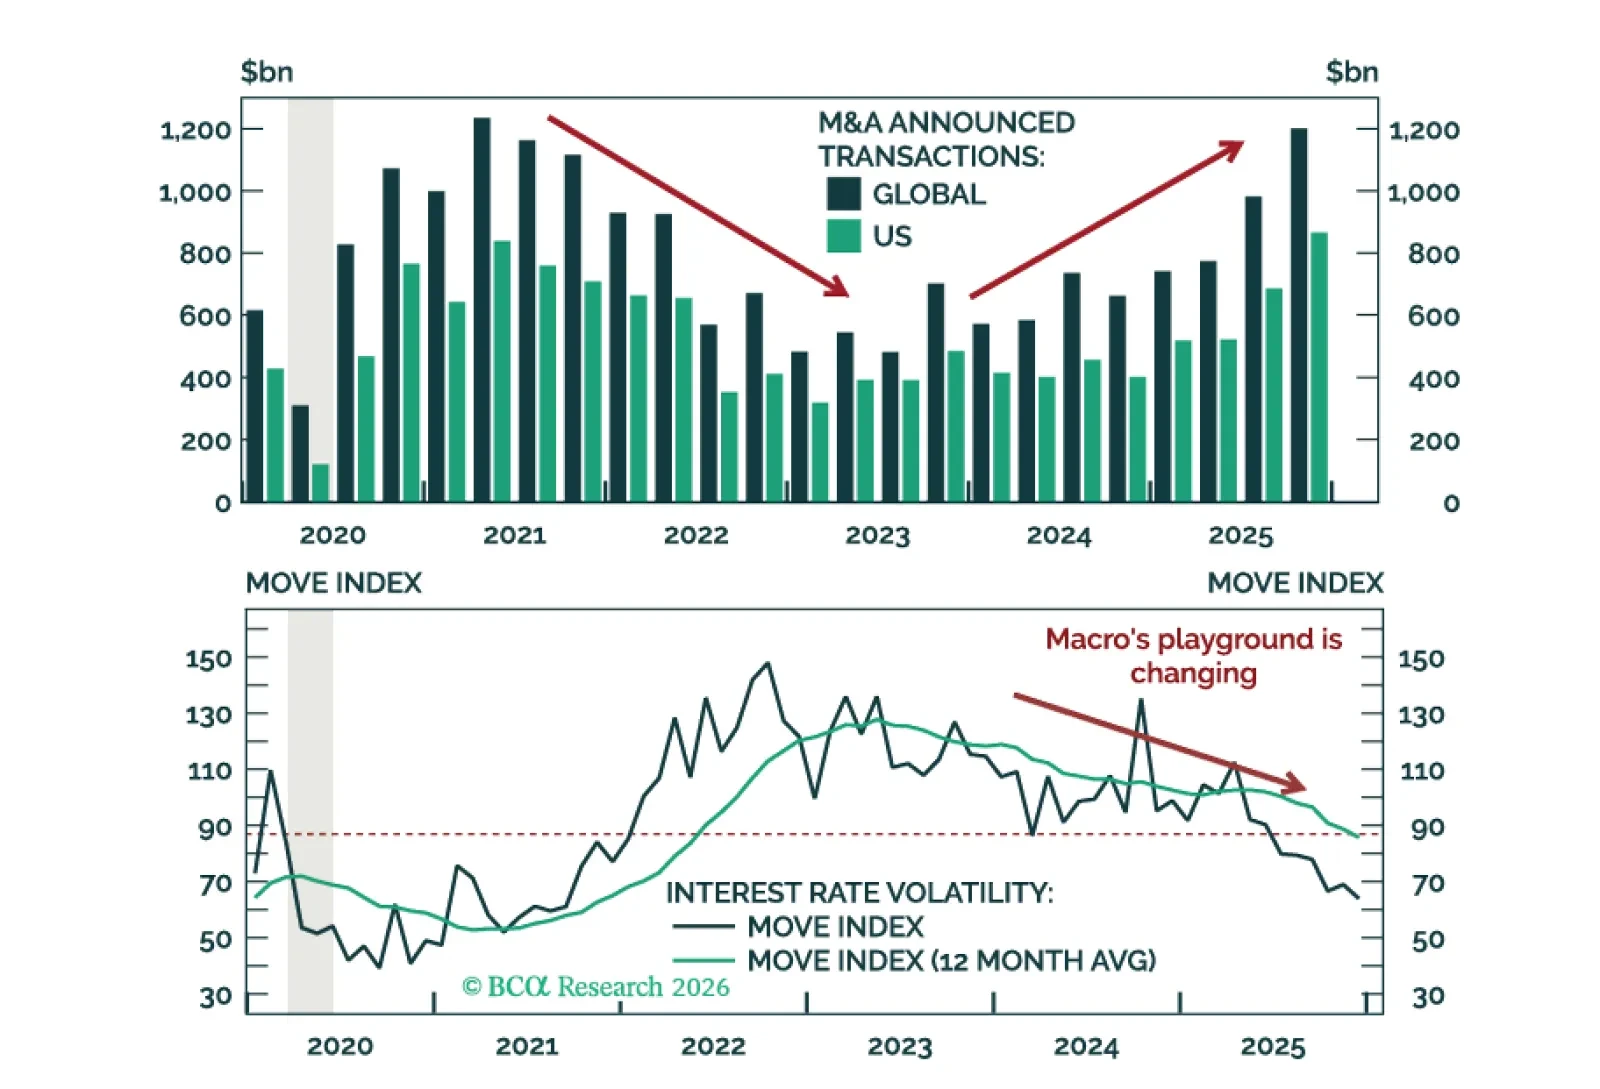
M&A activity finally reaccelerated in Q4 2025—it’s just the start. Macro Hedge Funds have outperformed with top-decile performance from Discretionary Macro—but that’s towards the end. We move Macro from overweight to underweight and Event Driven from neutral to overweight.

The president did not announce significant new tax cuts or economic stimulus.

This report examines the implications for Chinese exports and global trade in light of the US Supreme Court’s ruling on tariffs.

The US economy is in the Slowdown phase of the business cycle, according to our measure of aggregate US economic activity; growth remains positive but acceleration is negative. Historically, this phase more often resolves in reacceleration than recession. Recent market price action, from the index, to sectors, to relative industry performance, broadly reflects typical Slowdown phase dynamics.

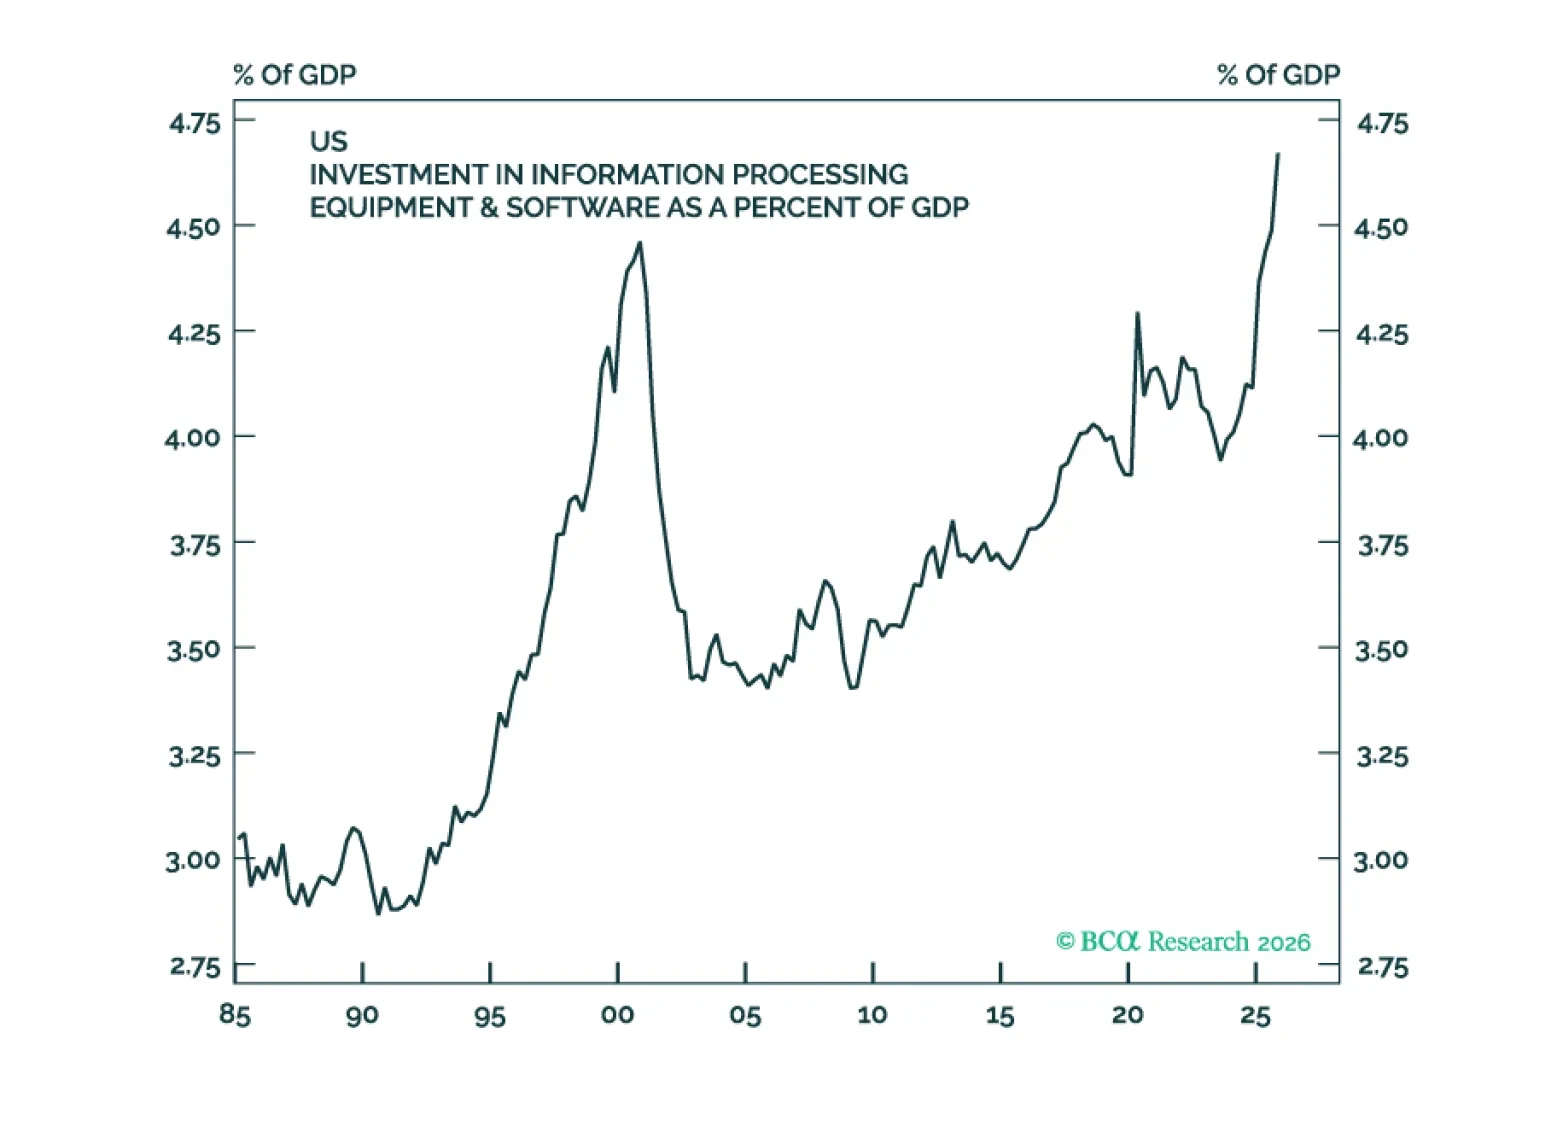
Fourth quarter US GDP growth clocked in at 1.4%, well below consensus expectations of 2.8%. We are not too troubled by the miss. The government shutdown weighed on the economy, with government spending subtracting 0.9 percentage points from growth. Real private final domestic demand – a clean measure of GDP growth that excludes government expenditure, net exports, and inventories – rose by a respectable 2.4%.
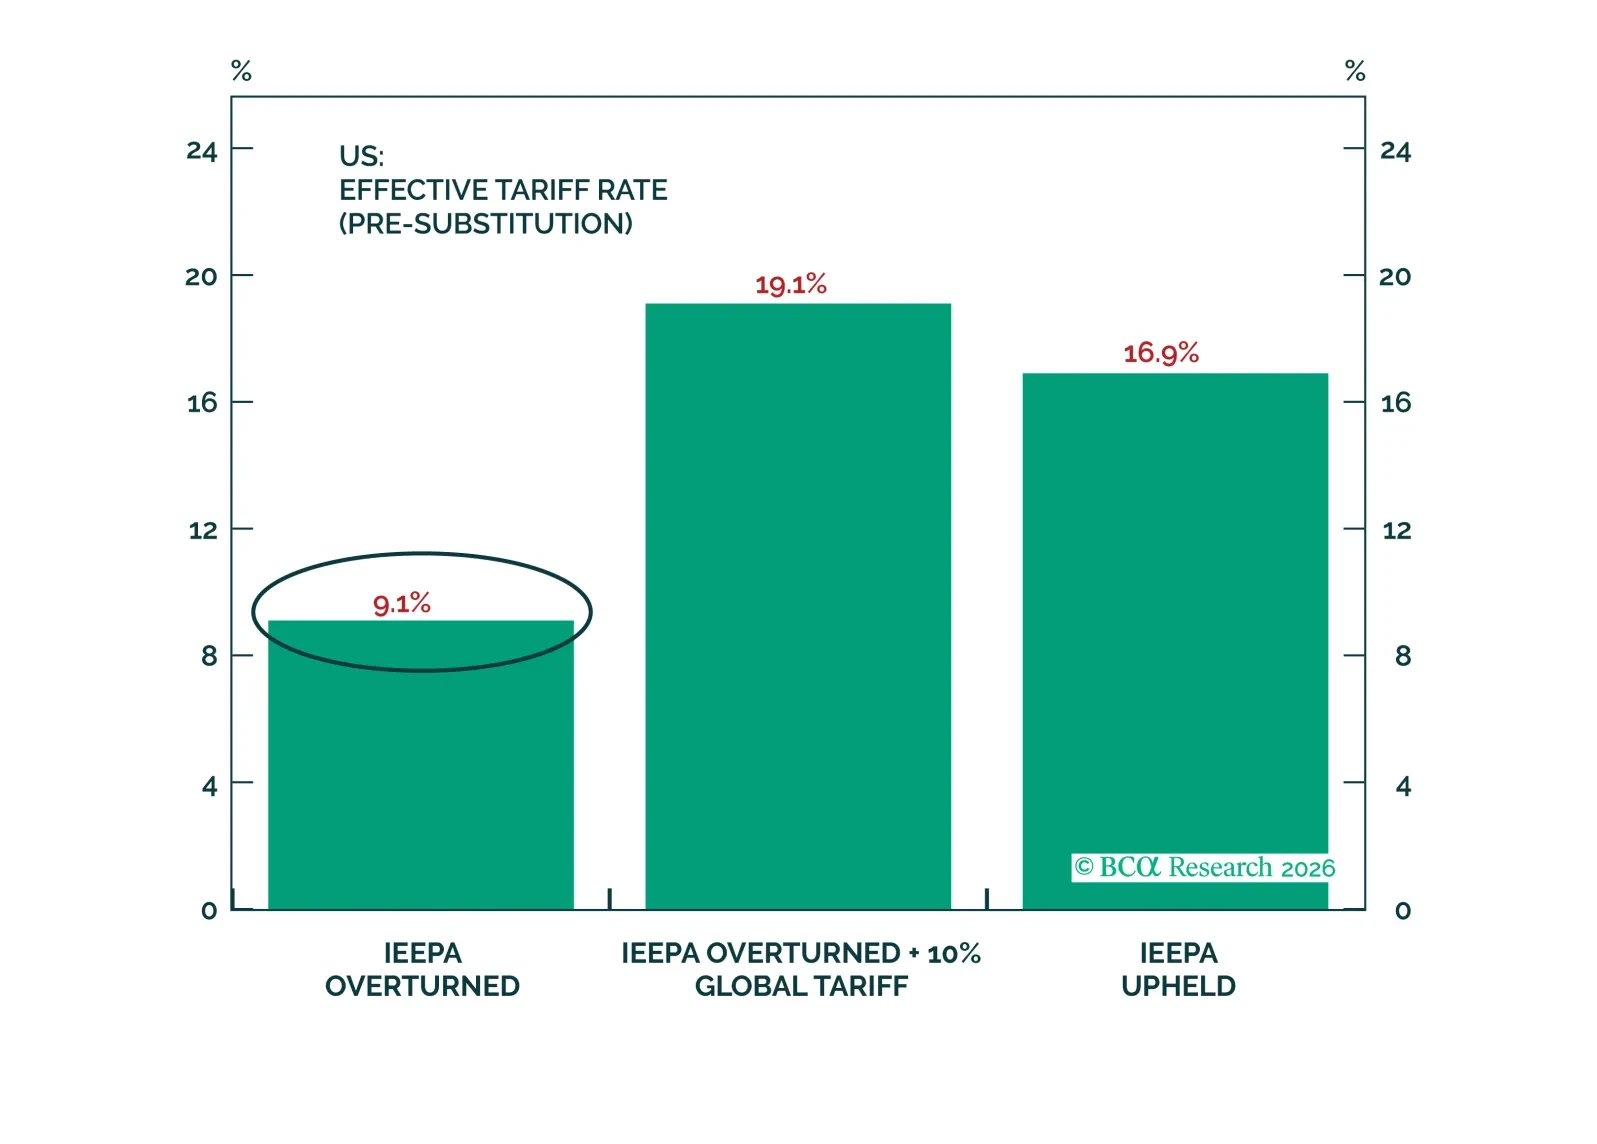
Trump is saving face with new tariffs but will avoid any major new tariff shock until 2027. For now, Iran risk will overshadow tariff volatility.

The “Chuck Norris Premium” is now fully in the market. Since the miraculously successful nabbing of President Nicolas Maduro on January 3, the odds of subsequent use of military against Iran increased.