Skip to main content

FICC

One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.

Explore FICC
Special Report In this Special Report, we outline the three themes that we believe will drive commodity markets this year: (1) demand growth will remain sluggish across cyclical commodities (2) supply-side developments will ultimately be bearish for oil prices, and (3) traditional relationships between commodity prices and financial variables may not hold.
Thoughts on the increase in bond yields and this morning’s employment data.
In this week’s report, we look at the likely trend for bonds yields and the dollar in the coming months.
Our Portfolio Allocation Summary for January 2025.
Special Report Our outlook for Fed policy in 2025 discusses our expectations for interest rates, the Fed’s balance sheet and the 2025 strategic review.
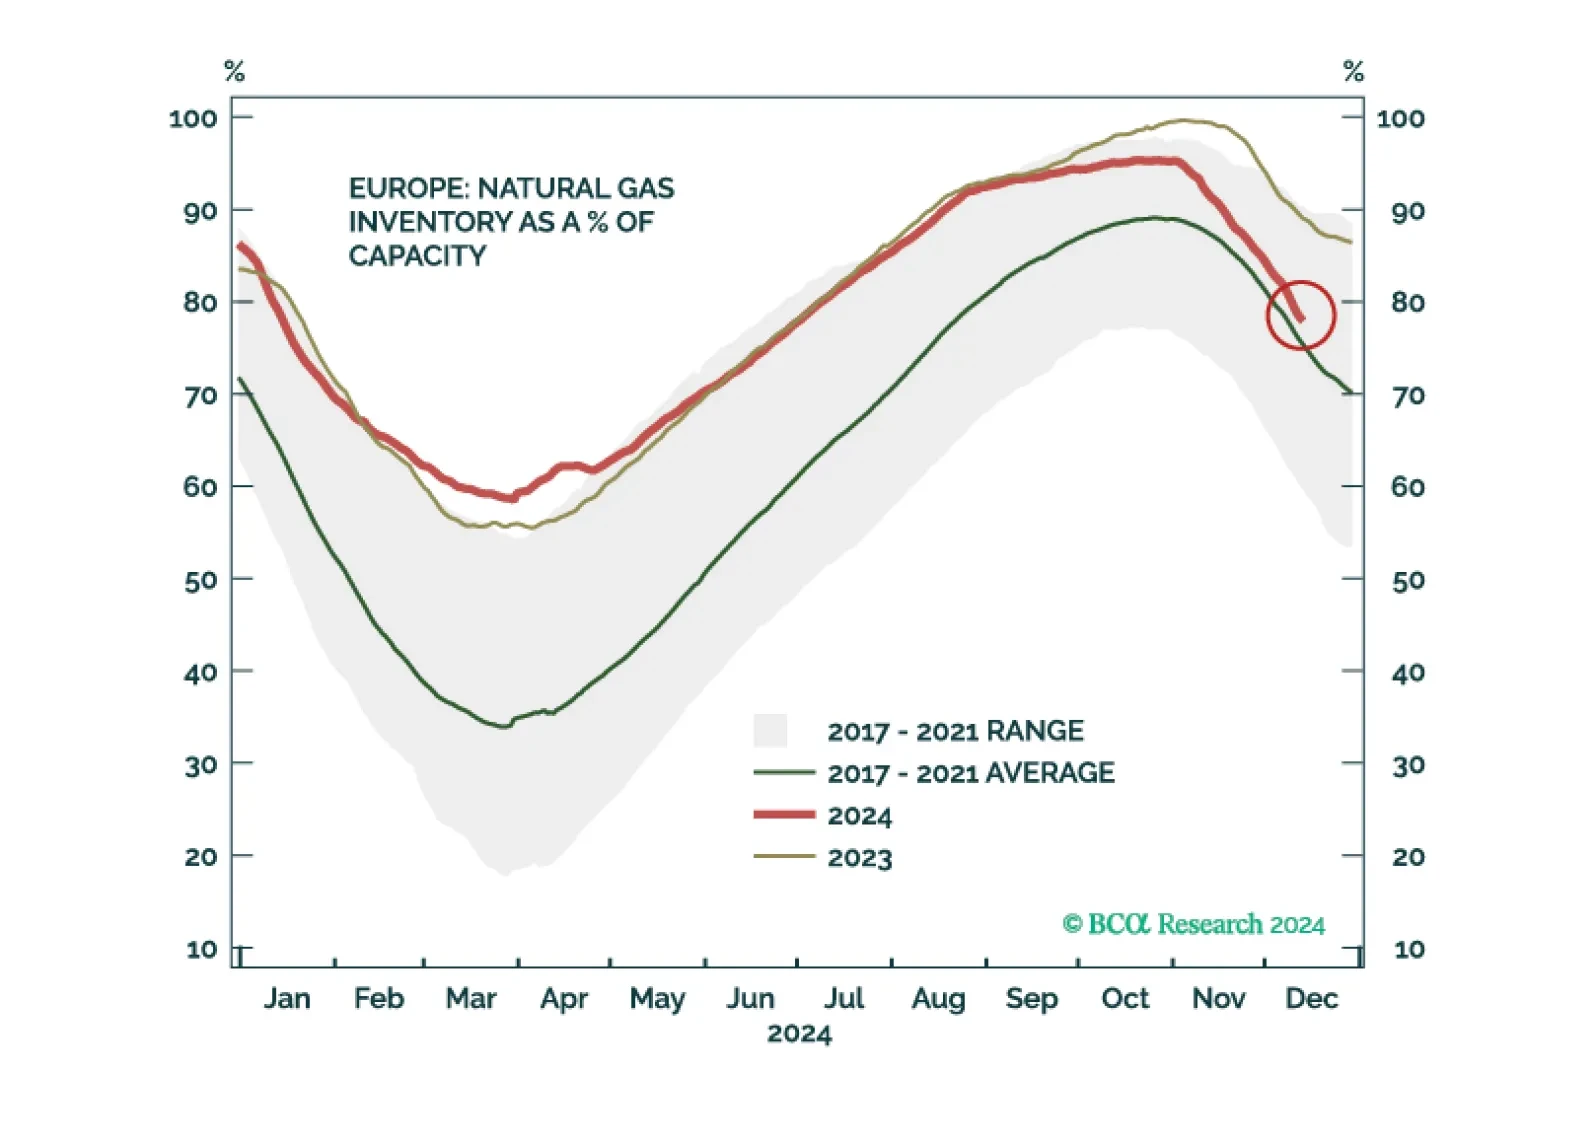
A confluence of both supply and demand factors contributed to the natural gas rally over the past few months. This trend could continue for a while longer. However, cyclical and structural factors ultimately argue against a sustained increase in prices.
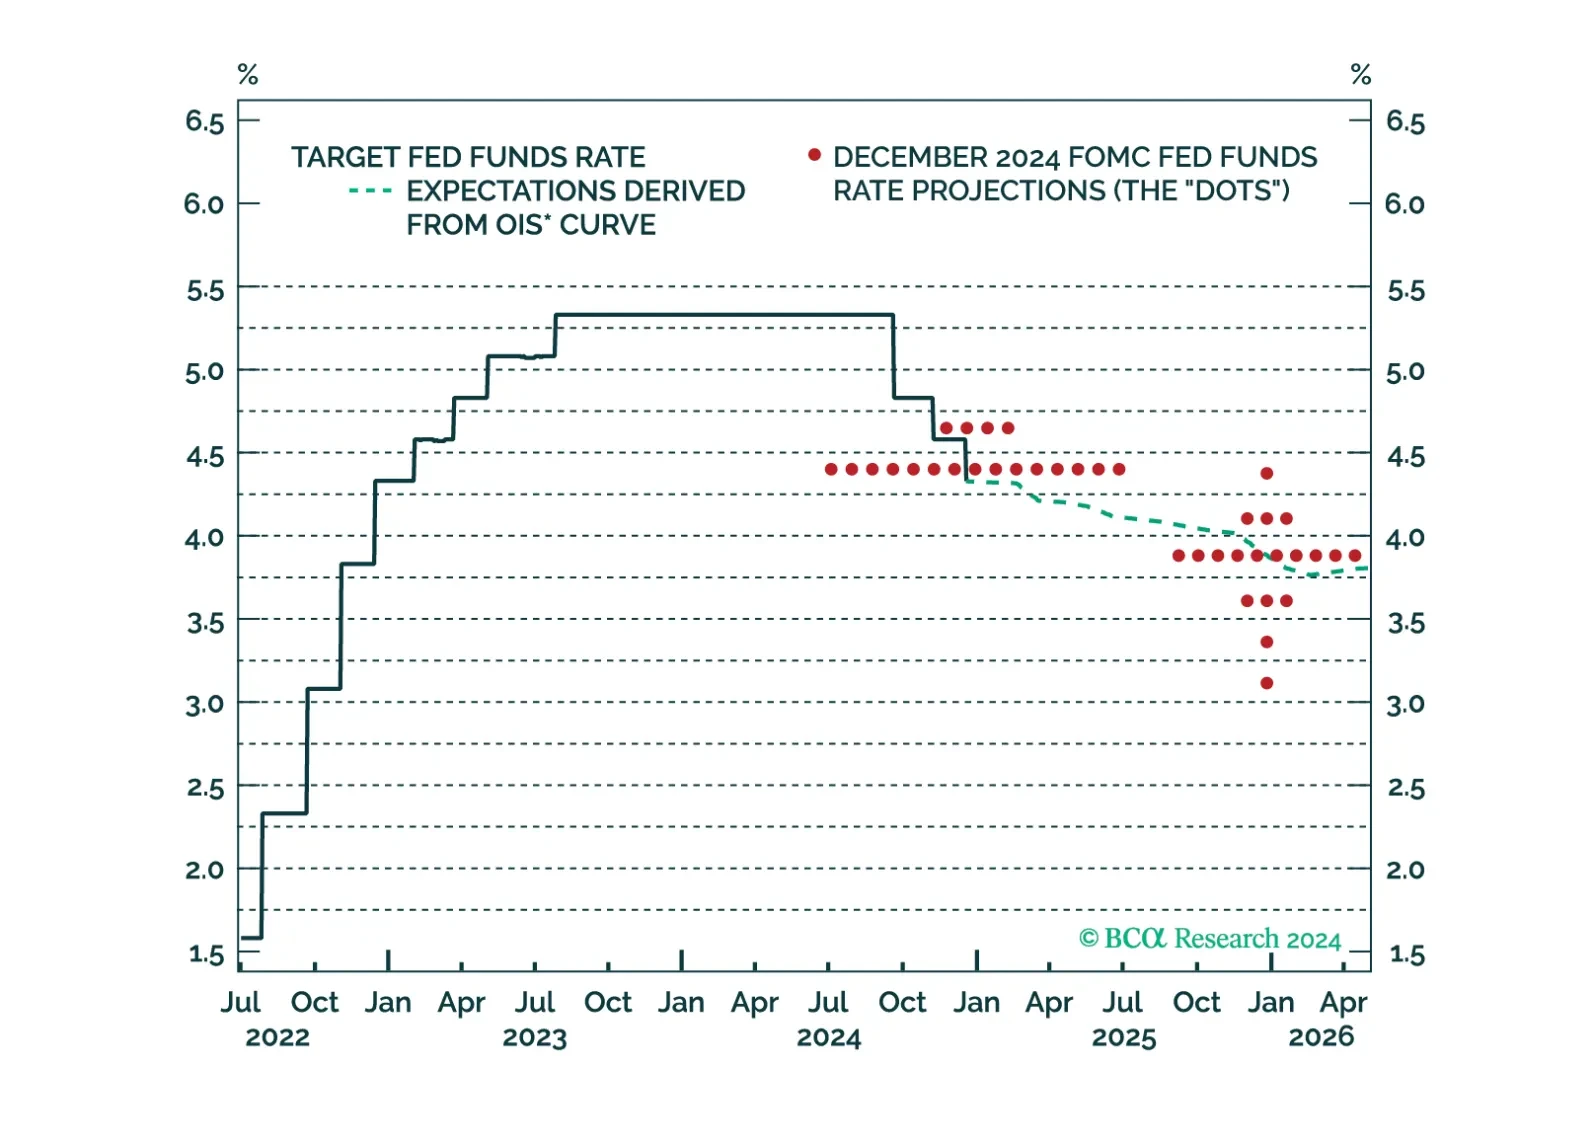
Our thoughts on this afternoon’s Fed decision and the bond market reaction.
Special Report This week, we present our key views for Global Fixed Income and FX for 2025.
Special Report Odds are rising that the trade-weighted US dollar will roll over and depreciate sometime next year. However, USD weakness will not be due to stronger ex-US growth. Rather, economic conditions in China and Europe will continue to underwhelm. Therefore, a weaker US dollar will not boost prices of cyclical commodities. That said, when we change our view on the US dollar, we will upgrade our stance on EM financial markets – especially EM domestic bonds.
Special Report We offer 5 key investment views for US fixed income markets in 2025.