 FICC
One macro framework for rates, FX, credit, and commodities, helping investors connect cross-market signals and position with clarity and conviction.
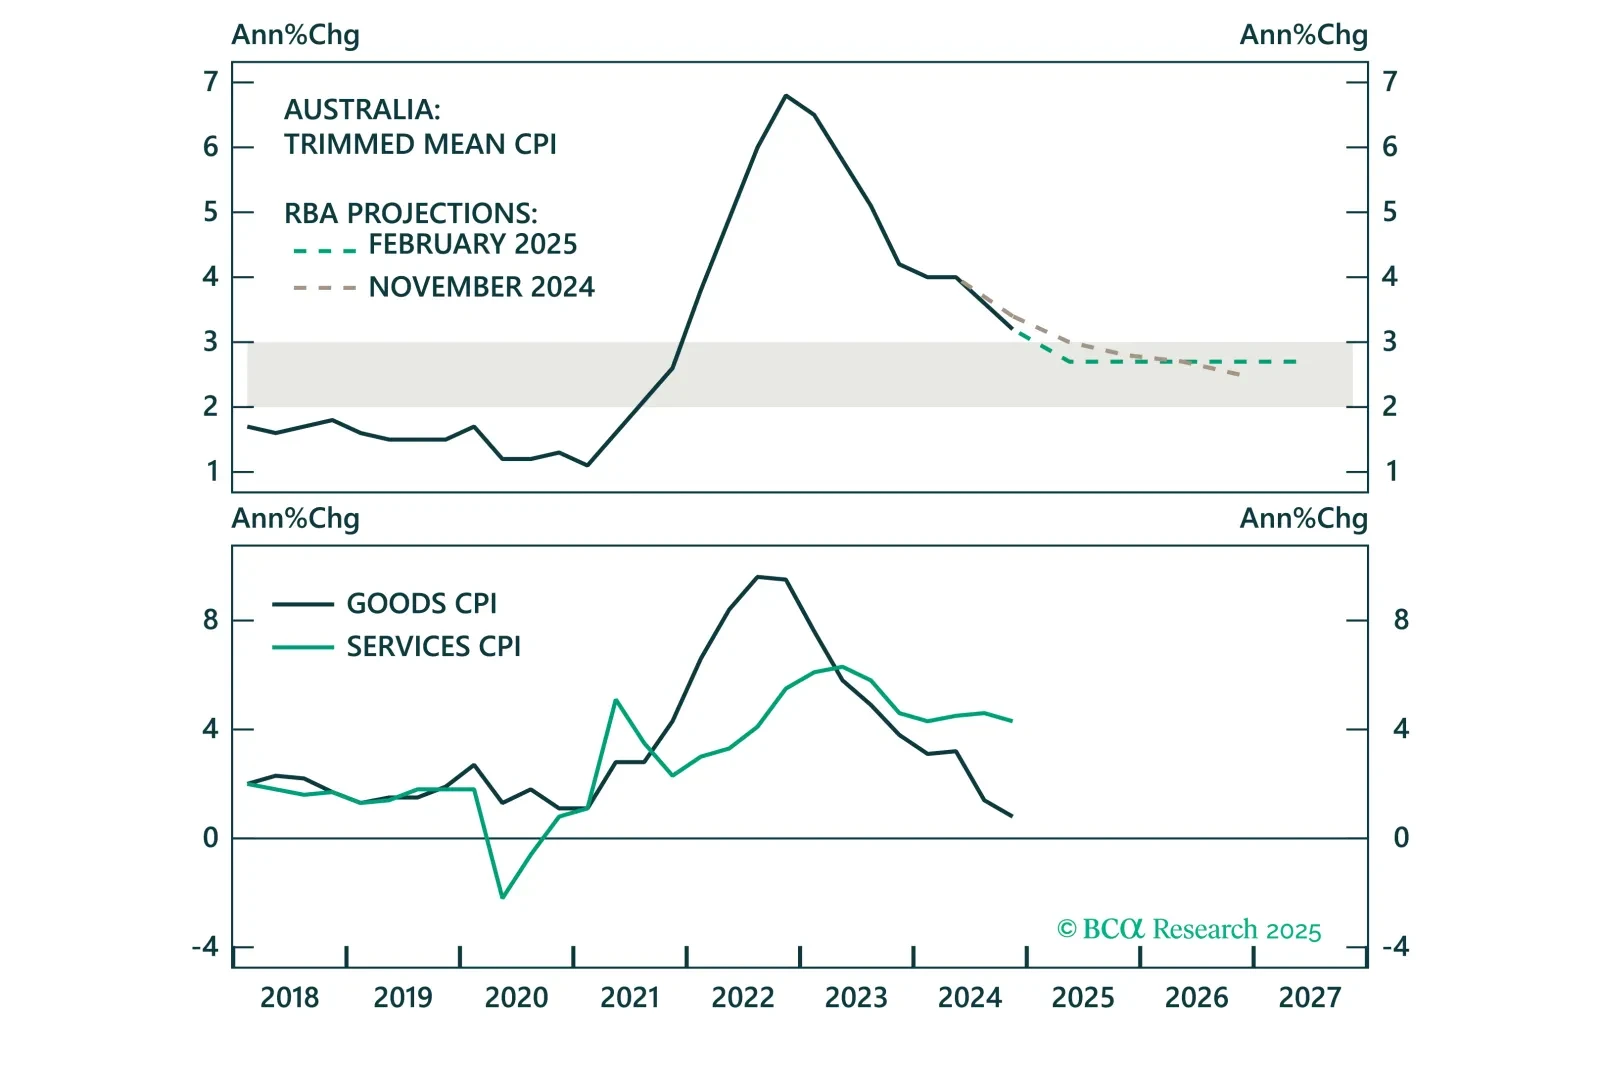
Overnight, the RBA cut the cash target rate for the first time since 2022, marking the beginning of the policy easing cycle in Australia. However, the RBA will proceed cautiously with further rate cuts, given a tight labor market and still elevated services inflation. This will keep Australian government bond yields elevated versus global yields, benefitting the Australian dollar.
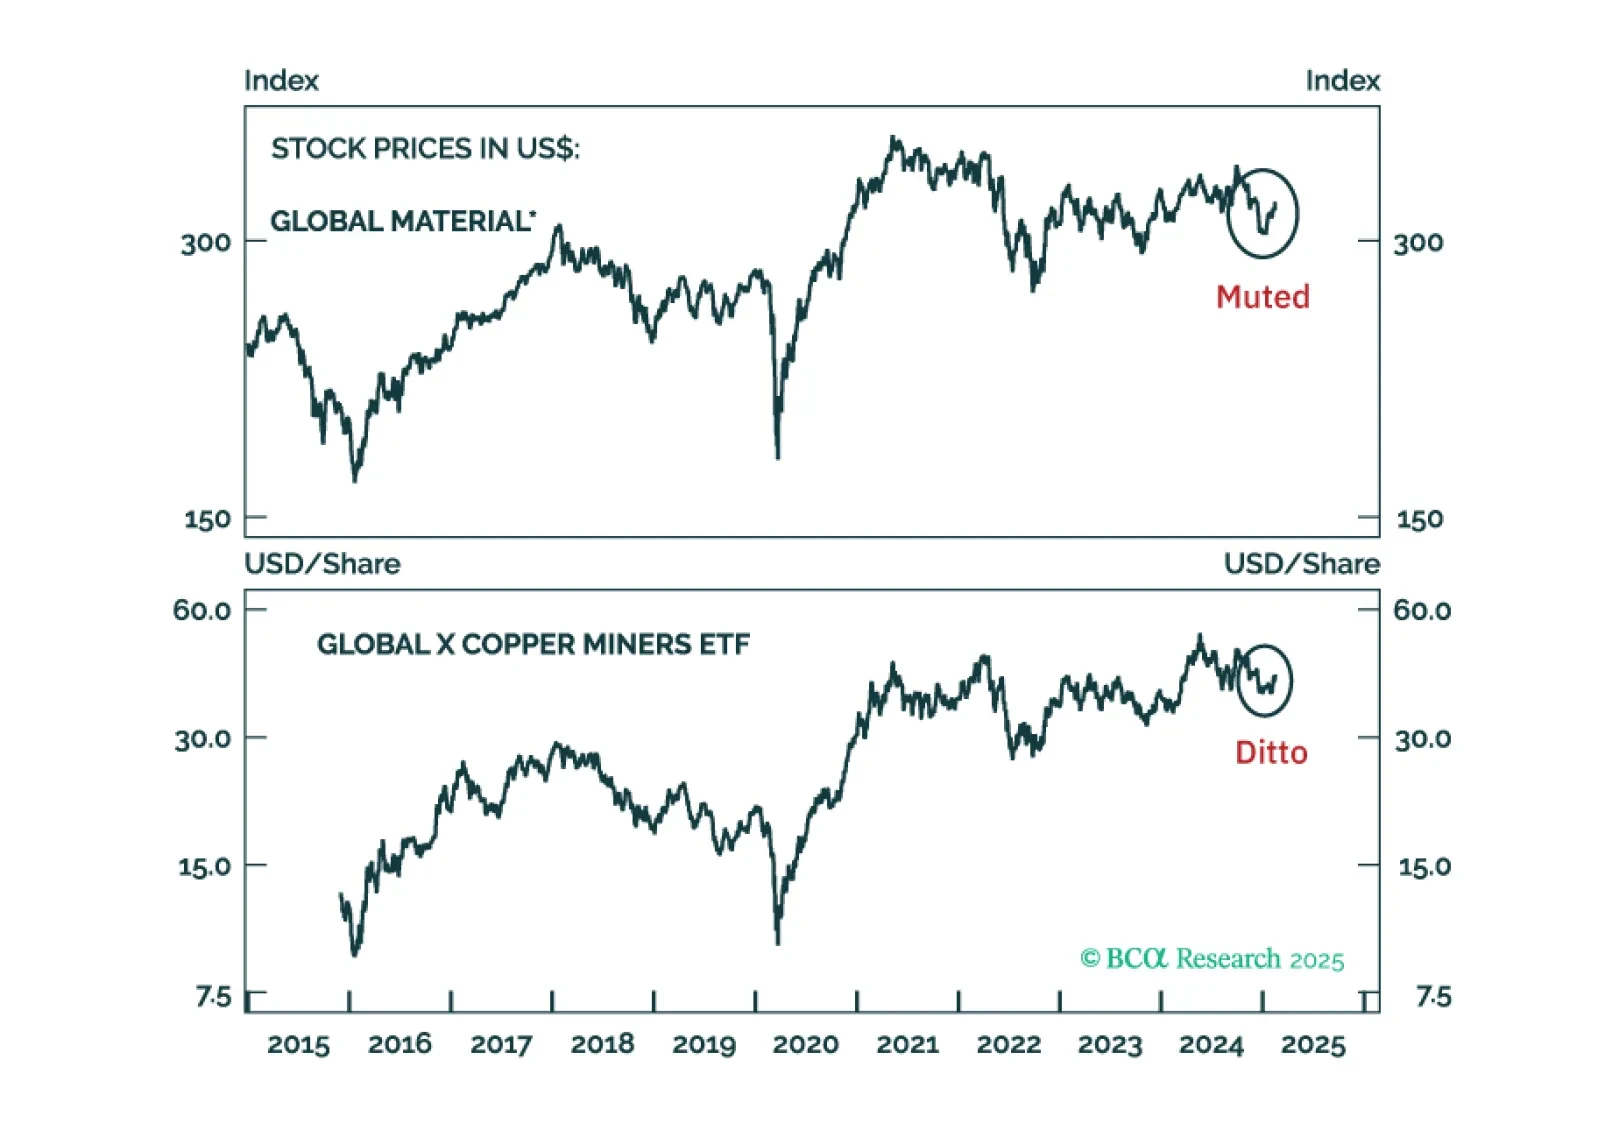
Expectations of US import tariffs drove the latest upleg in the prices of precious and industrial metals. However, there are no significant economic or political incentives for the US to impose import tariffs on these metals. Therefore, investors should fade the recent spike in gold, silver, platinum and copper prices. We are initiating a short position on silver as a tactical trade.
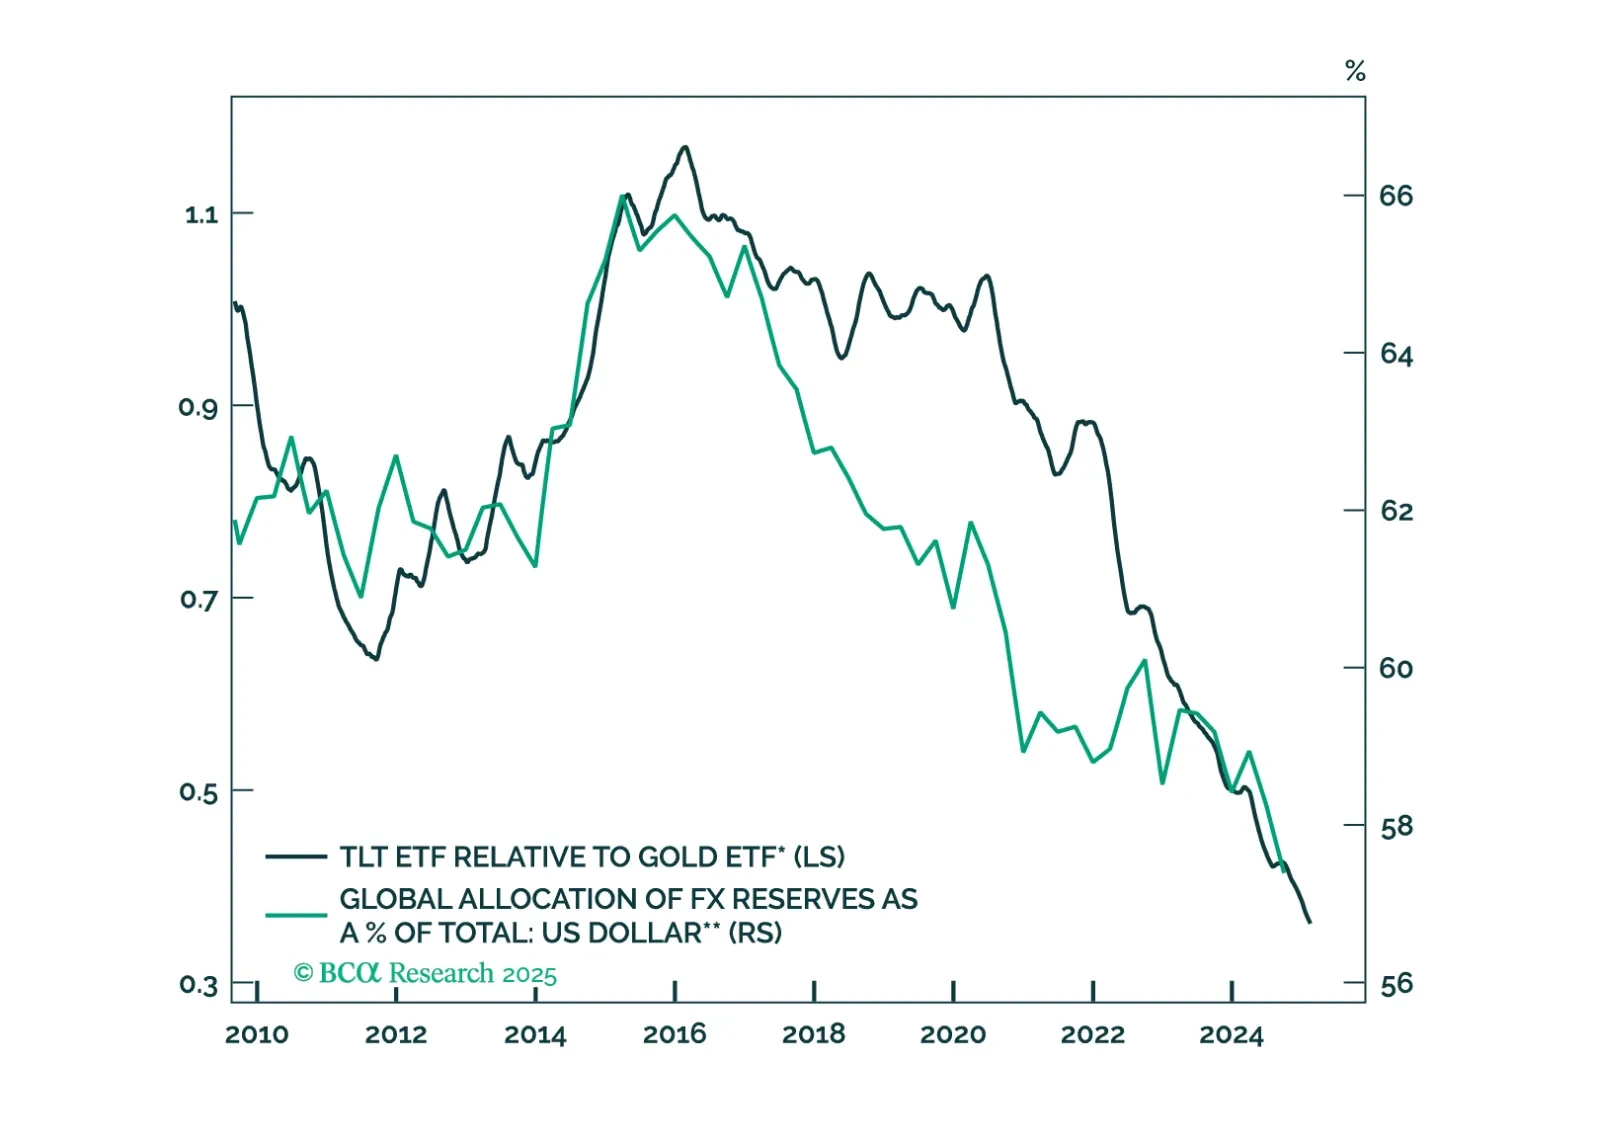
In lieu of all the geopolitical and economic news in media, this report looks at where next the dollar is likely to trend in the next one-to-three months. Our view is down, though on a cyclical horizon (six-to-twelve months), we would not be short the dollar, for now.

Some thoughts on this morning’s CPI report and its implications for the Fed and Treasury yields.


In this report, we reassess our bullish stance on crypto from early 2023, following Bitcoin’s recent all-time highs. While institutional adoption is broadening, there are also signs of excessive exuberance, speculation, and optimism. Given these conditions, a near-term correction appears likely. We are booking profits and will look to re-enter the market at $75,000.
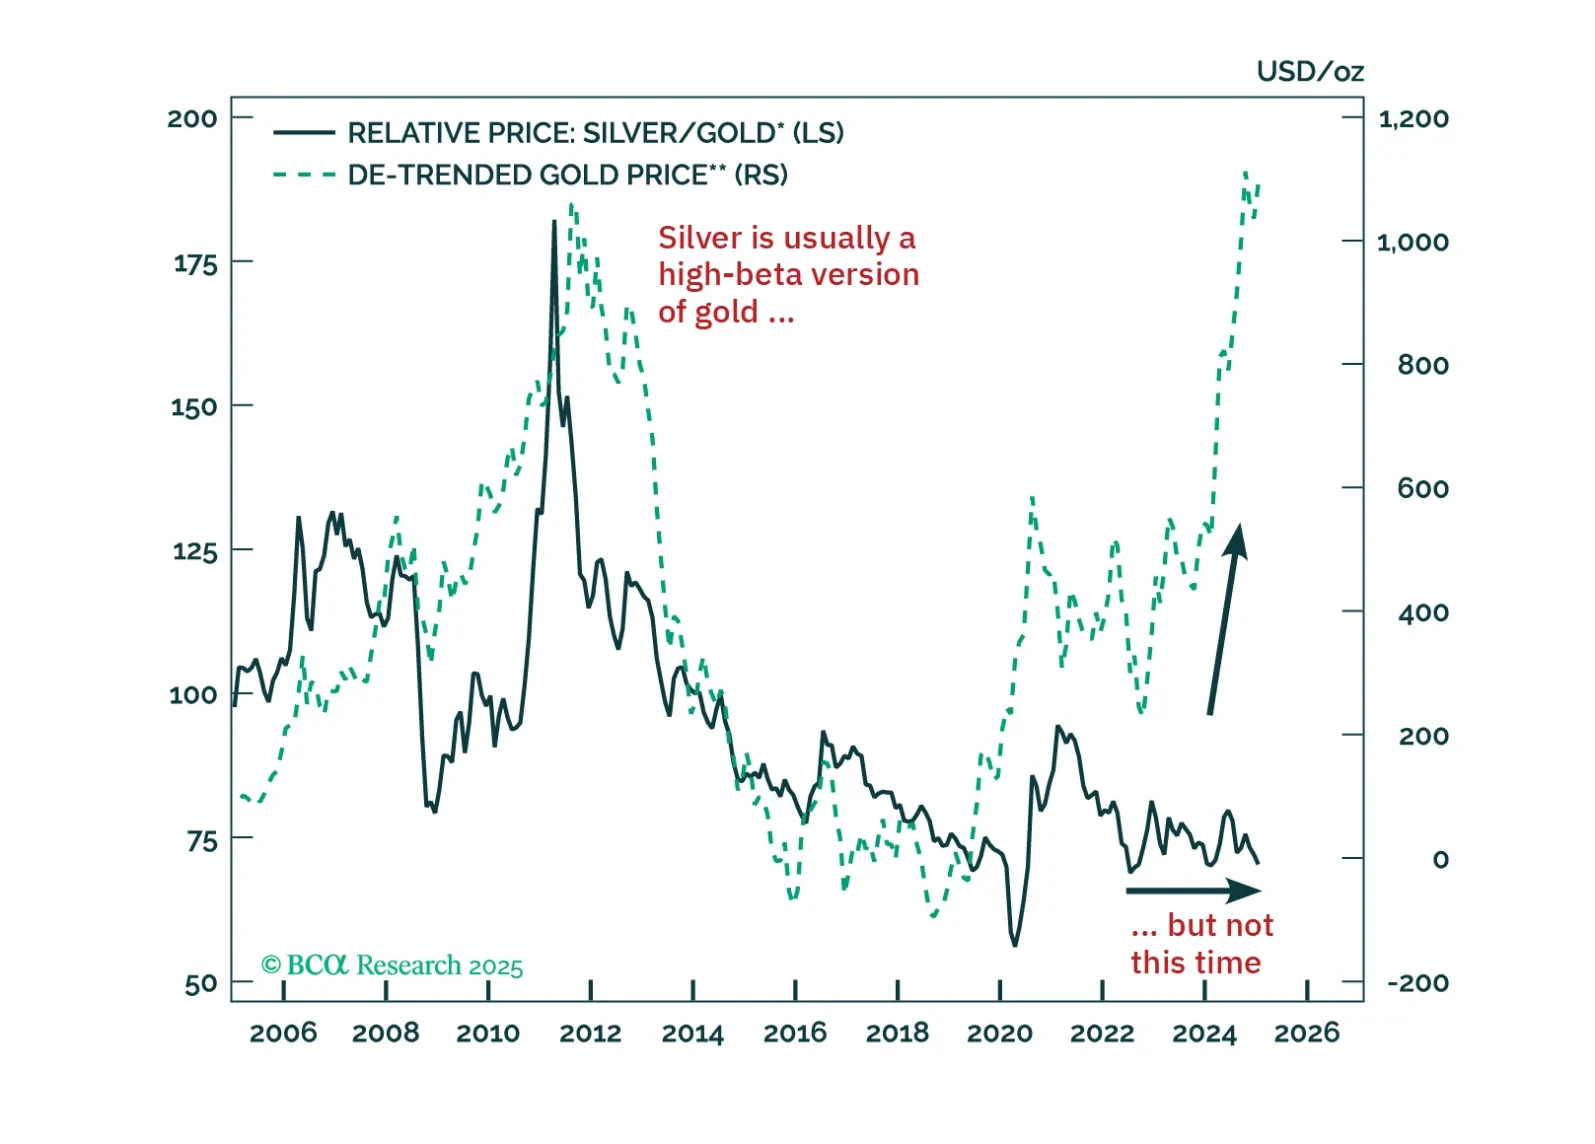
Last week’s tariff debacle kicks off a period of heightened global policy uncertainty under the new US administration. That is bad news for financial assets exposed to the business cycle. Meanwhile, it creates an opportunity for safe-haven assets to shine. Gold is capturing headlines for soaring to fresh record highs. Yet, what about the other precious metals? In this report, we argue that not all precious metals are created equal.
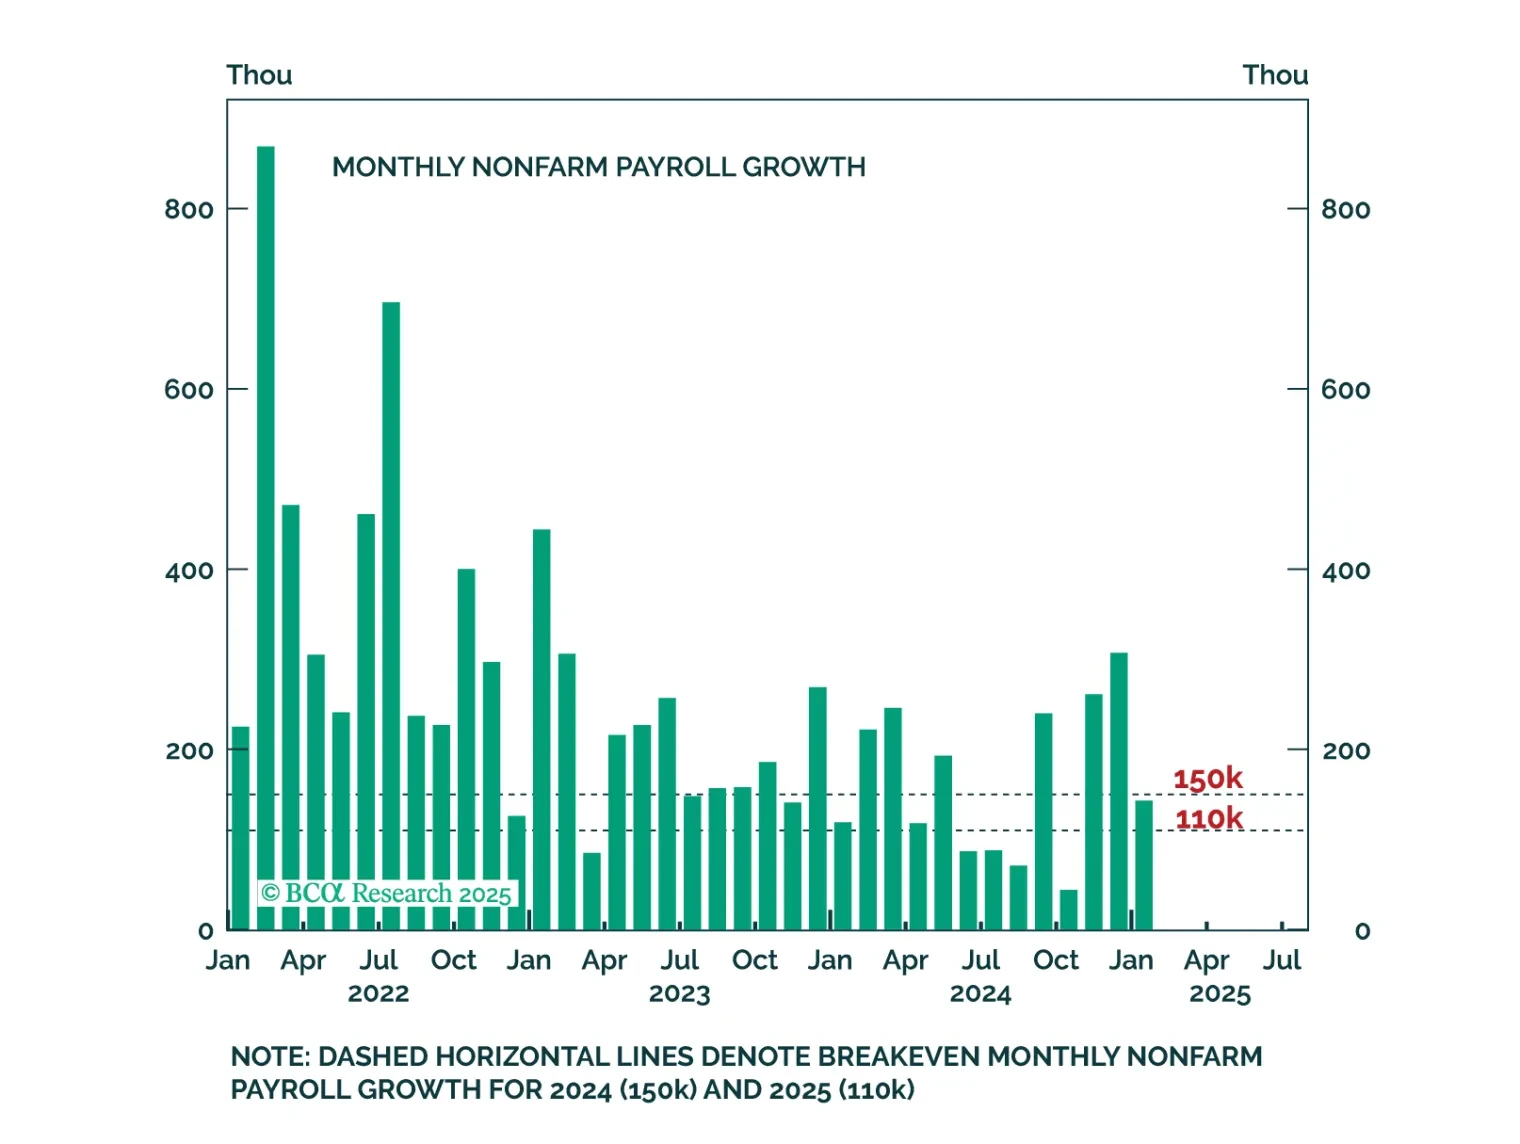
Some thoughts on this morning's employment data and Treasury Secretary Bessent's recent attempts to talk down the 10-year Treasury yield.

Following today’s Bank of England’s policy meeting, at which the policy rate was cut by 25 bps, we discuss our outlook for monetary policy in the UK. We expect the gradual easing to continue and discuss the investment implications for UK gilts and sterling.

Our Portfolio Allocation Summary for January 2025.